Fairpoint plc: Ditch the Ethical Qualms, Buy It

 Brief intro to Fairpoint (£FRP): from their own website
(http://www.fairpoint.co.uk/):
Fairpoint is a consumer financial services business focused on serving financially stressed consumers. Our mission is 'Making money go further'.
Our business is structured into the following primary business lines in order to serve the needs of this consumer group:
- Individual Voluntary Arrangements (IVAs)
- Debt Management Plans (DMPs)
- Claims Management
Fairpoint's Key Brands

Reasons to Be Attracted to Fairpoint (LON:FRP)
While you may not approve of the types of debt management services that Fairpoint provide (e.g. there are free debt management services available to indebted individuals), there are a number of solid investment reasons underlying my enthusiasm for this £58m market cap small-cap stock:
- Valuation is attractive;
- Profitability and cash generation are impressive;
- Income return is good in this ZIRP environment with a 5% dividend yield;
- Stock price momentum is picking up, breaking resistance levels to the upside;
- Acquisition strategy is cautious and sensible, delivering growth at a decent price.
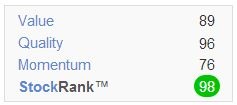
This is all summarised nicely in Fairpoint's UK StockRank:
Valuation: Cheap as Chips!
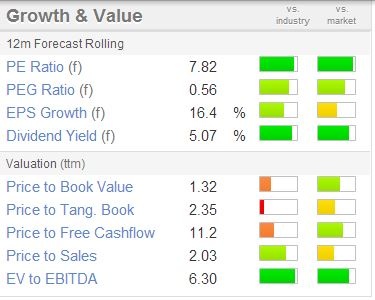
Whichever way you look at it, Fairpoint (LON:FRP) looks good value with a single-digit P/E and 9% free cash flow yield:
Income: a 5% Yield is not to be sniffed at!
Note not only that Fairpoint (LON:FRP) pays a 5% yield today, but that it is well covered at only a 40% payout ratio; not further that dividends have been steadily increased since they were initiated in 2010.
Growth: Double-Digit Top-Line Growth
Thanks in part to a prudent acquisition of law firm Simpson Millar, paid in part in shares via an earn-out (on targets set for June 2015 and June 2016), top-line growth should be double-digit both this year and next, driving sales from £28.4m at end-2013 to a forecast £36.1m by end-2015.
We can look at profit growth through the lens of the simplest 1-stage Gordon Growth Model, according to which, Fairpoint's internal growth rate is:
ROE x (1 - Payout Ratio)
= 11% x (1 - 40%) = 6.6%
This would in turn imply a long-term total return rate at around 12%, including the 5.1% dividend yield. But don't forget, Fairpoint's balance sheet is somewhat inefficient, with a net cash balance of £2.8m, which suggests that the underlying ex-cash ROE is closer to 13%, pushing the internal growth rate beyond 7%.
Profitability and Cash Generation: Very Solid
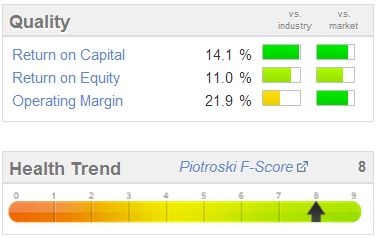
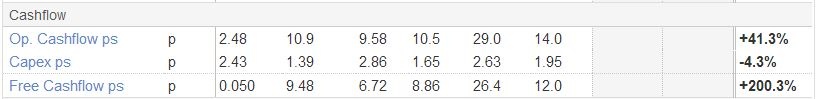
As the 96 Quality Rank implies, Fairpoint is high quality when running it by the numbers whether looking at profitability or cash flow:

Stock Momentum: Interesting Breakout
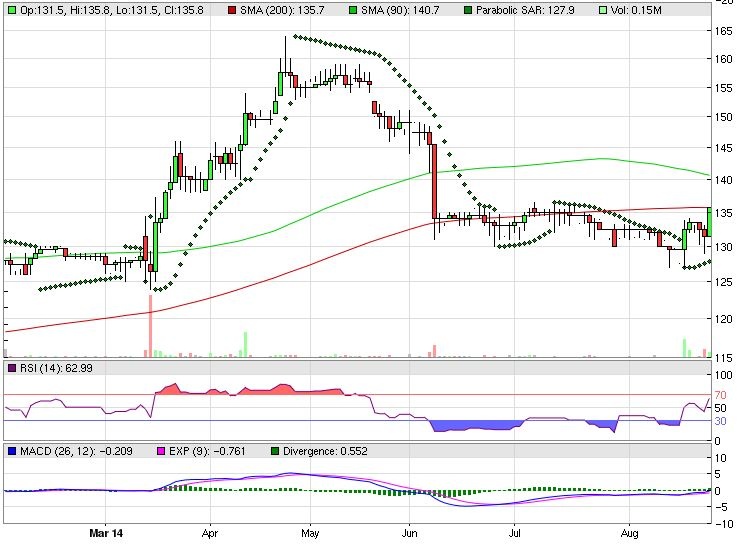
Fairpoint is breaking above a key horizontal resistance level of 135p; my first price target is thus 155p, the price gap that opened up on May 20. Beyond that, I am looking to around 231p, last seen in mid-2008 when business was strong (due to the weakening economy).
Stock Ownership: Extremely Concentrated Already
Another interesting feature of this stock is that stock ownership is extremely concentrated, making the stock vulnerable to an upwards stock squeeze in the event of any good news:
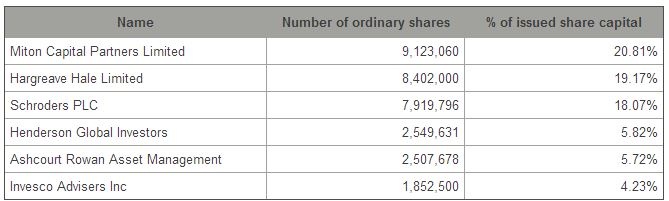
Three small-cap specialist fund management firms hold nearly 60% of the outstanding shares, including the top-ranked UK small-cap fund manager Gervais Williams at Miton (who runs The Diverse Income Trust plc amongst other funds - in which Fairpoint (LON:FRP) is the third-largest holding at 1.8% of the investment trust).
So any good news could see a big upwards squeeze in the shares in short order!
As always, please Do Your Own Research, however I have hopefully given you some points to chew over!
Disclaimer: I hold Fairpoint shares in my SIPP
Edmund
The Idle Investor
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
10 comments
I really struggle on the morality of investing in companies such as Fairpoint and others that profit on spreading misery. Here are some examples. In the gaming sector there are some very interesting companies whose business centres around attracting gamblers and increasing their gambling habits. Should I shun them completely? How about defense companies such as British Aerospace which sell arms to middle east countries. It was reported last week that IS have captured an arsenal of sophisticated weaponry sold to Iraq by the US, UK and France. Do I blank out this sector completely? Not to mention cigarette companies and booze retailers such as Majestic Wine. The common thread is that they all make profits by increasing misery and ruining lives. Where do you draw a line? Difficult.
Console yourself by thinking of the fun, and possible positive experiences, people got running up those debts, getting plastered, etc. Too bad if it went on big tv sets etc instead of something entrepreneurial or educational or good experiences. i draw the line with the activities which don't seem in any way positive - the gambling, smoking.
I would be very surprised if interest rates rose any time soon. The prospect of the UK following Europe and being sucked into a deflationary spiral is becoming more realistic every day in my view.
What never ceases to amaze me is why the DMP part of this business exists at all. With many decent free alternatives, why is anyone still paying for the service? Surely that is a basic failure of the market. Would you want to invest in a company that is reliant on that failure continuing? It doesn't really scream sustainable future earnings. The business is also easily subject to changes in the law. I vaguely remember a few years back that the government were planning to revamp the out-dated Administration Orders (essentially a court mandated DMP for anyone owing <£5k) and create a court controlled system of DMPs. That didn't happen, but it's not unreasonable to assume they revisit that or outlaw fees for DMPs at some point in the future if the growth you suggests actually happens.
Hi Edmund,
Interesting write-up, thanks.
In my view this stock is cheap for a reason - because earnings are unsustainable, so they are having to bolt on new sources of income to offset declining historic earnings. The decline is because they are focussed on doing CVAs for indebted consumers - mainly from the overhang of excessive credit card & personal loans that culminated in the 2008 credit crunch. So I would imagine that by now, anyone who was likely to get into problems with that debt, would have already done so. Higher mortgage interest rates might have some impact in boosting Fairpoint, but I think they've already eaten most of this particular sausage.
Furthermore, they were making hay on the PPI mis-selling thing too. That again only has a limited lifespan.
Which bandwagon will they jump on next, I wonder? Pawn shops? Payday lending? However you look at it, this business has a nasty smell around it - i.e. it is a group of people who are actively exploiting the problems of the financially troubled. Personally I wouldn't want to receive a 5% divi, knowing that it was made by exploiting the poor in various ways.
Therefore for me, the question marks over sustainability of earnings, and the poor ethics of the business activities, rule it out. I'm not seeking to impose my views on anyone, just offering one viewpoint. Basically, this company is cheap, but for a reason or two.
Regards, Paul.
Very fair point Paul. ;)
Another interesting feature of this stock is that stock ownership is extremely concentrated, making the stock vulnerable to an upwards stock squeeze in the event of any good news
....or, of course, a sharp downwards squeeze in the event that one of these "concentrated" holders gives up on it and sells out.....
According to 31/7 trading update:
Group net debt as at 30 June 2014, including asset related finance, was £7.1m (31st December 2013: net cash of £2.8m),
Further acquisitions are also payable in cash.
Hi there! Well, the recent acquisition is a type of diversification that should lead to new avenues of (related) business growth, while I think that we will also see lots of home owners getting into difficulties even before any new economic downturn as they are so heavily leveraged (given these historically low interest rates). When the BoE finally starts to raise base rates, even slowly, this will have a significant impact on households who are just managing currently to make their mortgage payments...
Hence why now is a good time to get into Fairpoint (LON:FRP), before this new growth kicks off in earnest ;-)
Edmund
Thanks for this Edmund - this is one that has come up on my screens for a while. I note a few people think that there is little room for growth in its core business (hence the recent acquisitions of new revenue streams) but surely as interest rates rise more and more people will find themselves in financial difficulty? This could lead to a flood of new potential customers