Small Cap Value Report (12 Sep 2014) - NBU, BOO, MCM

Good morning!
Chinese stocks - I've warned readers here many times about the risks of investing in AIM Listed Chinese stocks, indeed I personally have a permanent bargepole rating on them all, for a variety of reasons - the main one being that things are very often not what they seem. So you cannot rely on any facts or figures about these companies, hence they are impossible to value. There are numerous other red flags, such as constant insider selling, accounts that don't stack up - e.g. huge debtors (nearly always the biggest "tell" that something is wrong), negative cashflow despite big profits, unrealistically high profit margins, etc etc. I just treat the accounts of Chinese companies as works of fiction, it's safer that way. Which brings me on to;
Naibu Global International Co (LON:NBU)
Share price: 36p
No. shares: 58.6m
Market Cap: £21.1m
Shares in this maker of sports shoes have looked inexplicably cheap for a while, with the PER hovering around 1. That's nearly always a sign that things are not what they seem. I can only think of one situation where a PER of 1 turned out to be the bargain of the year, and that was Trinity Mirror, as I explained in 2012, here, when the shares were just 25p (they 8-bagged in the year or two after that). In all other cases that I can remember, a PER of 1 usually means there's something badly wrong.
I've only reported explicitly on Naibu once here, because it has always been under my blanket bargepole rule for Chinese stocks, so there wasn't much point in reporting on the figures. As I explained in my report from 5 Aug 2014 the only point with Naibu that was intriguing, was that it had started paying dividends - which of course made it look as if the company was genuine. At the time people doubted whether the dividend cash would actually be paid, but it was, twice I think? So I was still slightly unsure about whether Naibu could be genuine after all? I was 95% sure it wasn't, but the divis kept a 5% window of doubt open.
That window has slammed shut today - the interim results are out today, and follow the usual pattern of high profits but negative cashflow. Despite the large cash balance, the company has cancelled the interim dividend. The reasons given look ridiculous to me - that the cash is required for capex to build factories, despite there being no reason for doing so - 80% of production is currently outsourced, and the company makes about a 20% operating profit margin. So there is no valid reason at all to build their own factory.
My opinion - With the dividend passed, I think the game is up now, and these shares have an intrinsic value of zero in my opinion. I think the motivation for the previous dividends was probably an attempt to pump up the share price, to allow more insider share disposals at a much higher price. The market didn't buy that, and the share price remained weak despite the divis, so they've now been cancelled. The next logical step is for the shares to de-list, and investors are highly likely to receive absolutely nothing in the future in my opinion. I could be wrong, but why take the risk, when the evidence is now so clearly pointing towards my view being probably correct?
I'm not saying that all Chinese stocks are dodgy, but enough are to make it too risky to bother trying to sort the wheat from the chaff. This table, courtesy of AIM journal, shows the lamentable share price performance of AIM Chinese companies since floating. Bear in mind that the period covered was a boom market for small caps, where most things rose 50-100%, so for so many of these to be negative is very poor. I think this table will look a lot worse in a few months time. Most of these stocks will de-List in the coming months/years in my view, so they are all going on my bargepole list.
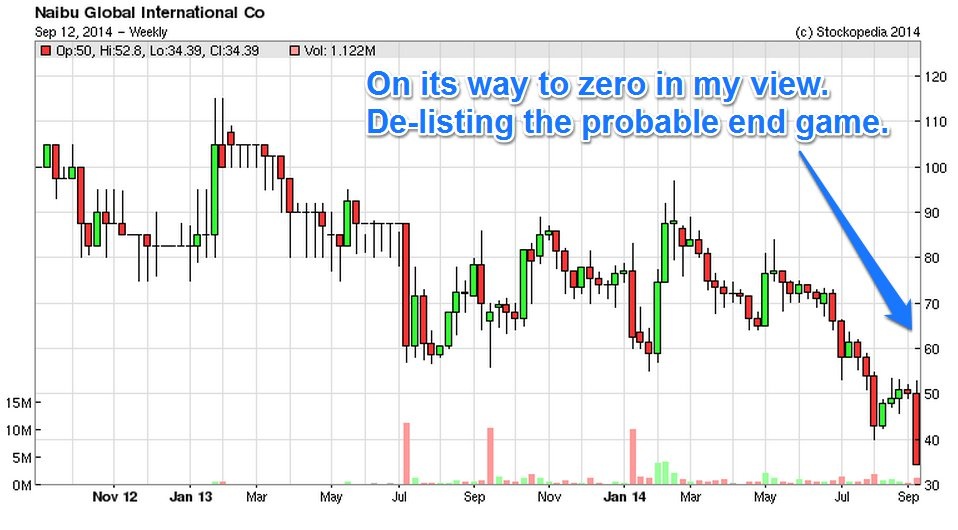
The spikes up on the chart below were caused by tipsters flagging up the "bargain" shares - very much a case of them not being able to see the wood for the trees I'm afraid. One has to be a bit more shrewd in this game than to just take numbers at face value. Lots of accounts are wrong, and often deceptive, and the fact that they've been audited doesn't make much difference. You have to question everything, and if it doesn't look right, that's often because it's wrong.
Boohoo.Com (LON:BOO)
Share price: 43.13p
No. shares: 1.12bn
Market Cap: £483.1m
BooHoo is an online fashion retailer. The market cap is larger than I would normally mention, but I'm going to cover it here because in my view it's a good company, and if things go well then I reckon the shares could be a good long term investment. Although the rating is high, so it comes with an additional risk warning.
It got a brief mention here in my report of 4 Aug 2014, in the section about ASOS. People are always looking for the next ASOS, and I think this could be it. In some ways it's a better business than ASOS, in that it makes a higher operating profit margin, and is growing more rapidly in % terms.
I know the people behind this business, as in my days as FD of a ladieswear retailer, two of our major suppliers were Manchester-based "Pinstripe" and "Jogo" - they were good people to deal with, importers from India, who we found reliable and trustworthy. The stock they supplied was cheap & cheerful, and sold well. I'm talking 12-20 years ago now (scary thought!), but they have obviously spotted the potential to cut out the retailer altogether, and supply direct to the public.
The BooHoo website is good, and as with all online retailers, I've tested it out by ordering some goods, and everything worked as it should. The product was good for the price. The target market is probably the under-40s, especially lower down towards the teenage & student market.
It's a recent float, so you would imagine it was hideously over-priced, and indeed did look so at first glance. However, I think what the market has missed is that the international growth is kicking in nicely, and the business is already decently profitable. It's not actually particularly expensive on next year's forecasts. See the usual Stockopedia valuation graphic below, with my comments added:
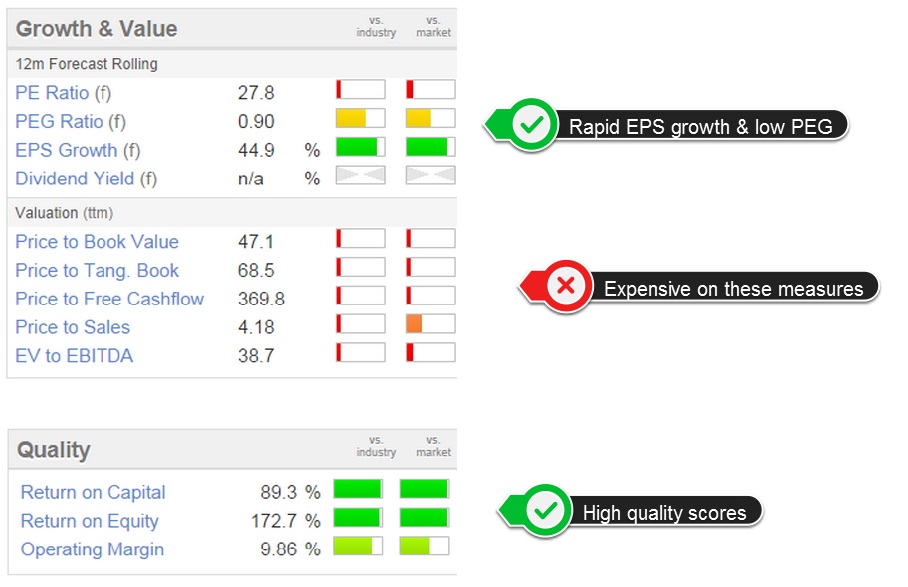
So it strikes me as a risky situation where the high (but not outrageous) forward PER is based on the company delivering very rapid growth. I got cold feet a few weeks ago, when the market wobbled, and I partially sold, but today have decided to buy back (at about the same price), since there is now the considerable benefit of an up-to-date trading statement.
Half year trading update - published today, this reads very well to me;
Revenue for the half year is approximately £67m, up 31% compared with the same period last year or 36% on a constant currency basis (CER). Revenue growth during the first half has continued to accelerate in line with management expectations with second quarter revenue growth of 37% or 41% CER up from 24% and 28% respectively in the first quarter. Improvement in growth was seen across all regions during Q2 with the UK up 50%, the Rest of Europe up 61% CER (50% reported) and the Rest of the World up 8% CER (0% reported).
The Company confirms that it continues to trade in line with expectations for the full year to 28 February 2015.
These are pretty impressive growth rates, and remember it's not some tiny start-up, they are forecast to do turnover of £157.5m this year, and make a £13.8m net profit (a profit margin of 8.8%, which is better than ASOS achieved last year at 5.3%, and ASOS is only forecast to make 3.4% this year).
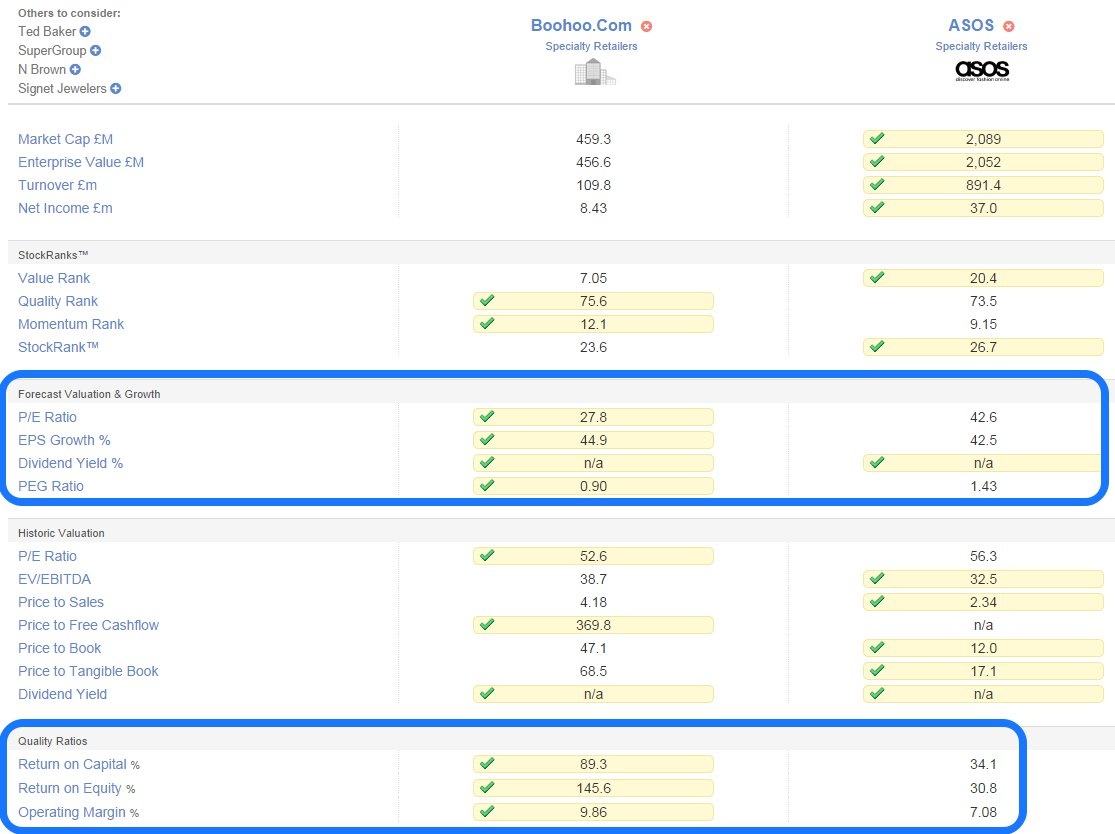
Valuation - ASOS is on a forward PER of 42.6, much higher than BooHoo at 27.8, yet I argue that BooHoo is a better growth story at this point in time. So there's a mispricing here in my view, potentially. Also bear in mind that during its rapid growth phase, ASOS went to a stratospheric rating, a PER of over 100, which was complete madness, but who knows the same lunatics could latch onto BooHoo and chase this up to a mad valuation too?
My opinion - It looks very interesting to me, especially with current news that it's trading in line with expectations.
Comparison Tool - Stockopedia has a nifty tool under the "Toolbox" menu above, called "Compare Stocks", which I find handy to compare key measures of two or more companies. I've run this tool for Asos & BooHoo, and the results confirm my view that BooHoo scores more highly on all the Quality measures, and is also cheaper on the key forecast Valuation measures (which I've ringed below);
The Stock Market Show
Ed has roped me into doing one of my spiels on the Stockopedia stand at this investor show tomorrow (13 Sep 2014) in Islington Design Centre. I'll be rambling on about small caps for an hour, and trying hard to sound intelligent! I really enjoy chatting to readers at events like this, so hopefully put some names to faces there tomorrow.
I'll have to sit down with a bottle of Aldi Chilean Merlot tonight, to plan what on earth I'm going to talk about tomorrow!
Motivcom (LON:MCM) - A recommended cash takeover bid has just been announced, priced at 148p. This company was on my watch list, after reading the Annual Report on a train, and thinking it looked quite good value, but not good enough to justify opening a position (as there have been some profit warnings).
The bid is only a 20.8% premium to the closing price last night, which is low for a takeover bid. If I were a shareholder, I'd want to know why the Directors have recommended this lowball bid? Surely there must be more than 20% upside on the shares from the company remaining independent?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
It seems like it's not just Naibu that look like they are up to sharp practices.
The attached article on Ultrasonic, listed in Germany perhaps sheds further light on the Chinese Shoe business..
http://www.bbc.co.uk/news/business-29227907
I wonder what the Mandarin is for Caveat Emptor?
"I am also a litigator hence my knowledge about shareholders' rights."
Always a useful person to know - would be nice to have some sort of real time legal recourse whereby company directors could be held to the transparency standards one would like to think something like Aim should aim for.
The problem is that most bods wouldn't begin to have a clue as to what we can expect from company officers.
Hopefully you will hang around and comment on other companies.
Also lets hope Paul never needs you services with his honestly held and forthright views. :)
thepiman3, probably the best place you could start is either by reading the Naibu admission document, or asking for a copy of the questions submitted to the board following the 2013 AGM.
You might also wish to investigate press comment relating to the company being financially restructured in 2008, and some brushes with the law and courts around the same time. None of these seemingly important (although vague) details are included in the admission document.
It's also very important to try to establish how these holders that magically appeared on the share register on incorporation in Jersey actually got there. Again, according to the admission document, they had absolutely no stake in the company previously, so why were they apparently gifted some of Mr Lin's shares at that time? According to the company and Daniel Stewart, they were "early stage backers", but that's categorically not the case according to the admission document.
If you're holding shares in this company, I guess either you haven't yet completed your research, or you may have a contrary view.
I'm sure I won't be the first to wonder, but I'll ask...
"Given you only registered today thepiman3, to ask these two questions"
http://www.stockopedia.com/contributors/thepiman3/
Are you
1) Working for Daniel Stewart
2) Working for Naibu
3) Working for a litigation Lawyer who's on the hunt for some business from one of the above two?
Otherwise why else would you REGISTER only today just to ask those pertinent questions. It's hardly likely you just HAPPENED Across this website, let alone the minute probability you stumbled across this specific thread when you happened upon this website!
What's your agenda?
Hi,
I registered because having read this article and subsequentposts, I wanted to find out more about this company. I do not work for Daniel Stewart or Naibu or their directors. I am a Naibu shareholder who has lost enough money to want to investigate this further. I am also a litigator hence my knowledge about shareholders' rights.
I have a question for Paul Scott and a comment to Mr Contrarian:
Question for Paul Scott:
I appreciate that in your article you just state your opinion and you are entitled to do that as that is your prerogative as a financial journalist/blogger but what is your evidence for the part of your opinion that states "I think the motivation for the previous dividends was probably an attempt to pump up the share price, to allow more insider share disposals at a much higher price. - See more at: http://www.stockopedia.com/content/small-cap-value-report-12-sep-2014-nbu-boo-mcm-86129/#sthash.IlCnQyKq.dpuf" That is quite an accusation. If it were true, the directors of NAIBU would be guilty of crimes such as market abuse contrary to section 118(6) of the Financial Services and Markets Act 2000. Of course, Chinese companies are extremely volatile and risky and relying on any unaudited accounts is always going to multiply that risk, but has anybody considered that whilst difficult to believe the problems Naibu is experiencing might be genuine? Yes, it's odd that they first stated that they built a factory but because they couldn't hire the staff the factory was empty and subsequently the directors decide to cut the dividend to pay for a new factory, but do we have all the info do be inferring market abuse yet? I don't think so. Isn't it possible that the empty factory is in a region of China where labour costs have risen prohibitively high and the planned new factory is somewhere else where it's cheaper to hire labour? China is a very big place after all. I remain an investor in Naibu and at the next AGM I will be asking these very questions. If the answers don't satisfy me, then I will consider whether there is a cause of action against the company's directors such as breach of fiduciary duty or market abuse and whether it's worth building a class action. Chinese companies are risky, but by being listed here their directors are liable to prosecution and, in some cases, to civil claims under the laws of England and Wales.
Comment to Mr Contrarian:
To the extent that your comment was meant as an inference that Daniel Stewart are not impartial, there may be some truth in that. Daniel Stewart holds a position in Naibu, either via some warrants or through some other mechanism see the notes on page 4 of Daniel Stewart's research note at http://www.shareprophets.advfn.com/file_download/286/NBUDS.pdf
Ref Naibu
Hello piman3
The facts with regard to main holders selling down their holding speak for themselves - other than the main bod guy they all now appear to be gone now - thats over 20 mill shares that been sold since joining Aim that could/will have netted them £15 million plus cash - now they have all sold up the dividend stops - seems that factually speaking whether it was deliberate ploy or not that - that is what has happened. Speculating as to whats going on behind the scenes seems fair game as long as its made clear that one is just speculating.
WIth regard to labour costs - this was only 21% of the direct costs anyway in relation to the cost of making a shoe - factor in the know projection rates for labour and similar and it seems bizarre that they could have got their sums so wrong that the whole factory is now useless.
The problem with any company like this is that in the event that there is anything wrong - the time proof is provided on a plate then you know where the shareprice will be at that time.
Thanks rmillaree, you may have a point there.
Looking at the figures again I think I can see where the error in the Naibu data figures has occurred.
Stockopedia is using the 2014 forecast (56p) from a report dated 08/05/14 and the 2015 forecast (46.2p) from a report dated 05/08/14.
For some reason Stockopedia had not updated the 2014 forecast to 46.1 pence which was also revised 05/08/14. This is an important downward revision which appears to have been missed? Obviously both reports have been lodged with Thompson Reuters so logically both figures should have been updated. I would think that some explanation from Thompson Reuters is justified.
Does this matter? – Probably not for Naibu but data accuracy is fairly essential. Obviously broker forecasts can be suspect but then if their data is misreported it introduces another layer of inaccuracy. I have some doubt that Naibu would have appeared in 13 positive Stockopedia screens had the downgrade been picked up.
Regarding the “Earnings Manipulation Risk” flag – this might be useful but it also picks up many decent companies. Kentz was probably the most impressive share I have owned in recent years – yet this was flagged up as a risk on at least one occasion.
Daniel Stewart have been taking their NBU F/C for a walk downhill for months:
8-5-14 53p
4-9-14 46p
Today UC but 0 div for 2014 & 15. Rec cut to Hold which, being the house broker, means Sell as the author Simon Willis knows full well.
It’s not only AIM traded Chinese companies that are mostly untrustworthy. Its’ the same situation on Canada’s Venture exchange which is the equivalent of AIM. The most recent example of maleficence is GreenStar Agricultural Corporation. The 2013 audited accounts which were due at the end of April were originally delayed because the auditors had “minor” concerns the company told the investment public. Turns out that minor concerns was that the agricultural property were no longer controlled by the company. No land, no business. Currently the story was the leases were seized and auctioned by a creditor but it’s obvious that this story will probably not hold up. The September 30, 2013 Interim Financial Statements showed Assets of $CND 57M of which the leases were valued at $CND 18M. The Balance Sheet showed Liabilities of $CND 7M of which $CND 2.9M were loans. Like Naibu Greenstar also paid a dividend for a couple of quarters almost yielding 10%.The PER ranged from 1 to 5. They were also profitable and unlike Naibu apparently generated significant Free Cash Flow as of the last Financial Statements it totaled about $CND 15M. No word where that went if it ever existed in the first place. So buyer beware on all Chinese small cap stocks and like you mentioned the accounts are most likely fiction.
Simon Thompson at IC 22.08.14--
It’s still my view that on fundamentals, and despite the downgrade, Naibu shares are woefully undervalued. They are also massively oversold from a technical perspective with the 14-day relative-strength indicator (RSI) on the floor, showing a reading sub-20. So although it will take a marked improvement in investor sentiment before the company is valued on a sensible basis, I am not bailing out and would advise taking advantage of the sell-off to average down the cost of your holdings."
It with Camkids was one of his Tips of the year and as a result I became less entusisiastic about his ideas. I will not buy into Chinese companies either. I think back to the hit Anthony Bolton took in China.
Earlier this year when Simon T published his bargain portfolio, I was gobsmacked to see included in it Naibu and Camkids. I must say that his standing in my eyes went down a notch or two.
Hi Golspie
I remember the article and thinking the same as you and have not renewed my sub. One of the many lessons I have learnt from Paul's column here is that not all accounts tell the truth and that Chinese Stocks just can not be trusted. It is a lesson that I think has probably saved me a lot of money.
Perhaps it's finger trouble, but I cannot find any trace of the ST article regarding Naibu on the IC site.
Sorry but typo--it was 12
08.14 and the third company mentioned in the comment. just put Naibu into the IC website Search.
Piledriver
Take a look at the ST Bargain 2014 portfolio...
Ref Naibu-
I was in,
now i am out,
I've been shaken all about……
if you must invest in these fantasy stocks, only do it in smalls…….
Hi Paul - From a valuation perspective, to compare BOO with ASOS is I think misleading as we know that ASOS were totally off the scale during the boom times and it is still off the scale at a PE of 40+ after taking a battering over the past few months. Maybe PEG is a better way to look at them. BOO's forward PEG is a healthy 0.59, whilst ASOS's is negative as the forward EPS growth is negative.
Hi Ramridge,
I don't think there's anything misleading at all about comparing two companies with identical activities, and many other similarities (ASOS & BooHoo). It's highly relevant. The share prices today are how the market rates each company, and my view is that BOO is much better value, even though ASOS shares have collapsed by 65%, they're still not cheap.
Paul.
P.S. I've run the Stockopedia comparison tool for Asos & BooHoo, and included it in the article above.
100% with you re Chinese companies on AIM.
As for Boohoo, where is the moat? So many companies churning out ladies clothing and selling on the net. Why, with your background and talents I'm sure you could join them tomorrow - well perhaps the day after. Just wait till Primark goes on line!
My feeling is that Boohoo will lead to tears... Sorry for that.
A question for Stockopedia re Naibu
Only one broker is listed and this apppears to be the house broker Daniel Stewart. So I guess it is reasonable to assume that the forecast for Naibu (see Broker Concensus Trend box on Naibu stocksheet) is that of Daniel Stewart.
The last broker note I can find from Daniel Stewart was dated 5th August 2014 and suggests a different eps for end 2014 and has a much different price target. Where then do the Stockopedia figures come from?
Very academic as far as Naibu is concerned, but I am intrigued as to how accurate the data is when a stock has perhaps only one broker and much of the Stockpoedia forecast data is based on this brokers thoughts.
Our forecast data comes from Thomson Reuters and the one data point is from Daniel Stewart indeed.
We can only publish what we can source. If Daniel Stewart aren't updating Thomson Reuters in a timely fashion then the market will be behind on their latest data and so will we - not much we can do about that I'm afraid.
The use of forecast data is a personal one. Many people don't rely on it especially amongst small caps with minimal broker coverage. In fact many studies by James Montier et al show that broker forecasts are notoriously unpredictive ! Some studies suggest that annual forecasts are on average wrong by up to 47% per year over a full business cycle.
Re. Naibu - Personally I give all stocks with a big 'Earnings Manipulation Risk' flag on the stock report a wide berth, unless it's only due to high sales growth.
I think my point is that it looks like very different data - not just old data that has not been updated. In fact I cant really see how this is old data at all.
Is there any way that it is possible to confirm that the Thompson feed is Daniel Stewart?
"Some studies suggest that annual forecasts are on average wrong by up to 47% per year over a full business cycle."
Yes - most broker research is poor - but I would be wary of going down that particular route as people might read this as the Stockopedia stocksheets can be wrong by up to 47%.
Hi Ed
Good point but two questions and sorry to piggy back on Paul's column
One of the best performing screens on Stockopedia is the Kenneth Fisher Price to Sales Screen, which contains Naibu Global International Co (LON:NBU), Spaceandpeople (LON:SAL) and Farmstandart OAO (LON:PHST). The first two have been disasters and whether that indicates the fate awaiting Farmstandart OAO (LON:PHST) I don't know:
1. Could I have forked this (KFPtS) screen or any screen and excluded all stocks with an "'Earnings Manipulation Risk Flag"
2. Could I have forked this screen or any screen and excluded all stocks where the management/head office are not in the UK or Europe or USA?
Thanks
Michael
.
Paul wrote a piece some time ago about QPP, which I dismissed at the time, however am now converted as Paul gives facts and figures - have been watching BOO for a while but it is a very volatile stock - RNS's being sold into probably because of ignorance by small PIs. Paul has a background in retail so knows his onions (or dresses !) - happy to subscribe here.
Hi Paul
I've found your comments about a range of "too good to be true" companies very interesting - and written in a style designed to make people question the story/numbers by applying common sense rather than lecturing them on their folly. It's a shame (for them) if they didn't listen and shameful that you have had to endure the abuse we've witnessed along the way - but so useful for the more balanced reader.
Of course, not all your concerns and worries turn out as expressed - but that's natural, especially given the (very much appreciated) "this is my current thought process" style in which you write.
Carry on the good work! And I hope to buy you a pint in Derby.....
Andy