Small Cap Value Report (21 Jan 2015) - UBI, IGP, SCH, ACT

Good morning!
Ubisense (LON:UBI)
Share price: 117.5p (down 2.5p today)
No. shares: 25.1m
Market Cap: £29.5m
Trading update - this sounds a bit mixed - turnover below expectations, but higher margins offset that, to deliver adjusted EBITDA (yuk!) in line with expectations for calendar 2014.
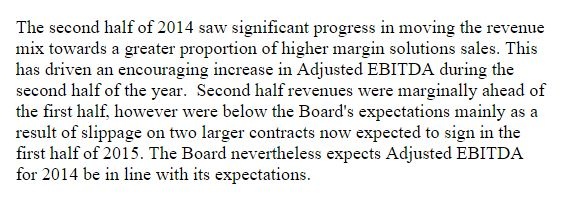
Mention is made of some restructuring costs (£0.7m - to be reported as exceptional) and goodwill write-off of £1.2m (fine, as it's non-cash).
Net debt - reported as £3.2m at y/e, down from net cash of £0.75m at the half way point. This is explained as being due to unusually high debtors (up by £4.5m), which is expected to reverse in Q1.
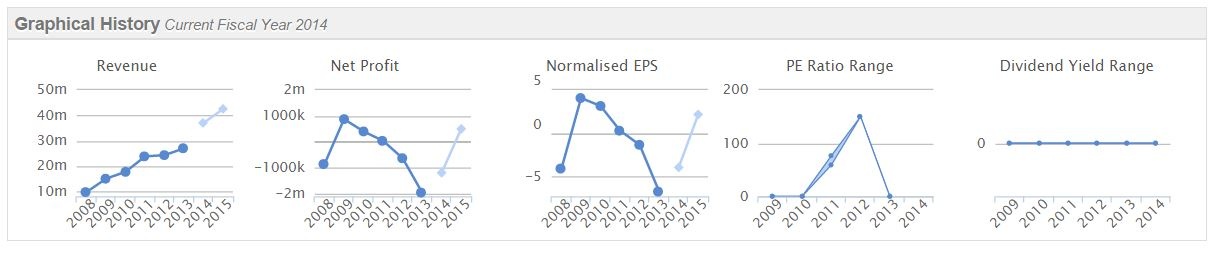
My opinion - a year end spike in debtors is a big red flag - so that would need careful scrutiny. It's good to see margins improving. This company has delivered decent turnover growth (see graphs below), but not gained any traction on profitability, in fact it's gone backwards after making small profits in from 2009-2011, to being loss-making again. That makes me question whether they have a viable business model?
Whilst the product sounds good, there must be plenty of other companies doing a similar thing (tracking movement of parts in factories, etc), and the bottom line is that if you can't make a sustainable profit, then something is wrong - maybe lack of scale, and/or lack of pricing power? I'm also not keen on loss-making companies having debt - as it makes a dilutive Placing much more likely if the bank decide they are not comfortable.
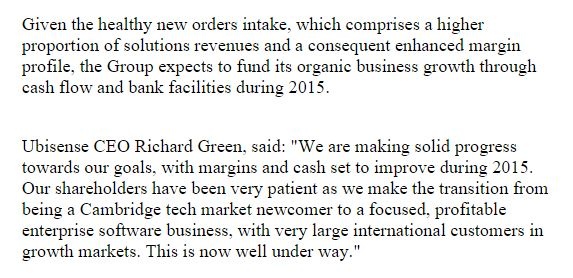
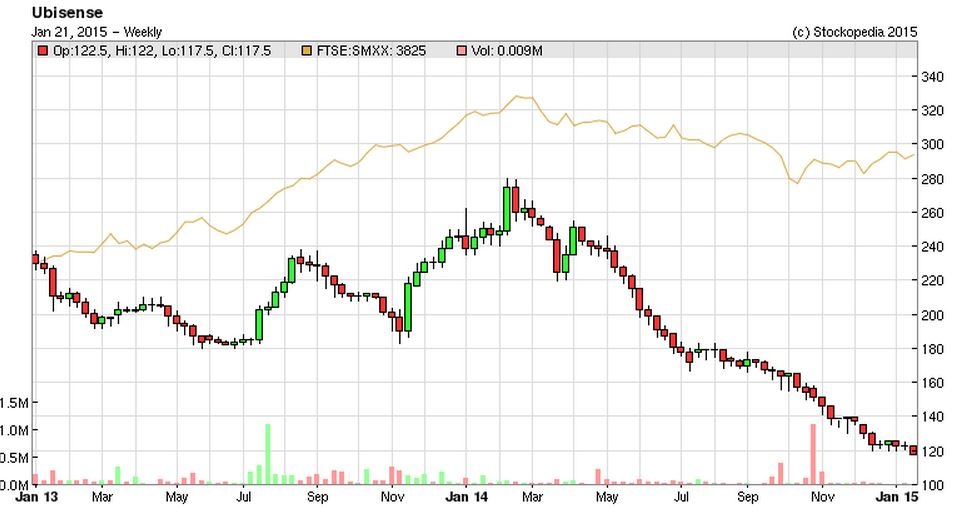
As I mentioned in my report on 16 Jun 2014 (when the shares were 192p), I'd be looking for a sub-100p entry price. It's almost got there now, but I can't say this share strikes me as a bargain even now. There's not really enough red meat in this outlook statement today, although the "healthy new orders intake" mentioned in the first line below is positive. Overall, I remain agnostic on this share.
Intercede (LON:IGP)
Share price: 114p (down 20p today)
No. shares: 48.4m
Market Cap: £55.2m
Trading update - it's a profit warning. Yet another situation where a company had a disappointing H1, but said it hoped to make up the shortfall in H2, but then fails to do so. The year end is 31 Mar 2015. The company says;

The company only did £9.8m turnover last year, and made a small profit of £0.8m. So as 2014/15 is showing no growth, how on earth does a £55.2m market cap make sense? It looks way, way too high to me.
A £1m loss is forecast for the year, but it does have £5m in cash, so no issue over solvency.
My opinion - the outlook statement talks up the future potential, but on the basis of figures achieved so far, I'd say a price of about 30p per share would look more reasonable than the current 114p. Therefore a market cap that looks about a quarter reality, and three quarters hope for future growth, strikes me as something I would rather avoid.
SafeCharge International (LON:SCH)
Trading update - not a company I've looked at before. It seems to be another payment processing company. An update today sounds good;
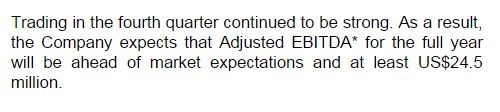
I haven't got time to crunch the figures today, as I've got meetings in London this afternoon, and am still in Hove! However, am just flagging it up to readers, as it's always worth checking the numbers for a company that reports being ahead of market expectations, as you can sometimes find the odd overlooked gem that way.
Actual Experience (LON:ACT)
This company has a very interesting story, but the figures today show hardly any commercial progress at all - turnover for the year ended 30 Sep 2014 is only up a little to £567k! The loss before tax & before exceptionals (such as AIM IPO costs) was £1.1m.
The market cap is £52.9m, so it's all about future hope, rather than current performance.
The narrative is too vague, and reads to me like a list of buzzwords & phrases, with very little specific. That said, I've been told the company has exciting technology. I'll look closer when the figures are exciting too, which they are not at this stage.
Gotta dash, see you tomorrow morning.
Regards, Paul.
(of the companies mentioned today, Paul has no long or short positions. A fund management company with which Paul is associated may hold positions in companies mentioned)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
re. SafeCharge International (LON:SCH). I have often read Paul and other analysts mention that EBITDA is pretty much useless. For those who doubt this, here is a case in point.
FY2013 accounts show an adj. EBITDA = $11.3m and a net loss for the year = -£1.3m.
HY2014 accounts show an adj. EBITDA = $10.8m and a net profit = $4.8m
So with two EBITDA s pretty close to each other, the bottom line can be vastly different.
Why? because there are a number of big moving parts such as goodwill charges, share-based payments, IPO costs, etc.
So when we have today's trading update which simply says the full year adj. EBITDA is forecast to be $24.5m and is ahead of expectations, it means nothing.
Hi Ram,
Wonder if I could pick your brains on this one I sold out recently as a small loss noticed after buying the low free float with north of 60% of stock being held by one company which from memory is linked to the owner was possibly a red flag in hindsight.
The impression I get is your a fairly successful investor i'm guessing you trade full time also can I ask any other red flags you use Stocko for when castings your eye over a company for the first time.
Cheers Andy
Hi Paul, I know it is annoying when you cover 500 stocks, and people keep asking you about the ones you don't cover, but I'm going to do it anyway. On 21st Jan 2014 (exactly a year ago) you did write some initial comments on IQE, which yesterday announced what looks like an extremely strong trading statement. Debt is falling, earnings are rising (+20%), and ahead of market expectations (2.4p vs 2.2p). The stock trades on less than 10x historic 2014 earnings and the company states:
'As a result, we expect continued growth in demand for our wireless products complemented by more rapid growth in our photonics related businesses. This dynamic should be further enhanced by the deployment of high capacity optical data transmission systems and storage (datacentres), as the growth in data continues to grow exponentially. Further growth in our business will be supported by the future market development of our advanced solar and power switching business units.'... 'Furthermore, just after the period end, we secured a major contract renewal with an important tier 1 customer estimated to be worth over US$50m, and which will also lead to some expansion of our market share - a significant highlight to the start of 2015. The outlook for this business unit remains robust, driven by increasing adoption of 4G and LTE globally.'.
I am a very small holder, but this piqued my interest, as the stock looks to be well positioned in the sweet spot of a growth market, yet completely ignored by the market. To be fair, they made a major acquisition in 2013, and bedding such a purchase down always takes longer and costs more than expected, so it is not surprising the positives are coming through only now. Your thoughts much appreciated.
Sorry, not enough time to look at Alkane Energy.
PetsAtHome is large cap, so not something I would look at.
Regards, Paul.
Thanks Paul. Numbers look good but be aware Safecharge is "regulated as a payment institution by the central bank of cyprus (CBC)". I'm not familiar with it either, but payments tends to be a business where scale is important (ie PayPal, Visa, Mastercard) because there are network effects. This is definitely a DYOR one!
One to file away in my investing rules of thumb notebook: "Therefore a market cap that looks about a quarter reality, and three quarters hope for future growth, strikes me as something I would rather avoid."
Paul.
Could you please also comment on this mornings Alkane Energy trading update?
Since Paul is busy - Alkane's share price is falling due to the Micawber factor - net debt keeps rising.The company keeps coming up with reasons,explanations,excuses - but there you have it.There is supposed to be an operating profit,so if capex really is capex,the company needs to start living within its means.
Disclosure,long -but not happy.
In fairness Alan, the increase in debt was expected due to the 5 year £5.5 m Lloyds loan for the Carron and Dragon aquisitions. What seems to be disappointing is the drop in STOR. The delayed commissioning of Wheldale and Shirebrook won't be repeated but the STOR might be. There is little to prevent new facilities coming online in competition.
Also long...also unhappy!!
Paul,
Please could you comment on this morning's Pets at Home (LON:PETS) trading update?