Small Cap Value Report (21 Sep 2016) - SWP, WINE, EGS, DX., DSG

Good morning!
It's worth noting that sterling is weakening again, which has a knock on impact on shares, as we've discussed here before. So those dollar earning companies, and UK exporters, are becoming increasingly attractive again.
As an example of that, Judges Scientific (LON:JDG) pointed out yesterday that as mainly a UK exporter, it is enjoying the most favourable exchange rates since 2009. This was one of the companies that I wrote about in a late update last night. The other one was Fastjet (LON:FJET) - a complete crock.
Here is the link to yesterday's complete report, to get you started whilst I crack on with writing up some new stuff about companies reporting today.
Profit warnings
As the day goes on, I will report below in more detail on 3 companies which have all put out profit warnings this morning, and are all hitting fresh 52-weeks lows, namely;
Majestic Wine (LON:WINE) - under-performance in commercial, and Naked Wines USA. Warning doesn't look too bad though. Am awaiting updated broker forecasts.
Bonmarche Holdings (LON:BON) - as I predicted here on 28 Jul 2016, another profit warning looked "a virtual certainty". I don't see any rush to buy the shares this morning, as profit expectations are way down, and the company is clearly under-performing. Guess what? It blames the weather!
Cenkos Securities (LON:CNKS) - not a sector I usually cover, but the deep plunge in H1 profit today illustrates the feast or famine cyclicality of this sector.
SWP (LON:SWP)
Recommended cash offer - the company's own Directors have made a cash bid for SWP, at 9p per share. This looks a fair price to me, being a 50% premium to yesterday's closing price of 6p.
Well done to all holders. The usual form now is for everyone to start bellyaching that the company is worth far more, etc. Then people quietly accept the deal, bank the profit & move on.
It's almost a done deal, with 57.2% already in the bag.
Majestic Wine (LON:WINE)
Share price: 325p (down 25.0% today)
No. shares: 70.8m
Market cap: £230.1m
Trading update (profit warning) - the key sentence is this;
EBIT for the current financial year ending 3 April 2017 is expected to fall below current market expectations1.
The "1" footnote is important, and very helpfully gives a figure for what market expectations currently are;
1 The board believe current consensus PBT for the year ending April 3 2017 to be £16.1m
All companies need to do this - i.e. if an RNS mentions market (or Directors') expectations, then it should always state in a footnote what that figure actually is. I think it should also state the forecast EPS figure too. This clarity greatly helps investors interpret statements correctly, and is to be applauded.
Good bits - 3 divisions within the group are trading well;
Majestic Retail trading on track and making good progress on the transformation plan
Naked Wines UK and Australia are performing well and on plan
A return to growth for Lay & Wheeler
Bad bits - 2 divisions are not trading well;
Commercial division
- Trading has deteriorated.
- H1 has seen no sales growth, and a 200bps drop in gross margin.
- If these trends persist in H2, then operating profit (EBIT) could be around £2m lower than expectations.
- Internal review underway to improve performance.
Naked Wines USA
- Increased marketing initiatives have impacted profitability.
- Direct mail campaign has not worked.
- Small loss for the full year (versus an "unscheduled" profit last year)
- Operating profit performance also c.£2m lower than expectations.
Put that together, and it's about a £4m shortfall in operating profit, versus a £16.1m market forecast, so about a 25% shortfall from expected profitability. Not great. The share price has exactly mirrored this, at the time of writing, with a 25% fall today.
My opinion - I'm not sure about this share. It had a honeymoon period after the new CEO joined, and bolted on an apparently exciting growth business - Naked Wines.
The glass may now be turning half empty, with the reality dawning that this is really a low margin retailer. £12m operating profit for this year, on turnover of c.£440m is not good. Sure, the hope is that Naked Wines could become a blockbuster business within the group. I think the jury is out on that, personally I'm not convinced. I signed up for its service online, only to find that the wines I liked were unavailable.
Naked Wine's marketing is undoubtedly very clever, and draws you in, but in the end I'd rather just pop down to Waitrose and buy something nice from there, if I have guests coming round for dinner. Aldi plonk will do for the rest of the time. So maybe I'm not the target customer here?!
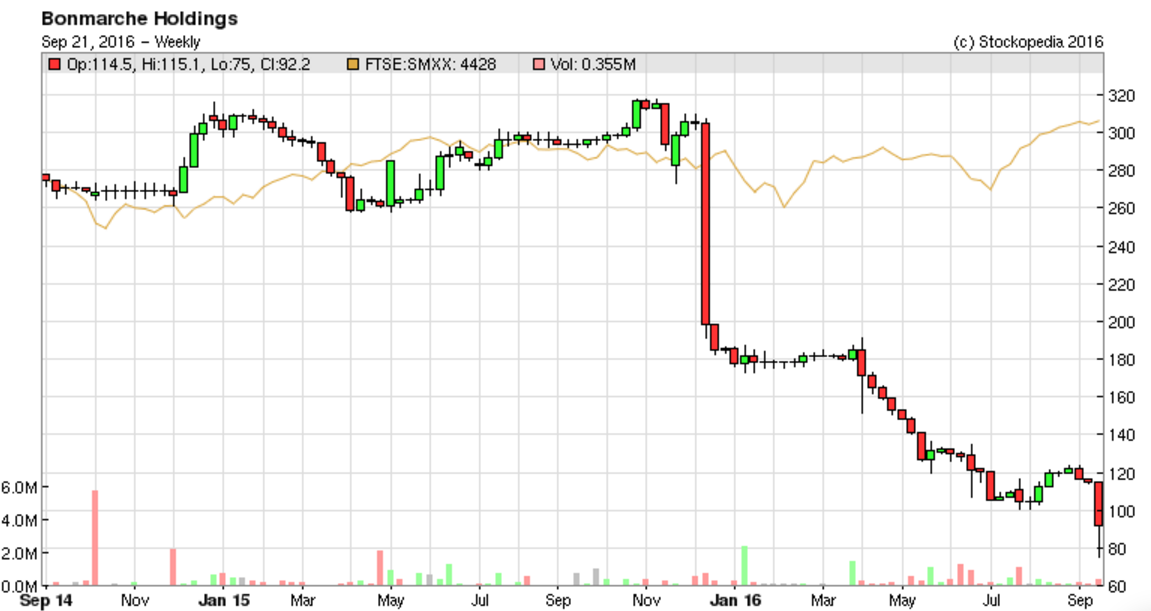
Looking at the chart, 300p has twice formed strong support, in early 2015, and 2016, so maybe it will do again? Therefore if you like the company, this could be a buying opportunity. Personally I don't particularly like the company, so will pass on this one, and don't have a strong view either way really.
Today's warning doesn't look too bad, with the core business doing alright. Also, the intention to resume divis is reiterated in the Directorspeak section.
I should also commend the company on a very well thought-out statement today. I found it comprehensive, easy to follow, and explained fully all the issues, and most importantly actually quantified their impact. If only all trading updates were this well constructed.
Bonmarche Holdings (LON:BON)
Share price: 90.5p (down 21.3% today)
No. shares: 50.0m
Market cap: £45.3m
Trading update (profit warning) - readers here were well prepared for this profit warning, as I predicted it very specifically in my report here on 28 Jul 2016. It seemed obvious to me that the company couldn't possibly hit its full year forecast whilst LFL sales were down 8.1% in Q1.
Another canary in the mine was Stockopedia's terrific little graph on the 12 month trend in broker consensus EPS forecast;
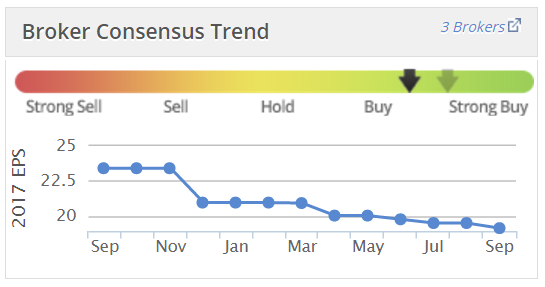
This graph is so useful, as repeated moves downwards is telling us that things probably are not going well. Research analysts at brokers don't operate in a vacuum - they talk to the FD at the company concerned, who will often give them a steer.
Mind you, broker forecasts are often still wildly wrong, which they're bound to be - nobody can predict the future with any great certainty.
This is an important general point to make actually. It's important to crunch some figures yourself, and check whether broker forecasts make sense. Surprisingly often with small caps, they don't. As in this case, back in July the company reported awful trading in Q1, but insisted it could still meet full year figures. That looked ridiculous to me. What the company said, and what brokers forecast, just didn't pass a simple common sense test. That's why I didn't buy any BON in the last few months, as another profit warning was very likely, hence today's price drop was a bullet that could & should have been dodged.
Profit warning - anyway, this is what the company says today;
Notwithstanding difficult trading conditions in July and August, overall performance was in line with management's expectations for the full year. However, trading in September has been extremely poor, largely as a consequence of the unseasonably hot weather which has not favoured sales of our new autumn ranges.
The hot weather conditions have resulted in the strong sales of residual summer stock however, and this will result in an end of season summer stock holding which is below last year's level, despite the generally poor summer season.
Nonetheless, we currently estimate that the store like-for-like ("LFL") sales result for Q2 will be approximately -8.0%, and the LFL for the first half-year will also be approximately -8.0%.
Now, let me compose myself before I explode. Deep breath. It is true that a warm September will indeed curtail sales of autumn ranges. That is, if you pack your stores with woollens, overcoats & hats/gloves, then of course they won't sell when people are on the beach in a heatwave. That's why sensible retailers bring in transitional ranges in July/August - i.e. new styles that will sell regardless of weather conditions, if the design/fabric/price, etc are all good.
Good retailers also find that unfavourable weather causes temporary downturn in sales, which they will usually recoup as the season goes on. In my experience, retailers that continuously blame the weather throughout the year are not seeing the wood for the trees. The underlying problem is that their product offering isn't good enough. The weather just makes that worse.
To deliver LFL sales of -8.0% for the whole of H1, then Bonmarche clearly has problems. What is frustrating is that management don't seem to be recognising that, and have instead looked for excuses, such as weather. Weather happens every year, it's always unpredictable, this is Britain. Good retailers navigate through that.
Revised forecast - well done to the company for giving us a revised profit forecast today. Companies can, and should publish guidance to the market. Brokers/NOMADs who say it's not allowed are just lying, and should be sacked, in my view. Lots of companies both on the main market, and on AIM, do publish current year forecasts. Everyone should do it - because managing investor expectations is a key part of being a listed company.
Here we go;
Combining the effect of September's trading with a more cautious forecast for the second half of the year, the Board's view is that the Company's full year profit before tax is likely to fall within a range between £5.0m and £7.0m.
Balance sheet - there's no problem with solvency, as the company remains profitable, and has a decent balance sheet with cash on it;
The Company's financial position remains strong and the Company is expected to end the half year with a net cash balance of approximately £9m. In addition, the Company is supported by a £10.0m revolving credit facility, which is currently undrawn.
Dividends - look enticing in the short term, but remember that this level of payout may not be sustainable, if trading deteriorates further;
Notwithstanding the difficult trading conditions set out above, the board proposes to announce an interim dividend of 2.5 pence per share, a similar level to that paid in respect of the first half of FY16, and currently expects to announce a final dividend of 4.6 pence per share.
Directorspeak - the new CEO does seem to acknowledge that action is needed to improve execution. Retail is detail;
"I was attracted to Bonmarché by its potential to grow as a business serving the 50 plus women's value clothing market. My early impressions of the business have underpinned this, and I am currently formulating my plans for the future.
The direction of travel is right, but the effectiveness of execution needs to improve. My plans are therefore likely to focus on improving the clarity of the customer proposition and operational improvements in all channels rather than a major strategic repositioning.
That's good. She's on the case by the sound of it.
My opinion - I'm very wary of getting involved with any struggling conventional retailers. They're up against big headwinds right now, and the one who are struggling now could end up in dire straits once these headwinds have taken their toll, specifically;
- Continued increases in Living Wage
- Pension contributions
- Apprenticeship levy
- Weaker sterling - large cost price rises in the pipeline for next year
- Upward-only rent review system, and increasing business rates
- Highly competitive sector, with new online competitors emerging & growing fast
A business experiencing all these headwinds, and seeing sales decline by 8%, could get into real trouble.
Therefore, I see this share as a potential value trap. Sure it looks cheap now, but it won't look cheap if current trends continue. Another drop in sales could easily see this move into losses next year.
The new CEO may be able to turn it around, but I reckon it's safest to steer clear of this, and other struggling retailers. I reckon it's better to spot overlooked growth stocks, and pay a bit more for them, rather than trying to find low PER bargains - which are often struggling companies that are being overtaken by online competitors.
A few quickies to finish off with;
eg Solutions (LON:EGS)
Interim results for the 6 months to 31 Jul 2016 are out today, and they're pretty awful;
- Turnover fell 31% to just £2.5m.
- Pre-tax losses ballooned from -£0.26m in H1 2015, to -£1.33m in H1 2016.
- Net cash almost halved from a year earlier, to £1.66m
The company, and FinnCap trumpet good contract wins in H1, which FinnCap reckons will lead to an "exceptional" H2. Sounds interesting, but it's more jam tomorrow from a company that has been a serial disappointer in the past.
Given its track record, I'm certainly not minded to give this company the benefit of the doubt. It very much appears to be a lifestyle company for the CEO, in my view. I'm basing that view on fact - i.e. comparing the cumulative amount raised from investors, compared with the cumulative amount withdrawn in remuneration by management.
DX (Group) (LON:DX.)
Preliminary results for the y/e 30 Jun 2016 are out today. They're not as bad as feared;
- Revenue down 3.2% to £287.9m
- Adjusted profit before tax of £11.5m (down 57% on prior year)
- Adjusted EPS of 4.9p
- Net debt of £9.8m
Given the share price is only 20p (down 9.1% today), surely this is a bargain at a market cap of only £40m? That's a PER of just over 4 - screaming bargain? I'm afraid not.
The problem is that the big profit generator is the DX Exchange business. This is in terminal decline, as solicitors & others substitute emails for documents. As the company explains today;
As we previously reported, the Group's profitability has been substantially impacted by three major factors. The most significant of these was an increase, above that expected, in volume erosion at the DX Exchange operation, our bespoke secure document handling service. As we have highlighted previously, this business is subject to e-substitution and has a largely fixed cost base...
... Renewals in the second half, which includes April, an important renewal month in the governmental sector, were in line with management expectations.
Revenue for the year from DX Exchange showed a decline of 10.1% compared to 5.4% in 2015. This decline significantly impacted profitability since the service has a mainly fixed cost base; deliveries and collections are made to all 4,500 document exchanges around the UK and Ireland every morning and every evening, largely irrespective of the volume of mail or the number of customers.
Volume erosion is expected to continue, with digitisation and electronic communications driving this trend, but DX Exchange remains a valuable service to its customers and we will seek to support renewal levels with high levels of customer service.
These comments should send a shiver down the spine of all shareholders. It's the worst possible scenario to be in - a fixed cost business with thousands of locations, combined with revenues which are declining at an accelerating rate.
My opinion - I think this company is the living dead. The dynamics described above seem to be pointing towards inevitable decline and eventual insolvency. It's likely to take several years, but I think this group is probably heading for extinction. Unless management can come up with a clever way of restructuring the core business to make it viable on dwindling revenues?
The rest of the business is operating in a cut-throat sector, where there's really not much profit to be made, as customers constantly shop around for the lowest prices.
So this one's a bargepole job for me. Although note that management did make substantial buys at 17p in Mar 2016, totalling £0.75m.
A divi of 1.5p per share is being paid, but it wouldn't surprise me if this is the last significant divi the company ever pays.
Dillistone (LON:DSG)
A couple of readers were discussing today's interim results from this software company, in the comments section below. I've had a quick look at the numbers, and the figures look alright. H1 2016 turnover & profit are little changed from last year.
There's an attractive divi yield here, but looking at the balance sheet, I'm concerned that the current high divi payouts might be unsustainable.
NAV of £7.1m becomes negative NTAV of -£2.4m. Generally I like to see generous divis only coming from companies with strong balance sheets. This one isn't strong.
Also, note that the current ratio of 0.57 is very poor - indicating a stretched working capital position. This could be because customers are paying up-front, so if that is spread evenly across the year, then it may not be such a problem.
The cashflow statement shows that the company uses up nearly all of its cashflow in paying the divis, and funding development spending.
Outlook comments are reassuring, and remind us that the business is mainly generating SaaS (i.e. recurring) revenues. This is an important point, as it means that revenues (and hence profits) should be much smoother & more predictable than other software companies which rely more heavily on licence sales.
Note 4 indicates that about two thirds of revenues are recurring. The Directorspeak section points out that recurring revenues cover admin costs. So the business should remain profitable, even in a bad year.
My opinion - given its strong recurring revenues, maybe my balance sheet concerns are unfounded. This strikes me as quite a nice, steady little business. It's probably priced about right for now. What is lacking, is convincing upside potential. If the company can start demonstrating some really strong growth, then I would jump in and buy some, for a re-rating. Trouble is, based on today's results & outlook, that prospect seems remote.
So the danger is that a purchase here would just be dead money, which comes at an opportunity cost of course. Sure the divis are nice, but you need the first year's just to cover the bid/offer spread. It's tricky to buy & sell in any volume too.
Overall then, it's not for me, but is on my watch list, as company I like, which I would consider buying in future if some exciting growth started to emerge.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

43 comments
Re DX.
Chickens have come home to roost here this morning.
You have saved me a whole load of grief Paul, because having read your ' living dead' piece as above I promptly sold out my holding.
Don't always agree with your views but with DX. & SIV [also timely sold out] you have been spot on.
Thanks & keep up the good work.
Not invesment related but I'd like to mention that we use the DX where I work and apart from their ropey online tracking (or our out of date IT) they have customer service that puts the Royal Mail to shame. People respond quickly to emails or phone calls and genuinely seem to want to help. The pricing is good and they are our number one choice for handling confidential files that we wouldn't trust to RM - which may explain why they are struggling to get enough suitably qualified drivers. Something I was told many years ago was that the government supports them as they never go on strike, the civil service would have major problems if the mail was backing up in post rooms around the country.
Hi Paul,
I'm a long time lurker and avid reader of your reports, many thanks for write ups, I find them valuable.
Anecdotally regarding £DX, they were the 3rd party delivery company delivering flowers for me yesterday and made a right dogs breakfast of it.
The delivery was due to be made to an office address and when I checked tracking for an update in the afternoon, I discovered that they left a calling card as they 'couldn't deliver the package'. There was no further explanation, no call to me or the recipient. I then spent 20 minutes on hold waiting for customer service who, when I finally got through, investigated for me. I was baffled that they weren't able to deliver to an office where reception is open all day. It turns out the delivery driver simply didn't bother delivering the flowers!
I was pretty shocked with the useless tracking (lack of detail) and general customer service.
Thought I would share as you like hearing about personal experiences with the firms you write about. "This company is the living dead" - In a cut throat market like this, I agree!
Best
Pete
One interesting outcome I have for DX (Group) (LON:DX.) is a purchase by a strategic buyer. Not another logistics company, but by one of the big online retailers in the UK.
Why? One of Amazon's key competitiveness is their own delivery network, which they are growing aggressively. To offer same day delivery, and decrease costs. One of the other big retailers trying to compete could acquire DX's network and infrastructure, saving themselves a lot of pain trying to create one from scratch.
Hi Paul,
Great report as always. As a holder of both Bonmarche Holdings (LON:BON) and Cenkos Securities (LON:CNKS) I've had better days.
Of the 2 profit warnings Cenkos is far worse that Bonmarche in my opinion. Cenkos has regularly updated the market over the last 12 months saying everything is fine. They don't seem to see that the monumental drop in revenue and profit is anything but fine. They dismiss the number of companies they have lost as acting nomad as insignificant, and they issue statements stating that current trading is good. In the same fashion to the last 6+ months whilst they have been secretly having a disaster. There really should be some clear cut rules on issuing profit warnings when it is clear that trading is not going well. Today's RNS has absolutely no humility or even recognition that they have performed appallingly badly. Totally shocking behaviour and from a company that advises PLCs on their obligations! sold out 100% on that one.
Bonmarche Holdings (LON:BON) is a slightly different one for me. I have held all of the shares in this one as I think the drop today was massively overdone. The price should have already priced in this second profit warning as it was as near to a certainty as you can get. I agree that the constant banging on about the weather is a mistake but it must seem like an easy excuse and the new CEO is probably listening to the old hands advising her. The reasons to hold: I think demographics will favour them, and protect them from internet erosion (unlike the youth market). The balance sheet is very strong. They have put out a clear statement, they have a new CEO who i think after a good bit of kitchen sinking will be a good match to the business (coming from George at ASDA) and they clearly acknowledge that things are not good and need to change.
Hopefully tomorrow will be a better day.
Hi Guys and Girls,
This is relevant to the discussion thread on positions in BON but it is a note to my self that I can refer to when fear levels are high.
'Capitulation' investment or maybe trading works!
All of the stocks referred to here have been discussed by Paul after severe falls and all dismissed as risky with little investment merit.
Some I bought, some I sold, some I held, some I avoided. The prices I got and the dates of MY transactions are not necessarily the same as quoted here. The only people who get in at the bottom and out at the top are liars. I have just taken a quick look at my notes and data bases.
The purpose is to illustrate that 1) consensus leads to mediocre results 2) short term trading can be 'safer' than long term investment 3) institutional sales throw up bargains for nimble Private Investors 4) short covering is a powerful force to the upside.
BON
buy 25 May 121p sell 26 May 136p
buy 29 July 101p sell 30 Aug 124p
GAH (Gable insurance)
buy 12 Aug 2,13p sell 23 Aug 3,60p
AVN (Avanti)
buy 7 July 19p sell 13 July 33p
SGI (Stanley Gibbons)
buy 15 July 7,78p sell 1 Aug 16,19p
RUR (Rurelec)
buy 20 July 66p sell 1 Sep 1,50p
2015
buy 20 Oct 50p sell 14 Dec 1,35p
DX Group
buy 21 July 13,50p sell 17 Aug 18p
If you have followed the sequence to here then the disclaimers are: Percentages are not calculated for numerous reasons a) not the price achieved, b) not the high or low for the day, c) only relevant to position size and brokerage charges.
It is possible to see, however, that there are some 100% moves here.
DYOM = Develop Your Own Method
aflash, your post was certainly thought-provoking for me.
All of the stocks you listed I would classify as dog sh*t stocks - ones that I would never conceivably own for any period of time. I'm a definite buy-and-hold investor - mainly because at the moment (at least until the end of the month) I'm not in a position to take advantage of intra-day price movements.
So quality, buy and hold stocks are my preferred investment. However in the examples you listed, you made an excellent return in a short period.
So can I ask: what metrics did you use to decide to invest? What led you to buy and sell those stocks you listed (obviously subject to how much you would like to divulge on a public forum)?
Completely understand if you would prefer not to elaborate. But it just goes to show that every dog does indeed have its day. Indeed some of my most successful investments have been shares where I have previously lost a large % and bought back in at a later date.
Also (no offence to Paul here) but retail stocks are my least favourite shares and ones typically from which I run a mile. Just goes to show that sometimes straying out of your preferred investment area can yield results. And being open to new ideas can yield results.
metrics: too long to explain and anyway you do not appear to have the time to develop check lists like mine.
However your text is well written so here some pointers in the order I listed the stocks:
BON met value criteria on data bases
GAH the only 'punt' due to knowledge of the insurance sector
AVN has tangible assets- satellites
SGI has tangible assets - stamp collections
RUR has contracts in developing countries, sometimes has to enforce with litigation
DX see Stockopedia discussions
Instant overnight success is achieved after years and years of long days and nights of hard work!
Great post aflash.. are you Howard Marks in disguise?? Here's a quote from his latest memo that I'm sure you'll agree with:
“When everyone believes something is risky, their unwillingness to buy usually reduces its price to the point where it’s not risky at all. Broadly negative opinion can make it the least risky thing, since all optimism has been driven out of its price.”
Wise words indeed.
https://www.oaktreecapital.com/docs/default-source...
Paul; re Naked Wines;
When they sent me a mail shot I recall they had a simple questionnaire at the beginning of the blurb, asking if one was a 'Wine snob' ; a filter to identify those who were ok drinking un known label wine. The American market possibly also see this as dubious, as they have plenty of their own of high quality reasonable price with which they will be familiar. I too rely on Waitrose and take advantage of their major discount promotions; for these it is an advantage to get to know the Wine Dept manager who in time will advise when short time promotions are coming up....Cheers.
Interesting to see that Sun European Partners retain 52.4% of the shares in Bonmarche Holdings (LON:BON) so they are taking the biggest bath of anyone. Small beer for them but still somebdy will have some explaining to do and, with that holding, a support operation is perfectly possible.
I wouldn't be so sure that Sun will want them to cut the dividend either.
Paul did you give your view anywhere on the Fairpoint video conference or have I just missed it?
thanks
Cleeve
See yesterday's comments section
Paul
Have you looked at today's results from Dillistone (LON:DSG). May be too much of a lobster pot (illiquid) for you but solid results a small increase in the dividend (yield close to 5%), with recurring revenues increasing and sign of product momentum? Not one to trade but it seems a solid company.
I had a quick look at DSG - revenue and EBITDA only increased by 2%, eps only +1%. I suppose "New business orders in January - August already significantly ahead of the equivalent value for the whole of 2015" sounds promising, but with a turnover of less than 10m and pedestrian growth at present they are too speculative for me. Maybe I'm missing something....
Andrea341 - I don't think you missed anything - just a solid company which is not on an aggressive multiple (which to me is basically because of the illiquidity of the shares).. Balance sheet look robust with £1.4 million of net cash and company seems to be run for shareholders (directors salaries are modest and dividend policy is generous).
On a small point, the quote you make about "2016 Jan-Aug new business orders being already significantly above full-year 2015" refers just to the Dillistone Systems Division (half of the business). But still the other half of the business , Voyager Software Division, already has its Jan-Aug new orders above full-year 2015 (just not significantly above). Therefore, both sides of the business are receiving strong orders, reflecting product improvements (particularly FileFinder) and this should bode well for sales into 2017 etc.
Yes, Dillistone (LON:DSG) is a good solid little business, and they throw out most of their profits as dividends to investors. One point omitted is that they are consolidators in their field, making small acquisitions over the years that have all become profitable. Also the management team are excellent, being extremely shareholder focussed. I am a long-term holder, and happy with it. As you say, not one to trade but one to buy and sit on.
I see that Mike Love, the chairman of SCISYS (LON:SSY) is chairman here at Dillistone (LON:DSG). I'm long in SSY and have attended several investor lunches with the board - they all seem sensible and very unlikely to take risks, so I view Mike's role here as positive.
Companies that continually blame the weather are best avoided, it's just an excuse for underlying problems. Now Bonmarche Holdings (LON:BON) profits are forecast to be between £5-£7m, if we do get some bad weather then what? I think something needs to change, retailers who don't usually go out of business.
I'm not a holder, I did look at it a while ago as it looked good value but I was not convinced by the business and retail is one sector I have reduced my exposure, I think things will get worse.
Paul, I owe you a big thankyou. Yesterday (sheer luck) I went through an exercise of deliberately seeking "disconfirming evidence" for my favourite holdings. Bonmarche Holdings (LON:BON) was a high conviction value holding, and very overweight in the portfolio. I re-read your comments from last announcement, a light bulb went off, and I sold the lot! So thankyou.
Incidentally it was interesting that this only happened on second reading, really looking for bear points - when I first read at the time my "confirmation bias" completely dismissed it.
All the best
Graham
Awesome! Glad to have been of service :-)
P.
I sold out of BONMARCHE a few weeks ago taking the hint from Paul that a profit warning was on the cards and so it turned out .
PC
Majestic Wine misadventure in the U.S. reminisces of Tesco's Fresh and Easy.
Paul
Don't think I have seen any comment from you on Joules (LON:JOUL) since it's IPO and wondered if you have looked at it. Could be that I have missed it though I read regularly. As it's in the schmutter trade your view would be appreciated.
From the results on 7 September it looks like the roll-out will continue and is going well. Online and international similarly. SP at £2 could be considered fully valued but if the roll out is progressing well perhaps worth a little more?
Seems to be swimming against the tide experienced by Bonmarche and others.
£DX came out with mid-year results today, the decline continues, but at least it appears to be slowing. Personally I'd want to be getting this at an absolute bargain price to be interested.
Bonmarche, used to be a rubbish business, nothing changes
Majestic, the new CEO's old company really was offering some poor wines. While his move to allow single bottle wine sales was the "elephant in the room" the reality is that Majestic wines and their prices are moving closer to the Naked wine model than the trad great wines at great prices (special prices when you buy 2 my a@@e). Since the marketing (the stuff you need when you products are not up to is) is not great we are into terminal decline with this one.
They need some real thinking, what business are they in and how can they be great? AVOID
Re Cenkos and comment "feast or famine cyclicality of this sector": invariably when it is "feast" a disproportionate share of the profits then accrue to the employees via bonuses. Makes this sector totally uninvestable in my view
Heisenberg,
Re Cenkos and comment "feast or famine cyclicality of this sector": invariably when it is "feast" a disproportionate share of the profits then accrue to the employees via bonuses. Makes this sector totally uninvestable in my view
Yes I agree with you there about the sector generally. However, Cenkos Securities (LON:CNKS) is one of the very few shares in this sector that I do keep an eye on. The reason being that it has actually been extremely generous with dividends. Although some years have benefited from one-off bumper deals, like the AA IPO.
Also I think there are issues with Cenkos, including its involvement with Quindell.
Here is the Stockopedia dividends summary page (under the "Accounts" tab on Cenkos's StockReport);
Hi Paul,
There certainly are issues connected with Quindell. The FCA gave them a severe slap and a half million pound fine. I don't know all the story but reading around, the general opinion is their reputation has taken a big hit and they struggle to attract quality business now.
Any comment on Arrow Global ( Arrow Global (LON:ARW) )? Many thanks.
Hi Samscvb,
No, I don't cover Arrow Global (LON:ARW) because it's in one of the sectors that I rarely comment on - financials.
It's mainly due to the sheer volume of companies - I already cover 500-600 shares, so had to omit certain sectors, just to get the figure down to something vaguely manageable like that.
Sorry about that. Although by all means post something about the company, and why you like it. No reason why readers should be constrained by my particular choice of sectors.
Regards, Paul.
I bought Bonmarche a couple of weeks ago, because it came up in my screen of Value and Quality.
I am still trying to find my feet with investing and am unsure what to do in a situation like this. My gut reaction is to ditch it, but my rules are to wait until value or quality fall below a certain level and then sell.
I would ditch them, future does not look bright. One hard lesson to learn is ditch your losers early. Invest in companies that are doing well. High street retailers are under pressure but I believe that will get worse over the next 2 years. Gut reaction is a good instinct to follow, report other day said it was beneficial to investing.
Have you read Naked Trader's book, it's useful for new investors I found.
Trouble is herbie, the opportunity to 'ditch Bonmarche Holdings (LON:BON) early' has gone... the stock has fallen 70% since last December. There is a price for everything. Valuation is key.
There were plenty of investors selling Home Retail at 88p last December who probably now regret acting on gut instinct.
But he only bought a few weeks ago so it's still quite early. Home Retail was a different situation.
Of course some will recover but overall I think it's best to ditch losers and stick with winners.
You can always pick out different shares to make a point - look at BOO after they announced a profit warning. I also agree that there is a price for everything and valuation is key.
However, I would disagree that the opportunity to ditch has gone - a 70% fall doesnt mean that it will rise from here and indeed could easily fall another 70% over the next few months.
I would recommend to the original poster - take the hit on the chin, sell out, and survive for another day.
I agree, sell and move on. I got stuck with Woolworths back in the day and have put my expensive lesson to work and avoided high street retail ever since - it's in decline. The only growth is in internet and some out-of-town.
This investing game is difficult enough without trying to swim against the the tide.
plank
The most recent Bonmarche Holdings (LON:BON) accounts (March16) reveal a net tangible book value of £29m. This compares with today's market cap of £42m (@89p share price).
So whilst the company is valued at a premium of £13m to it's net tangible assets, this equates to just two years profits (based on the new guidance of '£5-7m pre-tax' for the current year).
I'd say the stock is close to being classified as 'Value'.
Could be a value trap, PJ007!
A Private Equity firm did the floatation of Bonmarche, and the retail investors are always falling into the same trap!
You will be better off with Boohoo because their fashion is up to date in this fast changing world!
Totally agree Orangetree, I'm not a shareholder of Bonmarche Holdings (LON:BON)
But any stock that has
is surely worth an appraisal!
Got to do my fundamental analysis to trade this stock.
Hi Plank, I would re enforce the advice to read The naked Traders Book. He recommends selling at a 10% loss regardless but run your winners. Easy to say but hard to be that disciplined. Another tip is on Stockopedia go to the chart button and put in 50 day, 150 day and 200 day moving averages so they always appear on the chart. You will notice that when the 50day ma dips below the share price line the share rises and when it crosses above it drops. This is a really useful signal. Good luck but cut your losers early. Charles