Small Cap Value Report (4 May 2016) - NXT, BHS, AVG

Good morning!
Next (LON:NXT)
Share price: 5070p (up 1.8% today)
No. shares: 150.1m
Market cap: £7,610.1m
(at the time of writing, I hold a long position in this share)
Q1 trading update - It's clearly not a small cap, I know. The Q1 update this morning seemed a bit soft, but what's interesting is that the share price quickly rebounded from an initial drop. I'll stick my neck out here, and suggest that we might have reached a low after big recent falls. Mind you, I thought that at 5600p too! Market timing is not really my thing.
I've waited a long time to be able to buy Next shares at a reasonable price.
Today's update says that the retail stores are suffering, with sales down 4.7%. However, Next Directory is doing well, with sales up 4.2%. That seems odd, and lends credence to the claims that some of the fall in High Street sales could be weather-related.
I remain of the view that it's just a very competitive market, with lots of online competition, giving people less of a reason to visit the High Street. I don't believe that there is any issue with overall consumer demand - spending habits are just shifting. More money seems to being spent on leisure - e.g. J D Wetherspoon (LON:JDW) reports LFL sales up 3.8% today.
With clothing so cheap now, you do reach a point where the wardrobe is just full to bursting point. Apparently women today have something like 4 times as many clothes as they did a few decades ago.
As always, the update from Next is a model of clarity, check this out:
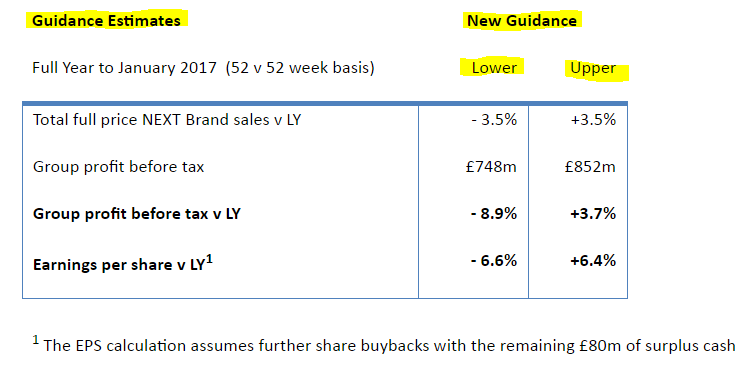
I have highlighted the word "guidance". So to all the companies who tell me, "We can't give guidance to the market" - my reply is, "Yes you can, and you should".
The upper & lower range, which is tweaked as the year progresses, is a wonderful way to manage investor expectations. Everyone should do this.
My opinion - this is a great quality business, making excellent margins. It's vastly better than say Marks and Spencer (LON:MKS) in almost every respect. Yet the price is now very reasonable, a fwd PER of c.11-12. That's a real bargain in my view. As always though, please DYOR.
BHS - Part 2
This is such an interesting, and topical subject, that I felt compelled to do more research on it last night.
In yesterday's report, I commented on my review of the published accounts for BHS back to 2006, saying correctly that it had paid no dividends at all over that period. A reader correctly pointed out that it had paid divis earlier.
So I decided to review all the published accounts for BHS Limited going back to 1999, up to the most recent, to 2014.
My notes are below. Sorry the formatting isn't great. I should have tabulated it, but didn't have time:
This is what BHS Ltd (the main operating co) paid in dividends:
1999-2001 - No divis paid.
y/e 30 Mar 2002
£124m divis paid. Profit before tax this year of £94.9m, so eating into reserves a bit to pay some of the divi.
2003
£70m divis paid, on £101.8m profit. So divis covered by profits made in the year.
2004
£220m in divis paid, which considerably exceeded profit of £101.9m
Balance sheet now looking stretched, but note that the main creditors are now other group companies - group companies are now owed £212m by BHS Ltd. So Green was effectively borrowing money from himself, to pay himself a big divi! Why?
2005
No divis paid. Profits for the year are retained, and group creditor on balance sheet reduces considerably.
2006
Business is now starting to struggle, with a big fall in profits, from £87.5m last year, to £31.0m this year.
No divis paid again.
Pension deficit shown on Bal Sheet for first time, at only £48.8m.
So note that the big dividends paid to date have not come at the expense of funding the pension scheme.
2007
£38.5m profit.
No dividends paid, again.
Bal sheet now looking more healthy, with £184.9m net assets.
Pension deficit has fallen to only £22.5m
2008
Profit of £21.5m
No divis paid again.
Balance sheet strengthened again. NAV now £226.2m
Pension deficit - n/a. Pension scheme now in SURPLUS of £2.2m
2009
Extended 74 week period.
Loss before tax of £65.6m
No divis paid.
Pension scheme goes back into deficit, of £99.3m
Balance sheet now looking stretched - NAV has fallen from £207m to £30m, due to trading losses & big fall in pension scheme.
2010
Loss before tax of £7.2m
Pension deficit rose to £118.1m.
NAV now only £2.5m
NB. See note 6 - management charges from Arcadia Group start - looks v high at £56.8m
2011
Unusual accounts - warrants a closer look.
Dividend INCOME for BHS Ltd of £56m, boosts profits. Where did this come from?
Going concern note - continued support of group holding company is confirmed.
Pre-exceptional operating loss of £43.7m
Large exceptional charge of £88.3m - being mainly a provision against onerous leases on stores which are now loss-making.
Pension deficit has reduced to £79.1m
Note £51.8m management charge from Arcadia Group (note 7)
Net assets just positive, at £330k
2012
Loss before tax of £71.4m, plus exceptional charge of £44.m - giving total loss of £116m
Balance sheet now negative, at -£80.3m net assets
Pension scheme deficit is £73.1m
Arcadia mgt charge £50.9m
Note that BHS Ltd now owes other group companies £147m (within creditors, see note 15)
2013
Loss for the year of £69.6m
Balance sheet now very weak - NAV is negative at -£178.2m
Pension deficit risen to £109.3m
Arcadia group mgt charge - seems odd that it is identical to last year's charge, at £50.901m
(this may be a typo, as it is changed to £42.36m in the following year's accounts, prior year comparative)
Group companies creditor has risen further to £176.2m
2014
£85.1m loss, which includes more provisions of £21.7m
Bal sheet now a car crash, at -£256.3m NAV.
Arcadia group mgt charge of £42.1m
Pension deficit is £101.1m
Group companies creditor is now £184.2m
Key findings from the above:
Dividends paid by BHS Ltd to its parent company totalled £414m, and were paid from 2002-2004 only - a time when the company was strongly profitable. These dividends look fine in the context of the profits being reported at the time.
No dividends were paid out by BHS Ltd after 2004.
The company was profitable, and capable of paying the above dividends, and still had £86.6m in positive NAV after paying out the £414m divis, because at the time it was making a profit of c.£100m p.a.
Pension deficit - was modest pre-financial crisis, so there is no evidence to suggest that the divis paid out by Green in any way affected the pension fund. To suggest so is simply hindsight.
Figures being bandied about of £ 500-600m pension deficit do not correspond with the actual figures in BHS's accounts. The scheme even briefly went into surplus in 2008. This is likely to be because the deficit has worsened considerably due to QE, ultra-low interest rates, and better mortality. None of these could have been anticipated when the big divis were paid from 2002-2004. Also, I expect that the actuarial deficit would be considerably larger than the accounting deficit, as that is usually the case.
The management charges levied by Arcadia Group from 2010 look high. What were they for, and are the figures justified by actual services provided? We don't know. This needs investigating.
BHS Ltd only survived due to financial support from its parent company - which was a large creditor. So Green would have incurred a loss of perhaps £200m+ on disposing of BHS, from having to write off this debt owed by BHS to group companies. In addition to a reported £200m loss on writing off his purchase price. So it looks to me as if he might have broken even overall, if we ignore the Arcadia Group mgt charges. If those management charges were inflated, then there might be a question mark over that.
Taveta Investments Ltd
BHS Limited was 100% owned by an intermediate holding company, called BHS Group Ltd. That in turn was owned by Taveta Investments Ltd, which was the UK topco for Green's main retail operations, including Top Shop/TopMan, Wallis, Miss Selfridge, Evans, and others (the Arcadia Group companies), as well as BHS.
The Arcadia group companies were/are highly profitable, and therefore Taveta group accounts show big dividends paid out, mainly funded by cashflows from Arcadia. The press have conflated divis from BHS Ltd, with divis from Taveta, which of course is nonsense! The big divis paid out by Taveta had zero impact on the BHS, and its pension fund, since BHS was a subsidiary of Taveta.
I've also confirmed my research with someone familiar with the situation.
So what concerns me, is that Green is being wrongly accused of stripping cash out of BHS through divis, when in fact no divis were paid out by BHS Ltd after 2004. The divis that were paid out were reasonable in the context of profits, and perfectly legal.
The pension fund deficit only became a major issue after 2008, due to Govt policy on interest rates. Green's big divis from BHS Ltd pre-date this by 4+ years.
Overall then, I'm very concerned that the reporting in the press has been highly misleading on this issue. Now it may be the case that there are other skeletons in the closet - there often are with companies that go bust. However, based on its published accounts, it is factually wrong to claim that Green stripped cash out of BHS through dividends in a reckless manner. He didn't.
Having said the above, Green is certainly not off the hook. His sale of the business to someone totally unsuitable, for £1, in the knowledge that the inevitable outcome would be it going bust, looks foolhardy. Not illegal of course. Although it reminds me of the deal that the last Labour Govt did to distance itself from Rover Group, which subsequently went bust when in private ownership. So a bit rich for politicians to criticise Green for doing the same thing.
In my eyes, BHS is a failed format, and long overdue for being put down. There will be more jobs created by more vibrant retailers taking over its many prime stores. Therefore this is capitalism in action - brutal though it is - assets being reallocated to more efficient operators, and yesterday's formats like BHS gradually disappearing. We should not mourn this, it's progress.
Another point in the press which has irritated me, is that they say the company (Taveta Investments Ltd) is owned by shadowy offshore companies. What's shadowy about it, when there is a note in Taveta's accounts, saying that the ultimate controlling party is Tina Green? It couldn't be more explicit as to who controls the group!
Taveta Investments Ltd is controlled (87.8% shareholder) by an offshore company called Taveta Ltd.
Incidentally, I didn't know that Green had sold 25% of TopShop. It was sold for £350m, to reduce debt. Thus TopShop was valued at £1.4bn. It's been a fabulously successful business, and that's where most of Green's wealth has come from. Not from BHS.
What I find most alarming about the BHS situation, is that the press are reporting it so inaccurately, and that nobody is challenging them (apart from me now). This is because many people want Green to be guilty of wrongdoing, so are twisting the facts to suit their predetermined narrative. That's very dangerous stuff.
I'm not a particular fan of Green, but the truth is clearly that he supported heavy losses at BHS, for several recent years, until it became obvious that it had no future in its current form.
Avingtrans (LON:AVG)
Share price: 186p (up 13.3% today)
No. shares: 27.7m
Market cap: £51.5m
(at the time of writing, I hold a long position in this share)
Proposed (major) disposal - this is a very interesting announcement. Mgt are basically selling the bulk of the group - its aerospace operations. After fees, and paying off all group debt, it will have net cash of £47m. Some of this is going to be paid out to shareholders (no figures are given on that).
So this means the remaining business is only valued at £4.5m. Yet it has apparently quite exciting growth potential in nuclear decommissioning.
My opinion - this strikes me as a good deal - achieving a full price for disposing of the aerospace division. It also highlights that management seem to be good deal makers. I reckon this share could be heading higher, once people crunch the numbers.
Many thanks to the reader here who nagged me into looking at the figures a couple of months ago. I'm sitting on a nice profit of 43% now, so I owe you lunch! So do get in touch, and we can arrange it, if you have easy access to London or Hove.
Avon Rubber (LON:AVON)
Share price: 815p (up 13.6% today)
No. shares: 31.0m
Market cap: £252.7m
Interim results, 6m to 31 Mar 2016 - it's good to see prompt reporting here - a sign that good financial controls are in place. The market clearly likes the figures, with the shares up 13.6% today.
Although I'm not keen on the presentation of the P&L, which draws unnecessary focus to EBITDA, and also contains significant adjustments.
Tax - note also that the EPS figure is heavily flattered by a favourable tax charge this year, so caution is needed when valuing the company on a multiple of EPS. I would always normalise the tax charge first, to lower EPS.
Outlook - this sounds upbeat, but doesn't say anything about performance versus market expectations, which is the key information that investors need:
The Board remains confident that the Group will continue to make progress as the year develops and maintain our record of strong cash generation.
Trading is normally second-half weighted in our Protection & Defence business and we believe this will again be the case this year. We continue to see a number of higher margin export opportunities and while, as always, the timing of order receipt remains unpredictable, the DOD order we received late in the first half affords us production flexibility to fulfil these as and when they are received.
In Dairy, despite weak market conditions, the acquisition of InterPuls and the encouraging gains in Milkrite market share provide us with significant opportunity at the point milk prices start to improve. This, together with the sales and distribution platforms we have established in China and Brazil to service these rapidly growing emerging markets, means we have a Dairy business with excellent short and longer term growth prospects.
Balance sheet - surprisingly weak actually. NAV is £47.9m, but once intangibles of £45.5m are removed, then NTAV is only £2.4m - not much for the size of business.
The culprits are some debt (a moderate amount, no particular worries with this), and an £18.7m pension deficit.
Overall then, the balance sheet seems OK, considering the level of profits.
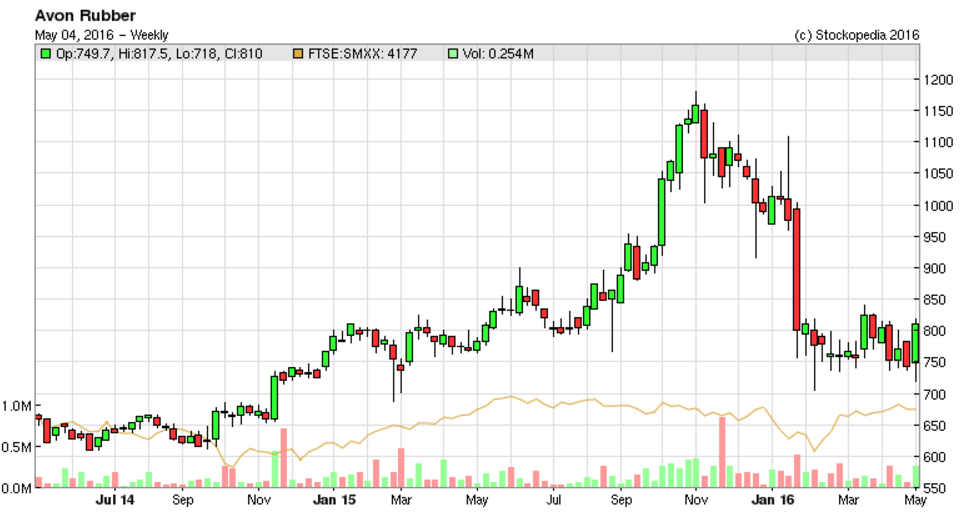
My opinion - last time I looked at this company, it was really expensive. However, I hadn't spotted that the share price had fallen so much this year (see 2 year chart below).
Based on existing forecasts, the forward PER will now be about 14, which sounds about right.
The divi yield is low, at only about 1.4%.
The group has a very good track record of growing profits, but I worry that the big gas mask orders may eventually stop, giving a greater potential for a profit warning perhaps?
Overall, I'm not really up to speed on this company, so don't have a particular view either way really.
I have to dash, as am putting on my FD hat this afternoon for a local small business.
Regards, Paul.
(usual disclaimers apply)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Dear Paul
Just wanted to add my thanks for the detailed breakdown of the BHS figures. Really interesting and as somebody else has said here, it should be compulsory reading by everybody who comments on the demise of BHS.
With regard to Sir Philip Green himself I really can not give an opinion. I have never met him and I certainly would not believe what I have read in the papers. However I am pretty certain he has been a net benefit to the UK economy. So he is rich and successful (never traits that Brits of any hue seem to admire for some reason) and he paid a dividend of £1.2B offshore to save say £600m in tax but it does seem to be forgotten that none of this is or was illegal.
I can understand why he paid the divi offshore as it is simply too large a take. That said if it had been me I would have paid the tax just so that I could be in the UK and with my wife for as long as I chose rather than the time dictated by the tax man!
Like Paul I look forward, hopefully, being cross examined by MP's.
As an aside I am surprised, knowing that his father died at (I assume as PG was only 12) an early age of an heart attack, that Green does not do something about his weight and if he doesn't I hope Arcadia has a succession plan in place.
BR
Michael
For info for any Next holders, Chronic Investor view is as follows:
Most of that sales decline is down to unexpectedly cold weather in March and over Easter, but other retailers - so far at least - don't seem to be hurting quite so much as Next. For that reason, we remain cautious on the shares and, at 5,180p, stick with our neutral recommendation. Hold
I think Paul's articles are more worthwhile reading though :-)
Sales are down 1%? Share price is down 37%, I think that is all in the share price. As for other retailers I think they are also struggling on the high street, yes weather was colder than normal. I would not take any notice of IC magazine.
Paul, great article and detailed analysis on BHS. We do love to knock our entrepreneurs. Not sure why people equate large financial gains with the entrepreneurs behind these ventures being likeable - Steve Jobs being a classic (US based) example, albeit imperfect. Carl Icahn maybe a better example. It seems a particularly British thing to go after those who are the brashest rather than basing on actual misbehaviour.
Whilst PG ultimately failed with BHS and it's repositioning over the 15 years of his ownership, I suspect by 2005 he'd reconciled taking a portfolio approach of backing his winner (Top Shop) and, having already made very significant returns from BHS, shifting this to being a cash cow / in run off. In value investing / private equity terms this may well have been the only rational decision. How many retail businesses with the scale of BHS can we point to that have been successfully repositioned in the last 15 years? I doubt anyone would have been able to justify an ROI to justify the very high level of cash investment that'd be required to reposition the business. Isn't this what Warren Buffett did with the original Berkshire Hathaway business to then fund his acquisitions?
Amazingly the press have talked about a hypothetical float that could have solved the BHS problem of repositioning by being able to raise additional capital from the City. Surreal - effectively risking pension fund money via naive fund managers buying a high risk and heavily promoted story from new managers that a very skilled entrepreneur wouldn't back.
As well as the very high intracompany charges and dividends, the property income received + current value are hard to get behind but all of these together will have made the deal a compelling success by 2003 when the business was recapitalised with debt.
It's worth emphasising is that the ultimate metric is cash on cash return (capital invested vs realised). Rather than notional P&L intracompany "losses", assertions that I don't think hold water in terms of PG being presented as losing money on this deal. It's also worth noting that whilst PG bought the business for £200m from Storehouse in 2000, it isn't clear how much cash investment the major shareholders (who appear to be PG / Caring / Hunter) provided. Which is the real metric. Indeed press at the time stated / in 2003 stated Robin Saunders of WestLB lent £200m for the deal, and together with a colleague ended up with 1% of BHS personally.
Paul I'd be interested in any words of wisdom on the Next balance sheet and debt. I've not looked in masses of detail but the gearing seems very high. I found the same issue when looking at Imperial Brands recently (although the ratio of profit to debt is much better for Next). These businesses have great track records but I find the leverage off putting - if circumstances turn against them is the debt going to limit their ability to recover? I'd be interested to know how/why you get yourself comfortable in the case of Next.
With AVG, the net equity of the deal exceeds the market cap of the stock.
Therefore even if the residual business is valued at £1 there is a gain to be had in this stock?
RE: BHS Pension deficit.
I don't get it.
How do pension deficits increase year after year?
Thought after Maxwell et al, it had been outlawed - both "borrowing" from a pension fund and companies voting themselves a "pension holiday".
Were the pension reforms after Maxwell window dressing, then?
Pension fund deficits or surpluses are a function of assets on one side and interest rates and life expectancy on the other. If interest rates rise, the deficits will fall.
xcity - I remember back in the day, the company I worked for, suspending contributions to the company pension fund because it was in "record surplus". I was outraged, what would they do if it ever fell into a deficit then?
I left that company eons ago. It went to the wall some half a dozen years ago.
All the rage at one time.
It's one of the consequences of defined benefit schemes where the company is responsible for making sure those benefits are paid. Now they tend to use long-term adjustments which is more appropriate, but they didn't then.
Defined contributions are better in this regard and might have had a better press if companies hadn't taken advantage of the switch to reduce contributions. And wouldn't look so bad if governments hadn't artificially reduced interest rates. They are much better insulated from employer bankruptcy.
Tricorn lost the RR pipes contract to AVG. At the time the CEO of TCN said that RR wanted them to work for nothing. Later TCN sold its aero division to AVG. At the time I remember AVG had some fibreglass Formula 1 business as well.
AVG have now sold their aero history at a time when RR will be applying even more pressure on margins.
If you look at the board of AVG they have a finance background and are probably good dealmakers.
What they do not have is a good engineering background or a theme for the group's activities.
I, also, do not know whether this is a good deal, but I would be very wary of "apparently quite exciting growth potential in <>"
apad
I would have to say that it looks as though TCN may have sold its aero related business to Avingtrans too cheaply .Reflects poorly on the management there.
According to this article, Sports Direct Mike Ashley is still planning to bid for BHS:
http://www.telegraph.co.uk/business/2016/05/01/mike-ashley-ill-save-bhs-and-all-its-staff/
In this article it says in 2002 "BHS becomes part of Arcadia after Sir Phillip pays £840m for the clothing chain. He makes £164.5m from dividends. In 2005, Sir Philip’s wife Tina Green, who resides in Monaco, receives a £1.2bn dividend". Is this factually correct? If it is (and I have no idea what to believe in the papers) then based on this newspaper statement she has taken more out of the company in one go than he paid for the whole thing... and twice the pension deficit that now exists for which 11,000 employees are dependent. Although it may be legal, is that morally right? Surely a £1.2bn dividend would have made a marked difference to the finances of BHS during its history covered by the time period Paul documents...?
I wonder if this BHS/SPD rumour is also why the SPD share price has dropped.
BHS & Phillip Green -
I think Paul makes a valid point that we mustn't judge a book by its cover. There are quite a few superficial similarities between Phillip Green and the infamous Robert Maxwell, (and I repeat superficial) least of all being the alleged bullying tactics and personal attacks.
But people should remember how, not just the media, but nearly the whole nation had condemned Christopher Jefferies for the murder of Joanna Yates in 2011. His odd mannerisms, furtive behaviour and louche personal life had convinced everyone that he was "clearly" guilty. (by the way, excellently portrayed by Jason Watkins in a recent ITV drama).
So personally I will reserve judgement until the weight of official enquiries and committees has run its course and given us the substance rather than the form.
Hi Paul, I don't know if you have seen the news item for Sportech winning their battle with HMRC regarding vat on spot the ball competitions. Could have a positive impact on BOTB as according to their last accounts they had a similar claim for £2.2m.
Paul,
One further thing to think about on BHS (and I haven't looked at the accounts) is how the initial deal was financed - was the company loaded up with debt that it struggled to pay back? Movement in dividends, while interesting isn't necessarily the only way to extract value, could be sales of assets at friendly prices or excessive management charges.
Apologies if you looked at this already.
Rob
Hi rjmahan,
I'm not sure how Green financed his original purchase of BHS, but there's no doubt he got a bargain (at the time), and there are question marks over how he managed to massively boost its profits so quickly after taking over.
That said, it paid UK Corp Tax on those profits, so I find it difficult to understand why he would have tried to inflate the profits of a private company, and then pay loads more Corp Tax. So that particular conspiracy theory doesn't pass the common sense test.
And no, BHS wasn't loaded up with debt. It had a sound balance sheet up until about 2010.
Regards, Paul.
Thanks Paul.
From memory, the BHS business was acquired from The Storehouse Group leaving behind the Mothercare business with the original management team. I believe the purchase was financed by a combination of PG's own equity (I think his first major deal prior to this was buying, turning around and then selling on the Jean Jeanie business leaving him with a decent pot of capital) and a £200m acquisition loan provided by Barclays Capital and one of the German Landesbanks.
Re AVG
I also hold but don't think it is possible to say whether or not this is a good deal. The aviation side seemed to me to have a very bright future. However, given the large cash return I wish AVG had given a guide as to the shareholder cash return and a timetable, as Melrose (MRO) always does in similar circumstances.
Paul, an excellent analysis on BHS and as always, it doesn't pay to pay too much attention to what is said in the newspapers.
They are businesses and as such the more sensational the headline, the more they sell. As an aside, rags like the Daily Mail, on slow news days, publish articles on some kind of outlandish weather prediction.
I read somewhere (in a newspaper perhaps?!) that circulation increased by over 100,000 on days of outlandish weather prediction. Nothing sells like fear (be it news headlines, or the majority of advertising that is grounded by fear).
By virtue of working in energy, I decided one day to see who provided them with such ridiculous forecasts. It turned out to be a tiny outfit somewhere in central London. Hardly a cutting edge weather forecasting operation.
I was surprised by the muted reaction to the Avingtrans (LON:AVG) deal this morning. I've held on and off for nearly five years (disclaimer: am currently a holder). A very sensible board of directors, and have been very astute over the years in realising shareholder value, e.g. in 2012 they sold Jenatech for a sum (if memory serves) not too far from the then market cap. They then used those proceeds to build up other parts of the business, fairly rapidly thereafter.
More info here: http://www.avingtrans.plc.uk/pages/history.html
I've no reason to assume that they won't do the same now. Energy, Medial and the roadsigns business have all been subdued performers over the past few years, but the sectors they operate in are beginning to turn - for example, Crown (who makes road signage) I believe has passed break even. And now management can devote more attention to the remaining businesses (I felt sometimes that they were too diverse, for what is quite a small company).
The Sellafield contract is 1/10th of the business that they could potentially win - given nuclear decommissioning is happening in other countries (e.g. Germany) there is definite potential in this area.
So although I like aerospace businesses (and like GKN (LON:GKN) and Senior (LON:SNR), both look cheap to me for what are world leaders in their fields), I'll stick with Avingtrans (LON:AVG) and see what happens. I commented to DGW that the company now reminds me of a mini-Melrose - high praise indeed as I'm a great fan of the Melrose ethos.
It's also worth reading the commentary in the annual reports from Roger McDowell, the Chairman. Always strait talking, it's a refreshing change from most of the drivel I usually read in such reports.
ReBHS
I see similarities with the press reporting on Mr Cameron's tax affairs, where everything was OK, all taxes paid, but the reporting implied problems. No one challenges the left wing media. Not even the PM.
Paul - Delighted you came on board re AVG, I have been a shareholder for some years and having attended a number of AGMs over the years come to view the Board as very astute in many respects.
Superb BHS analysis, Paul. It should reach a wider audience somehow.
Avingtrans - I have held the shares for a number of years and topped up when thex bought a piping business from RR. Even better, they then annouced that RR had given them a 10 year contract for pipes! Then two months later to sell the Aerospace operation (including the purchase from RR) for £52million (after debt) looks a fantactic deal. - see below
They are definately good dealmakers - lets hope they can do the same with their nuclear business.
Deal with RR
Completion of £3.5m Acquisition of Rolls-Royce pipe manufacturing business
Avingtrans (AIM:AVG) is pleased to announce that Sigma Components, which forms Avingtrans PLC's aerospace division, has successfully completed the acquisition of Rolls-Royce's internal pipe manufacturing businesses, which was announced on 29 January 2016.
Contract with RR
Sigma signs £75m deal with Rolls-Royce
Siigma Components, which forms Avingtrans PLC's aerospace division, has signed a ten year contract with Rolls-Royce valued at more than £75m to supply pipe assemblies for a range of engine programmes including the rapidly growing Trent XWB variants fitted to the Airbus A350.
Final salary pension schemes having been wrecked by various governments now all need to be closed to new money and managed down.
I would require all pension schemes, public as well as private, to transition to a defined benefit basis for all new contributions within two years.
Then I would require all private sector schemes to be progressively brought into balance and not allow any dividends to be paid out by companies until and unless the scheme was fully funded.
Unpalatable I know, but if things are allowed to carry on as they are it encourages financial engineering to ensure the liabilities end up dumped on the safety net scheme.
Any better ideas anyone?
Yes- simply wait until interest rates normalise from the unprecedented lows of the last few years. Pension liabilities are paid out over decades and are valued into a lump sum using a Government of AA Bond yield ( I understand.) Rising bond yields will reduce the capital value of the liabilities since £ 1 in the future is worth less in the present. Panicking over this large single figure based substantially on one current bond yield is mad and IMHO financially reckless. Charitably commentators may be ignorant. Uncharitably as the journalist saying goes "Never let the facts get in the way of a good story"
Sadly many pension managers under LDI have quite possibly handicapped future pensions by the reduction in an equity allocation and an overconcentration in low yielding bonds.
Economically all western governments are in economically uncharted and indeed previously considered impossible waters.
The difference between us is that I don't think interest rates are going back to what we would regard as normal any time soon. They can't because governments and mortgage holders would all be bust.
I'm old enough to remember paying 13% on our mortgage but I think we are in a new normal now.
I agree, can't see even 5% interest rates for at least 5 years. I remember 15% mortgage rate, ouch.
The implication of your words are that if one is overloaded with debt the only solution is to massage the market with artificially low interest rates for ever more. Given that the UK government is running a budget deficit and therefore debt is growing and given the current low economic growth rate , there is a real possibility of the debt burden growing ever larger on the economy. That is eventually an unsustainable situation - interest payments - eventually consume all government revenues. Japan is in the forefront of this situation and has continued far longer than most / all observers thought possible. Perhaps Japanese cultural solidarity is a factor.We wait and see.
My other problem with your words is that recognised star investors have said that the famous words you imply "This time is different" never apply.Sooner or later market forces assert themselves.
If a government could simply keep interest rates low regardless of inflation and market forces and also print money then how come countries through the ages eg Germany, Brazil, Argentina succumbed to economic and market crashes, bond default etc.BTW I too paid mortgage interest at 15% - but as compensation inflation boosted the value of our house..
Well, is it already different "As interest rates mark their seventh anniversary at the historic low of 0.5% this week, the figures will reassure Bank of England policymakers that they can keep borrowing costs low without fearing a rapid pick-up in inflation. Some economists have even raised the idea of interest rates being cut closer to zero". Yes later we will get back to boom and higher rates but it could be 5-10 years time. Japan has been in this situation for over 20 years.
Governments in the past have not acted or acted too late. Problem is now we are already at low interest rates when the next recession comes what options are left?
Rates were at 2% from 1932 to 1951 except for the two months of Aug and Sep 1939. Prolonged low rates are not unknown in the history. If you look at the interactive on the Guardian website it's our lifetimes since the 1970's that are the crazy times.
http://www.theguardian.com/business/interactive/2008/nov/05/interest-rates-history
The liability is usually index linked, so if bond yields go up at the same time as inflation, the impact on funds may not be that significant.
BTW if you are certain interest rates will "normalise" any time soon, you may want to make a fortune trading long rates derivatives.
Cig
Taking your BTW point first - timing is everything. Interest rates will rise if the last 500 years of interest are any guide - but when is completely unknown as is the speed of normalisation. Taking a short position with unknown timing which may be years into the future, can be a good way to lose a fortune especially since there is a significant carry cost. A possible straw in the wind is the sharp downturn in (corporate) bonds earlier this year when long duration IG bonds we held in GBP and USD dropped about 10% - stunning moves which quickly reversed to the original prices . The implication to my mind is that future sharp moves in the Bond markets will not necessarily be due or in the proportional measure of Central Government rises in interest rates but may caused by a stampede out of bonds by Fund Managers afraid of losses in absolute terms. Further as you may be aware Hedge Funds also look for any trends and then exploit it.
Your first comment assumes a "usually". There is no data I have seen as to the degree of inflation protection this and also where there is inflation, the index used RPI or CPI chosen may understate actual inflation. Further as I understand it some funds have limited inflation protection in terms of indexed benefits.
Finally the long end of the yield curve is fixed by markets not by governments to a significant extent. If yields go from +1% approx real interest rates now at the long end to a not unknown real interest rate of say 4% then there is quite a significant reduction in liabilities even if your assumption of a linkage inflation - interest rates is correct. The exact figures will depend on the level of inflation and interest rates.
Arcadia Group provided a whole chunk of different services for Bhs including sourcing and buying its menswear range, IT, some supply chains functions. Whether the management fee is the right number is a different question.
Hi Paul,
I think a proportion of the inflated management charges (£56.8M in one year as you state) should be included in the dividend figure. Is this just a way of hiding dividends?
What you do not cover is all the valuable property that was striped out of BHS and put into a separate Green company. This is how I think others got to the figure of £1.2bn. This is alot of support to take out of the balance sheet and could have been sold to cover the pension deficit or ground rent.
Hi Stocks321,
Yes indeed. I tried to look at the property side of things, but it was too complicated, since I don't know the market value of the properties concerned.
Note that BHS Ltd only had freeholds of £8.5m on its balance sheet (at Apr 2000) round about the time when Green took control. It did however have an additional £192.8m in long leases, and there was comment in the narrative saying that the company believed the market value was considerably in excess of that figure.
Property declined on the balance sheet over time, so there does indeed seem to be evidence of property assets either being sold, or otherwise removed from the balance sheet of BHS Ltd. The question is whether that was done at open market value (in which case no issue), or whether the properties were hived off on the cheap to other Green companies?
That's a much more complex thing to delve into, and can't really be done from the published accounts unfortunately.
A good point though to flag up, so thanks.
Although as the group was by far the largest creditor to BHS, it's not actually unreasonable for them to require BHS to sell its property assets to reduce group debt. That's what any other creditor (e.g. a bank) would also require in the circumstances. So again, it's all down to how you look at it.
Regards, Paul.
Very interesting analysis on BHS Paul
what I would say is that while the dividend issue is obviously a misnomer, the "management charges" of £50m per year is ridiculously high, and hence in a way how Philip Green has taken money out of BHS
Management charges go to his Taveta group, which is ultimately owned by his wife etc, who lives in Monaco...
Not illegal, i know but dubious.....
Hi DVB99,
I agree, the management charges from BHS to Arcadia are the biggest question mark.
I read somewhere that Green tried to merge a lot of BHS back office & distribution functions with Arcadia, to save money, but even so the £50m-ish charges look extremely high.
There again, the biggest creditor of BHS was its own parent company. So he wasn't actually taking money out - BHS was actually racking up a large debt (c. £200m by the time it went bust) with its parent company.
Note that the auditors were only signing off the accounts for the last few years after receiving assurances that the parent company would continue its financial support.
So if you read the mainstream press, Green was apparently plundering BHS, resulting in it going bust. Whereas if you actually look at its accounts, Green was financially supporting a heavily loss-making company for several years before the inevitable finally happened.
A fascinating situation. Very much also a lesson in DYOR - since you just cannot rely on what's reported in the press, nor what politicians or other commentators say. In practice, almost none of them have DTOR, they just repeat what they read, which then becomes widely accepted as the truth, despite being factually wrong!
I think Green will rip apart the MPs when he appears before them. Will be fascinating to watch, hopefully it'll be televised.
Regards, Paul.
Interesting reading. Agree with DVB99, the Arcadia management charge is just sickening, surely that's more than the whole salary bill of the average large retailer exec committee... and what exactly have they done for that money other than neglect it?!? Horribly greedy rich people playing with the lives of mere mortals they wouldn't want to mix with I'm sure.
And I thought dividends were supposed to progressive and covered by earnings? Here, what dividends were paid, were all over the place and frankly look reckless to me.
Rant, rant... :-/
Hi andrea341
In a Group Structure a mgt charge is an appropriate mechanism to normalise the financial results of a subsidiary that benefits from Group services that would not be available to it as an independent entity , we don't know what those services are but swan hunter above gives some vey material items.
Nobody knows the facts but everyone still feels able to brandish pitchforks!
The disposal of BHS looks like another kettle of fish but to my eye it looks a lot less simple than the press and politicians would have you believe.
Being rich is not a crime BTW
Paul
Thanks for the insightful report on BHS. Very interesting.
Also, thanks for rapid view on AVG. I also read the announcement with interest and concur with your conclusions. I too hold a long position and will watch developments with interest.
Regards, Howard
TopShop is 25% owned by Leonard Green & Partners, a mahoosive private equity company based on the West Coast of the US. http://www.leonardgreen.com/Investments.html
Thanks for the highly insightful BHS analysis Paul.
Much more thoughtful analysis than I have been reading in the papers, especially concerning the allegations of asset stripping and conflating dividends paid by the entire group with dividends paid by BHS.
Any chance on commenting on the recent Trak updates?