Small Cap Value Report (6 May 2015) - BOO

Good morning!
It's quiet again for company results today - I must make a note to take this week as holiday next year.
Today's report will be a little later than usual, as I'm heading into the City for the analyst presentation for Boohoo.Com (LON:BOO) which is one of my favourite stocks at the moment. I'd better get my skates on, as it starts at 9am.
Boohoo.Com (LON:BOO)
Share price: 27.38p (down 2% today)
No. shares: 1,123.1m
Market Cap: £307.5m
(at the time of writing, I hold shares in this company)
Preliminary results - for the year ended 28 Feb 2015 are out this morning. I've just got back from the analyst presentation, which was well attended - about 40-50 analysts there at a guess, so the company is certainly getting noticed. I asked an adviser whether the overhang from disappointed IPO buyers (who overpaid, at the 50p IPO price) has now cleared, and was told that they believe so - i.e. people who want to sell are now gone.
I'll spend a bit more time on this company, as it's one of my favourite growth companies at the moment, and is the only online etailer I can find which is strongly profitable, growing at a decent pace organically, has global reach, yet is still reasonably priced (house broker Zeus have it on a cash adjusted PER of 20.7 times their current year forecasts).
Here is the highlights table from today's results. I've highlighted the items that are most important, in my opinion;
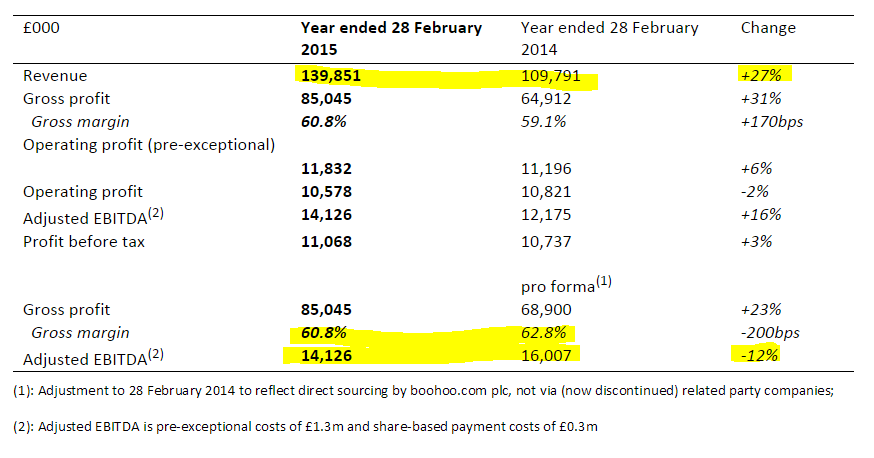
First thing to note is the strong top line growth, up 27% as reported in sterling, but up 31% in constant currency. BOO sales are strongest in the UK, at 67% of total turnover. Its other most important markets are Australia, France, and USA. The company sells into most countries in the world, but has decided to focus its efforts on the countries where it sees most potential. As the CFO jokingly commented,
"Mahmud's (the founder, who is known for his colourful language!) new F-word is 'focus'".
Mahmud only spoke once, and spent the whole meeting fiddling with his phone & looking preoccupied/bored, whilst Neil Catto (CFO) and Carol Kane (joint CEO) gave presentations & fielded questions.
Expectations at the time of the IPO last year were far too high, and the business had a slowdown in H2 of last year. The CFO was questioned about this, and blamed an "exceptional series of events" - the marketing campaign & launch of A/W range was delayed in Aug 2014, due to implementation of new warehouse management IT system. This was a mistake, as he admitted, "we've learned that we can't afford to have a slow start to a new season". Then of course the mild A/W weather (which was a genuine factor), This led to competitors discounting on price much earlier, and Black Friday caused them problems as it concentrated competitor sales in an unusual way. BOO responded by reducing its marketing spend to protect profits, which had a further knock-on impact on sales.
The CFO said that this series of factors are "not likely to recur again", and "we've learned the lessons from last year's under-performance".
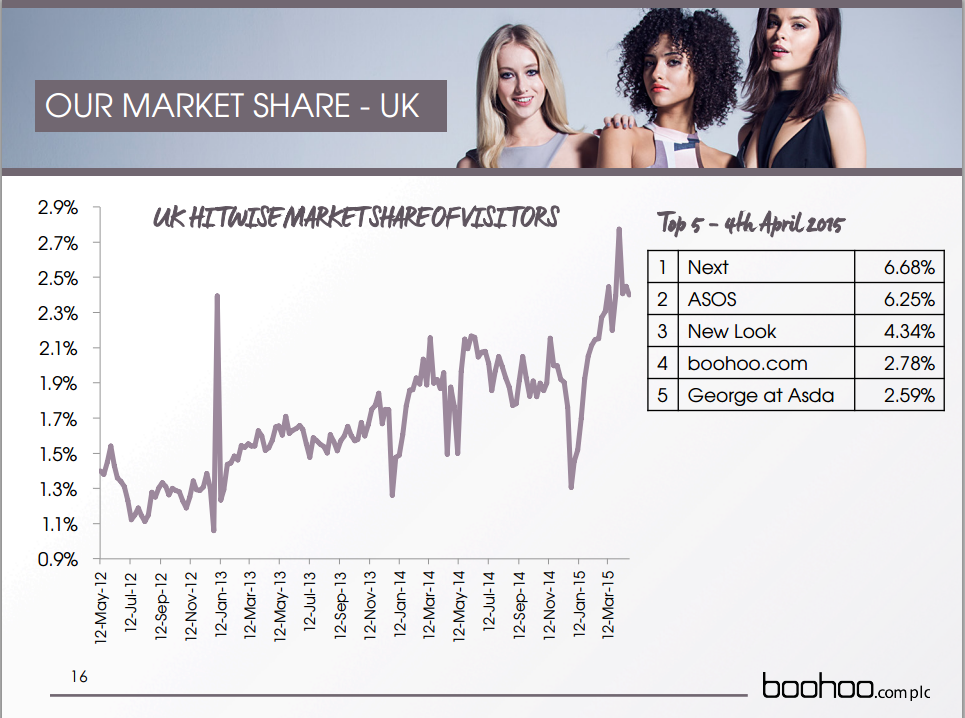
The presentation slide relating to market share shows encouraging recent trends;
Gross profit margin - is impressive, at 60.8%, especially as the company doesn't have all the costs of a chain of shops. Note that, whilst good, this was down from 62.8% in the pro forma figures for last year (which adjust profit to the same basis as this year, by eliminating related party sourcing companies).
Personally I'm relaxed about the margin - it's very high, and BOO has responded to a downturn in sales in Australia for example, by cutting prices. This has worked, and there was a strong recovery in sales in H2 of last year in that market. So a little off the margin is worth it, to drive higher sales. Demand is very elastic at this end of the market (low priced fashion).
The CFO indicated that the gross margin is likely to drop by about 70bps this year, as further price reductions are made to support growth, but that they will stay above the 60% level - more than satisfactory, in my view.
Profits - a number of options are given, but to my mind the most meaningful is pro forma EBITDA of £14.1m vs £16.0m last year. This is in line with revised expectations after the profit warning in Jan 2015.
Why has profit gone down, despite sales being up? This is due to considerable expansion in the distribution & admin overheads. The company is "investing ahead of the curve", in particular with a major warehouse expansion, which should mean they have capacity to expand considerably further.
Although one point that slightly concerns me is the dis-economies of scale as they expand - primarily that the warehouse is now so large, with so many product lines, that the manual picking process - people walking around the warehouse - is now getting slower, as the pickers have to walk longer distances. This might be automated in future, and the floors have been reinforced to be capable of holding the weight of such machinery.
The CFO said that he sees the benefit from this expansion in overheads flowing through this year & next year.
Other key points - in no particular order;
- Working capital - has a favourable profile, due to efficient stock management, so the business actually generates more cash as it expands.
- Really strong balance sheet - "great platform for future growth".
- Customers engage mainly by handheld devices.
- Heavy capex this year, £13m, for warehouse expansion (£8m last year).
- Current trading - all comments were favourable - "it's been a good 8 weeks", in line with mgt expectations. They sounded confident.
- Range extension - Carol Kane told us how well the new plus size range, and the petite ranges were performing. Also a gym wear range has been launched.
- Website is being re-designed to group products together into "shops within a shop", e.g. holiday ranges, festivals, basics, evening wear, blue (denim), etc. Should make it easier for customers to navigate a huge range of options.
- BooHoo is now no. 4 on hitwise - have overtaken key rivals Top Shop & River Island.
- Social engagement - getting good results from working with prominent Vloggers (video bloggers, e.g. Zoella)
- "Really good response to new ranges" currently.
Lack of an App - this strikes me as an absolutely bizarre omission for a fashion etailer - BooHoo doesn't have an App! Mahmud perked up and grumbled;
"I can't even tell you we have a shit App! We don't have an App at all!! It's been signed off though, our App should go live in about 60 days".
Whilst an astonishing omission, I think this could be a catalyst for an acceleration of growth. As one analyst commented, some competitors are getting 30% of their business through their App. If BooHoo's soon to be launched App is any good, then that could provide a nice uplift for sales later this year - customers seem to browse on mobile devices, but order on a PC at the moment, which seems a crazy way to arrange things, and must be holding back sales to some extent.
Valuation - the company has surplus cash of £54m at end Feb 2015, so that's 4.8p per share. It's obvious that the company doesn't need this cash, and there was talk of a share buyback recently. Therefore I think it's valid to deduct this cash off the share price of 27.38p, taking us down to about 22.6p which one is paying for the actual business.
Using the figures from Zeus Capital, adjusted EPS for the year just reported was 0.89p, so the ex-cash PER is 25.4. For the current year, Zeus are forecasting a modest rise in adj EPS to 1.12p, so the ex-cash PER drops to 20.2 times. In my view that's not an aggressive rating at all, for a company that is growing organically at an impressive rate.
Note also that BooHoo generates a much more impressive net margin than any other UK listed etailer - ASOS (LON:ASC) makes lower gross and net profit margin, and its profits have been steadily falling, as a percentage of turnover in recent years, so its sky-high rating looks to be highly questionable, in my view (disclosure: I am currently short of Asos shares).
I believe that, following the Jan 2015 profit warning, analysts are possibly now being too conservative with their estimates for BooHoo. There is a chance that BooHoo could get an Asos-style re-rating if sales take off in the USA - the signs sounds positive there - they are setting up a USA HQ, and have been pleased with the performance of their marketing trial in the New York area, including a pop-up physical shop, combined with "meet the bloggers" type events. All in all, BooHoo seems very tuned in to the whole social networking generation, which is good as that is its target customer base.
Balance Sheet - is bulletproof. The current ratio is terrific, at 3.66, and includes £54.1m in net cash. So you get a very strong cash buffer included with these shares. It makes me wonder why they raised so much cash at the IPO, which they clearly don't need. So hopefully a decent divi should arise at some point.
Note that the company capitalised £2.4m of intangible costs in the year, which needs to be taken into account when looking at EBITDA. It's not an excessive amount though. There is no pension fund issue, as it's a young company, so no legacy issues to worry about, thankfully.
Q&A - the analyst meeting went on to Q&A, here is a selection of things I jotted down;
Q1. Is the 10% EBITDA margin sustainable, and should we see that as a minimum achievable target?
A1. It's the right ballpark. Don't see it as a minimum though. We want to exploit growth opportunities when we see them.
Q2. What further investment is needed?
A2. Mostly done, or in progress (e.g. warehouse). We want more people in IT, and increase headcount in USA.
Q3. Capex guidance?
A3. £13m this year, c.£10m next year.
Q4. Will the warehouse be fully mechanised in due course?
A4. Something we're considering. Would only be done to accelerate growth and/or if achieved cost savings.
Q5. Currency hedging?
A5. We're fully hedged for the next year.
Q6. Picking costs?
A6. About 60p per unit (not sure if this was per garment, or per order?)
Q7. (from me!) Product quality appears to be patchy, judging from online reviews & market research I've done myself. Are you aware of this issue, and what are you doing to sort it?
A7. Carol Kane replied that quality issues only relate to a small number of items, and that negative reviews are rare. They have increased their quality control headcount from 3 to 20, and monitor the whole supply chain.
(I was disappointed with this answer, as if you ask the target customer base, they all say the same thing - product quality is variable, but it's cheap - so you get what you pay for. So I would have preferred management to have properly acknowledged this issue).
Q8 (also from me) They lost business last year at Xmas, as customers returned to the High Street over busy period, concerned about delivery delays. What are they doing this year to reassure customers that there won't be late delivery problems?
A8. Again, a defensive answer from Carol Kane, who missed the point unfortunately. Instead she said that BooHoo hadn't had delivery problems last year. I wanted to know how they would reassure customers in advance this year, and hence avoid a dip in Xmas sales again, but never mind.
Q9. Plans for wholesaling?
A9. Being trialled with Asos, and also in India & somewhere else. A new area of the business, we're setting this up now, from scratch.
Q10. Marketing spend?
A10. High at start of each season, then declines. Will be about 15% of turnover globally. Concentrated into key markets.
Q11. Next day delivery?
A11. Doing more offers for this, as good response rate in UK.
My opinion - I really like this company. It's delivering good organic growth, and has international expansion underway, as well as a leading position in UK, younger, cheaper, fashion.
The rating may not look cheap at first sight, but once you adjust for the surplus cash pile, and compare the stratospheric ratings of competitors, a case can be made for this share actually being good value, which I think it is.
Moreover, it seems that the profit warning a few months ago was mainly due to expectations being too high at the IPO. If you ignore expectations, then the business is actually performing well - growing the top line strongly, all organic remember, and maintaining a decent level of profitability despite absorbing increased costs related to future growth.
The company's website has the presentation slides, and a recording of this morning's webcast, which are well worth looking at/listening to, the webcast in particular, as it is basically the same as the analyst meeting, with commentary and slides. Here is the link for that.
I think there is scope for the share price to continue recovering, as market confidence gradually rebuilds. It takes time for the market to trust a company again after a disappointment, but in my view that has created a buying opportunity to get into a company that is going places, at a reasonable valuation.
As always, never a recommendation, this is just my personal opinion. Sometimes I'll be right, and sometimes wrong. So please DYOR in the usual way. Views from readers are welcomed in the comments section below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
I just bought some after putting it through my analysis.
Paul,
Please can you stick your neck out and give us your estimate for Boohoo.Com (LON:BOO) medium term future EPS growth rate? I would use this information to calculate the Graham Formula Margin of Safety.
Hi Warranstar,
Gosh you're putting me on the spot there! I don't know is the honest answer of course - forecasting is just educated guesswork really, and I don't think anyone can meaningfully forecast more than about 2 years ahead for most businesses.
It's complicated by the fact that Boohoo.Com (LON:BOO) are in rapid growth phase still. So they're "investing ahead of the curve" on numerous fronts, especially the big jump in admin costs, and warehouse costs, which they implemented in 2014/15. So that is getting the busy ready for much greater sales volumes.
My main impression from the analyst presentation is just how busy they have been, improving and expanding the business on many fronts. It reminds me of my days at Pilot, when we were growing the business very fast, it was tremendously exciting - but costs are stepped - so you have to invest in e.g. an HR Dept, which is a burden in year 1, but then the cost only marginally increases as the business say doubles in size. You just add in one or two extra assistants, whilst the core mgt are able to handle a much bigger business.
That's the stage BOO is at now. I have really high hopes for this share, with a 3+ year view, as I think they are doing so many things right. And now that it has temporarily disappointed, the ex-cash rating is modest for a rapid organic growth company, at about 20.
Overall then, I would suggest perhaps a relatively modest, say 20% rise in EPS is possible this year, but then maybe a 20-30% rise in EPS for several years after that. I think the launch of their App in 60 days could provide a good boost to sales, it's amazing they don't have one yet. You have to go via this online magazine they created, or through Safari.
There's a lot of competition, but Kamani is extremely experienced in this sector - he's a bit like a Philip Green rag trader. We used to buy gear off his company in the 1990s, when I was in this sector. It was cheap & cheerful stuff, but they have very good supply chain contacts.
I think the trick he's pulled off, is to bring in a professional layer of management to manage things, now that the business has grown a lot larger than its entrepreneurial origins.
The mood music was all very positive about current trading, trends, etc. So I think they are more likely to meet, or beat expectations going forwards, which at some point should trigger a nice re-rating. Obviously they want to get it back to the IPO price of 50p, but I think we may have to wait until next year for that.
Regards, Paul.
Paul
I appreciate the quality and length of your reply.
Thanks
Having speed watched that video. What an inane load of old ......still if the bird got her kit off it would be even more popular. Bit of a looker.
And you wonder why so few women engage with investing bulletin boards.
Hi Paul,
Re an earlier poster and the Brighton connection : you've now added (a) be good looking, and (b) personable & a bit quirky
Three out of three......you are pewdiepie's Doppelgaenger and I claim my £ 5. !
How's the £ 1 diet going ? Google 'bullet-proof coffee', if I haven't suggested before. Mind you, premium coffee + grass-fed butter + organic coconut oil would probably break your budget....
ATB
Thanks for the excellent Boo write-up Paul. I really hope that this stock is going to be a North of England success story but I have my reservations. I think the group is being overambitious on the international front, a financial graveyard for many UK retailers, and am uneasy about the lack of interest shown by the company's founder Mahmud at today's investor presentation. Maybe he is a brilliant internet retailer, but his failure to participate more fully in the investor presentation, combined with his recent far from flattering press interviews, suggests that he might be far better suited to running a private company than a listed company. My final concern relates to Boo's logistics infrastructure. I am not a logistics expert but have been to have a look at Boo's new Burnley warehouse on a couple of occasions. Whilst it is a very big "shed", its location seems less than ideal. Not only is Boo's logistics centre situated near the end of the M65, a motorway to nowhere, but Boo's delivery trucks have to travel through Burnley to access the M65. One might have expected Boo to site its logistics centre next to a motorway junction, like many internet retailers. Last October's resignation of Boo non-exec director Petar Cvetkovic, a logistics expert, only six months after Boo's IPO also raised a warning light. Maybe I am reading too much into his departure, but it strengthens my suspicion that Boo's expansion plans are being "done on the cheap" and may not be as well thought out as one might hope.
Hi Paul,
I'd be interested in hearing your views on the free cash flow compared to the market cap of BOO, as I make free cash flow about £7M against a mktcap of approx £314M, a whopping 44 times.
The company reports free cash flow of £5.843M, so an even bigger multiple on their own calculation.(53 times).
Do you think this still looks like value or GARP?
Regards
mrwhits.
Hi MrWhits,
The free cashflow figures you mention are impacted by the fairly heavy capex spend on the warehouse extension - they are gearing up to be able to handle sales of £500m+.
So in the context of this being a company which is expanding quite rapidly, and incurring heavy capex, it's impressive that they are generating any free cashflow at all! Most growth companies are cash hungry at this stage of their life.
Wind forward several years, and if all goes well, I reckon this company could be an absolute cash machine, throwing off buckets of free cashflow, once the capex is done.
Importantly too, there is no risk of any dilution here - as the company is already cash generative, and has lots of surplus cash on the balance sheet, so there should not now be any fundraisings needed.
Who knows, they might even bolt on some smaller competitors? Note that they have a Call Option (for £5m) to buy PrettyLittleThing.com
Regards, Paul.
Paul, any thoughts on Gulf Marine Services (LON:GMS), please?
Many thanks,
Jane.
Paul - thanks for the very comprehensive review of Boohoo results and meeting. It's a shame that more PIs can't get access to the analyst meetings.
Hi Glaws2,
Indeed, putting on my "Press" hat, does have distinct advantages, in terms of access to companies & meetings.
That said, Boohoo.Com (LON:BOO) recorded a detailed webcast, with slides, which is available here. This gives you the same info that we had at the meeting.
Regards, Paul.
Hi Paul...and anyone else interested in Finsbury Food (LON:FIF) - they made an interesting sounding acquisition today. Any thoughts?
Regards,
Sully.
Hi Paul,
Thanks for the detailed report on Boohoo, its one Im considering.
As you seem to have some time, GMAA results are out today, don't look too bad?
Also I would be interested in your views on Pure Wafer sp.
Herbie, have you read the PUR RNS - it's all in there. They have settled the factory fire insurance claim and won't be rebuilding, instead returning excess proceeds to shareholders. So PUR now valued at insurance proceeds ('significantly more than 60p') plus the remaining plant in the US.
@ Redrumtum
Yes of course I have read it but its not very clear to me, on the BBs there are debates about the value of the company now, many have sold, not surprising because before the fire the sp was about 60p, now after the fire and claim settlement (which is not disclosed) the sp is about 108p, I was hoping for Paul's views.
Paul
Do you have any concerns about the high Montier C Score for Boohoo.Com (LON:BOO) ? Does it highlight any red flags for you?
FREng
Hi FREng,
I've had a quick look at the Montier C Score for Boohoo.Com (LON:BOO) and it looks a red herring to me - none of the risk factors are relevant, or a problem (see below).
Also, the Altman Z-score looks a red herring too - possibly because it hasn't updated yet for the post-IPO fundraising. Clearly with its huge cash pile, BooHoo should be deep in "safe" territory.
Still, it's always worth checking out any potential red flags, but there are no issues here whatsoever, in my view.
Regards, Paul.
Hi Paul
Thanks for the comprehensive write up about Boohoo.Com (LON:BOO). One thing I noticed from the FY results was that menswear had experienced growth of 39% in the last financial year, but still only represented 4.2% of sales. They allude to to this being a significant growth opportunity going forward. Did they elaborate on this at the presentation?
Best wishes,
Imran.
Hi Imran,
Yes, menswear was mentioned. Carol Kane mentioned that a blogger that Boohoo.Com (LON:BOO) works with, called Marzia Pie, has a boyfriend called Pudding Pie(??) or something similar. So they've got him wearing BooHoo gear, and that's helping to boost menswear sales.
The Vloggers are the stars of today. It's amazing - the top Vloggers, e.g. Zoella, have more followers than the big fashion magazines, and are incredibly influential - e.g. we heard today how when a new Zoella video went live, featuring BooHoo items, it lifted BooHoo significantly up the Hitwise rankings, in just 4 hours!
Regards, Paul.
Marziapie's boyfriend is pewdiepie. Does silly youtube videos that make him millions as he has more viewers than most TV programs. Probably the most famous person in the world you've never heard off. He's Swedish but lives in Brighton:
en.wikipedia.org/wiki/PewDiePie
Don't we know another famous blog and video star who lives in Brighton? :-) Clearly a hot bed.
Hi Steviej,
Thanks for the info on blogger pewdiepie. I've just been looking on YouTube, and he has an astonishing 34.4m subscribers to his channel!
Here is the BooHoo "haul" video he did with his girlfriend.
It's one of the things I like most about BooHoo, that they are focused very much on this blogger trend. What amazes me about these blogger videos is that they don't have any discernible talent, but all that is required is to (a) be good looking, and (b) personable & a bit quirky. They then seem to build up a fan base, who enjoy watching their inane videos.
As long as the audience buy their clothes from BooHoo after watching these videos, then I'm happy!
Regards, Paul.
Hi Paul
Just thought I would let you know I was working in the local Tech last week. The catering students hang their coats and bags on the hooks outside the kitchens. Twenty eight coats; seven with Boohoo.Com (LON:BOO) labels. Wish I had bought some!!! (Shares, not coats!!!)
Its not too late, sp has drifted down lately. Compared to Asos it looks a bargain.
Order in!