Small Cap Value Report (Thu 2 Mar 2017) - RBG, IND

Good morning!
It's just me writing today, as Graham's having a day off.
Revolution Bars (LON:RBG)
(at the time of writing, I hold a long position in this share)
Meeting - I was lucky enough to attend a meeting yesterday with the CEO & CFO of Revolution Bars. Management ran us through a similar set of slides to the ones on their website here.
I was tremendously impressed with management - my impression was of serious, competent managers. Strategy is very clear, and they seem to be executing well.
Here are the points I jotted down;
Premium bars + casual dining - so quite differentiated from competition.
Roll-out is gaining real momentum.
Plan is to achieve double-digit sales & earnings growth each year.
High ROI of 38% on new sites, which is sustainable.
Relatively small number (66) of large sites - so they can manage sites very intensively.
At IPO the plan was to open 4 new sites p.a.. This has now increased to 6 new sites p.a..
Pipeline of new sites has grown to 26 sites - very confident can do 6 in FY2018 and FY2019. These are at various stages of planning - which can be a lengthy process. So growth in next 2 years is guaranteed, due to new sites pipeline.
H1 EBITDA grew by 13.6%, vs. revenue growth of 12.7%.
Higher depreciation charge, due to new sites opened.
Expecting profit growth in H2, due to new sites + LFL growth from existing sites.
Strong cash conversion.
Dividend increased 10%. Scope to be more aggressive with dividends in the future.
Revolution & Revolucion de Cuba brands have pricing power, due to premium products, high quality fit-outs, nice ambience, and entertainment (e.g. live music on busy nights).
Key area of procurement is wet sales. Have supply contracts to 2019, giving protection against cost price inflation from weak sterling.
We are a "lighthouse" operator - i.e. premium drinks brands want their products & brands on display behind the bar, which helps when negotiating cost prices.
Living wage - not seen as a significant problem, as many staff are under 25, and those above 25 tend to be in managerial roles, so are already earning above living wage.
Staffing costs steady at 22.9% of revenues.
New sites - are over-staffed to begin with, to ensure high customer service. Then efficiencies can be achieved once everyone is trained & experienced.
European Union staff - not stated what the proportion is, but key staff (managers) are nearly all British. They see Brexit as "no big issue" for the business.
Business rates - there will be an impact, of £0.6m p.a. extra cost from April 2017 onwards. Already budgeted for. Only have 5 units in London, hence why impact is not worse.
Rents on new units are very competitive, which is offsetting upward rent reviews for existing units.
Keeping older units updated, so always fresh, with maintenance capex.
All 4 new sites this year are doing really well. Not seen any cannibalisation of business from operating 2 brands in same town - e.g. Reading. Different demographic - de Cuba attracts 30's mainly, whereas Revolution attracts 20's.
Roll-out is being done very carefully, so not making any mistakes (which can be costly due to long leases).
Not had any site that hasn't worked in the last 5 years.
Rent is 7% of revenues, which is extremely low - industry average is about double that.
New sites typically come with about 1 year rent-free period, which is spread over the term of the lease through the P&L.
New Rev de Cuba site in Reading was given as an example. Site was empty for 4 years, at asking rent of £180k. Deal eventually done to take it at just £90k rent (I am staggered at this, as it's a huge & busy bar, so it must be an absolute gold mine!)
Customer dwell time is very good - as people come in for drinks, then eat, then stay for more drinks & entertainment.
No other chain is doing this business model. Closest competitors are independents.
Sites are refreshed (.e. refurbished) every 4-5 years, to keep standards high.
Proud of being a good employer - in Sunday Times list of best employers for last 9 years.
Franchising - question asked had they considered this? Had been approached, and it's something they might do longer term, but internationally, not in UK.
Market size - easily 100 Revolution, and 50 Revolucion de Cuba - so scope for the business to more than double.
History - 3 or 4 years ago the brand was repositioned, and £10m spent on refurbishing the existing estate. Some non-optimum sites (e.g. wrong layout, not enough kitchen space, etc), were hived off, outside the group.
Profit concentration - I asked (prompted by a reader comment here, thanks for that by the way) whether there was still a high concentration of profits - something like 86% of EBITDA generated by the top 25-ish sites, was in the IPO document. They said that figure has since fallen, due to successful new site openings.
Planning consents - a key competitive advantage - this company applies for A4 usage (enabling them to operate as a full bar), which is a lengthy & difficult process. Hence why new site pipeline is so long. Rent is not paid until the new units are occupied. Many competitors don't go to this length, and instead have A3 use - restaurants - which restricts opening hours & size of the bar area, thus limiting their turnover.
Smaller sites in affluent areas have been tried, and work well. This gives scope to open in more locations.
Larger sites are better, as they achieve economies of scale.
Dedicated new site opening team - they've just opened 4 sites in 3 months, so working well.
Expansion creates a buzz amongst staff, and gives opportunities for internal career progression.
Feedback from customers is vital - over 900 feedback forms are received each week. Plus Trip Advisor is monitored closely, and social media.
Tough market but have maintained c.2% LFL sales growth, at steady profit margins.
Biggest selling product are cocktails.
New vodka supplier - Ketel - a premium USA brand, very popular there. Fixed price for 2 years, slightly cheaper than previous main brand used.
All products are premium , e.g. cocktails. No regular brand of beers are sold. So think Peroni instead (yum!). Key differentiator.
Significant pre-bookings for drinks. Each site has a dedicated sales manager. Customers are increasingly pre-booking for large groups, parties, etc.
Cocktails are difficult to make at home - and lots of staff training required. So less competition from off licence sales & people drinking at home, which is more of a threat to regular pubs & wine bars.
Revolution does everything well - e.g. each new site they spend £27k just on ice machines! Cost of fit-outs (c. £1m each) creates barriers to entry.
Typically £8-9 per drink (for cocktails), so when price increases are necessary, then adding say 5-10p is less noticeable to customers than when a pub puts 5-10p on the price of a pint.
Food - is profitable. Small plates are popular. All freshly made. Increasing number of specials.
There is scope to increase food sales - this will be a key area to drive future LFL sales growth.
An app is being developed, to enable customers to order & pay for drinks (fantastic idea!), which will be combined with a loyalty scheme. Will be tested this year, and launched later. Will be unique. (I think this is a wonderful idea, and should also drive LFL sales).
Digital marketing - incredibly important. Very high level of Facebook likes, a long way ahead of the competition. So can communicate much better with customers.
Possibility of acquiring groups of new sites, and gradually converting them. Although nothing actively being planned on this, but opportunities may arise.
More sites in London being sought - only have 5 at the moment: Leadenhall, Clapham, Battersea, Richmond (and 1 other that I missed). A suitable site in Putney is being sought.
Bank facility has been increased to £10m, it's a RCF. Very cheap interest rate.
FD (Chris Chambers) is leaving - this unsettled the market when announced recently. He was asked why he's leaving, at this meeting. He explained that when he had taken the job, he understood it would be a North-West based role. However, in reality it has involved a lot of travel around the country, and often very long hours. Having 2 young children, he was unhappy with work/life balance, so raised the issue with the CEO. They both felt it was best for him to step down now, rather than stringing it out. It was abundantly clear at the meeting that this is an entirely amicable parting of ways, with nothing untoward underlying it. I thought the FD (Chris Chambers) is excellent, and he clearly has an excellent grip on things, reeling off facts & figures in this meeting. So it's a great pity he's leaving. Let's hope his replacement is as good. The key takeaway for investors, is that there's nothing to be concerned about with regards to the FD leaving. He wouldn't have even been at this meeting, if there was. Also the dynamic between the CEO & FD was excellent - there's clearly mutual respect there, and they clearly work well together.
The StockRank is OK, but not spectacular;
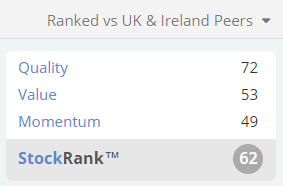
My opinion - I came out of this meeting absolutely thrilled to bits (which can be dangerous! Hopefully not so in this case). I think the CEO is excellent - clearly a very safe pair of hands - experienced, clear-thinking, and very much on top of his brief. The outgoing FD is excellent too - pity he's leaving - more on that below.
This business is quite obviously the wrong price, in my view. The forward PER is only just over 10, which is just the wrong price for a successful, self-funded, net debt free, roll out. I think a more appropriate PER would be at least 15, so there's a fairly easy 50% upside available on this share in my opinion.
I think the missing link is a lack of private investor interest. This often happens with new floats. The shares are placed with institutions, leaving a gaping hole where an active private investor shareholder base should be. That takes time to build up, and needs to be actively encouraged by the company & its advisers. I can't see any evidence that the company or its advisers are even aware of this issue, let alone doing anything about it.
So I strongly encourage the company to get out & about, and give some presentations to private investors, as well as to the city. This is a terrific business, and very modestly priced. Clearly under-priced actually. So generating some private investor interest is the vital next step to the shares re-rating.
I think the company is a sitting duck for a takeover bid too. I'd be gutted if someone came along and tried to buy it for say 260-270p, as I think the business would be worth much more than that in say 5 years' time - which is my intended holding period. By that time it should be a much bigger business, and probably on a higher rating too - so the opportunity here is ideal, as shareholders should hopefully benefit from the double benefit of higher earnings & a higher PER. Combine the two, and you get lovely upside.
It's very rare to find a decent growth company on such an astonishing cheap rating. Even more so when you consider that it also has a bulletproof balance sheet with nil net debt. The valuation just doesn't make sense at all to me. Perhaps I've missed something negative, of vital importance? But I can't for the life of me think what it might be. If you can think of anything, then please post a comment below. I always like to consider the bear view on stocks I hold. I'm probably going to buy even more of these shares (it's already my 2nd largest long position), but am having trouble deciding what to sell, to raise the money.
Sorry, I'm not getting any further with this at the moment. Will pop out for a while, then revisit it once I've recharged my brain with some fresh air. Further update this evening, I'll Tweet out when it's done.
Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
Popped into my first ever Revolution Bar on Monday. Was only planning to walk through to a meeting from the car park, but they had half price Monday food promotion, and a perky waitress invited us to sit down. About half full (upstairs closed) which I thought was good, but she said it's usually busier (it was raining) and always "rammed" Monday evenings.
Encouraging, was my verdict.
Jon
Good article, thanks, with plenty of detail and which has given me reassurance in continuing to hold this share despite recent volatility.
excellent
Huddersfield RB busy on Sat early evening and said to be very popular especiallly with students. RB prices are a sure way of accelerating student debt!
Richard
I intend to make a field trip in the interests of research to Leeds and Harrogate RBG. Will report back.
Paul,
sorry I did not recognise you and say hello at the Revolution bars meeting at Numis. ( we had met at the Loop Up CMD last month).I didn't realise it was you until reading your above report on the company!! Apologies. Peter
Went to the Richmond RBG last Sunday at about 1:30pm looking for something to eat (more in the snack line that full meal). Out of roughly 20 tables about 6 were empty. We were told on arrival that if we wanted to eat (even snacky stuff) we would need to wait 1 hour. It took just a few seconds to decide that we were off.
Can only hope that this was a one off.
Sorry Stokie - hit down by accident
Fantastic analysis as usual..wish I had bought a few days ago when Revolution came onto my radar!! Thanks Paul
Hi herbie47,
The gross bill for 3 of us (self, niece and her partner) came to about £ 60 for (good) food and drinks, non-beers for me and foreign beers/premium G + Ts for my fellow researchers.
We got a couple of 2-for-1 deals on both food and drink using the card , from what I could see would have been able to take advantage of similar offers / promotions even without.
HTH. At some point, my diligence will take me to Nottingham , to try out the sister Revolucion de Cuba site.
ATB
OK I see, thanks.
Hi all,
DMOR'd a couple of weeks back with my daughter (RBG Clapham) and niece (RBG Loughborough) . Reasonably early in the evening , so both venues were mainly populated by the 30's demographics + adult families. We were told that the young crowd tend to come along later (presumably after cheaper drinks elsewhere), I got the sense that RBG is consciously moving upmarket/up price point whilst still retaining its earlier client base : there's still an offering of exotic/"adolescent" shots - bubblegum cocktail, anyone ? - but that's only part of the picture.
Tip : If your efficient server tries to cross-sell an RBG loyalty card , do take it up ! For £ 3 you get to try a range of offers, with impressive discounts - we "saved" over £ 20 on the second visit....and I'm a non-drinker. ;->
ATB
Eeks £20, how much did you spend? Of course the mark up on spirits is very high.
RBG - did some field research early Wednesday evening in Richmond (Surrey). 27 customers while I was there (about 1/2 hour), many eating and drinking. But felt rather empty as it is a barn of a place and upstairs terrace bar was closed. Hope to do more field work in Huddersfield this w/e. However I am clearly not the target market. Do not hold (yet).
Richard
£100+ of gross property on the books. If you squint a bit, another £100 employed off balance sheet. Give them credit for every penny of depreciation and you still have a business that's structurally single digit return on capital. Trades a bit over 1 times sales, seems fair to me?
Sorry I didn't get round to writing about things.
Cheese,
PP./
Paul - look forward to your thoughts on Indigovision (LON:IND) when you are ready but please put your health first - I am very worried about your circadian rhythm.
They have gone up and then disappointed so many times in the past but now look like a value play with balance sheet $19.3m including $6.2m in cash cf MCap $17.1m. Forward p/es are 9.4 then 6.7 (@183p) based on house broker N+! figures available here:
https://www.indigovision.com/Portals/2/Documents/Reports/2017/Broker%20Notes/IndigoVision%20Group_CC_020317.pdf
sharw,
Thanks! There's no issue with IND - I read the accounts in my local greasy spoon, and it looked alright.
Its a struggle to write things sometimes. Anyway. As you know, I love change, if that is what you require! Here comes the mirror man! Ooooooh Cheeeesse!!!! (if that's what you require?!)
Cheese, PP.
Your points are well taken simoan. I have a slightly different perspective on both your points.
Weak sterling opens many U.K. companies up to takeover, not just super cheap ones. There was a great article by the naked fund manager on research tree recently https://www.research-tree.com/blogs/the-naked-fund-manager/m-a-one-reason-why-i-m-still-bullish-on-uk-equities - so maybe more opportunities from takeover gains for a while yet.
Regarding your SR point, I have many 90+ ones in my PF and I see some toppiness for sure but not many are on ridiculous PERs (10-20 typically) and virtually all pay a dividend (2-5% typically). I have a lot of high QR holdings, about half have 80+ momentum rank. The stocks that fit this profile generally have a low value rank. Then I have a high yield segment (which is lower weighted at present) which tends to be high VR with about half also having 80+ quality ranking. My intention is to top slice some of my gains from the QM segment into the VQ segment which I have begun doing. However, it is the prospect of takeover fever that is holding me back.
Sentiment is a funny old thing though and can turn on a sixpence, so while generally bullish, I share your caution.
Keith Ashworth-Lord released his funds monthly factsheet two days ago revealing he has bought Revolution Bars (LON:RBG) - I'm not sure if that has anything to do with it sp moves? It's still very cheap
Hi Paul - excellent write-up.
Mark McQuater the CEO has a long and successful history of leading companies in the pub, restaurant and hotel sector. It really looks like this company ticks all the major boxes. Like you I am puzzled as to why the price anomaly has remained for such a long time; efficient markets and all that.
Declaration: I have had a modest stake but now wish I had taken it more seriously.
It's very rare to find a decent growth company on such an astonishing cheap rating. Even more so when you consider that it also has a bulletproof balance sheet with nil net debt.
Although RBG is growing EPS it is at a modest rate, which the market doesn't seem especially interested in at the moment, far more interested in 25%+ growth rates. I have no doubt that at some point this will change as it always does and hopefully RBG will get rerated.
yes up 18% now, I was going to take a nibble but I think I'll wait to see if the paulypilot spike is permanent !!
K
Fallen back now around 226p.
To re-echo other comments, great write-up Paul. Many thanks.
Like ithomson1, I also think the drinks app is a fantastic idea. I could never understand why, when I was out on Friday and Saturday nights in my 20s/early 30s, so many of us had to wait so friggin' long in a queue at a bar! Surely the economics are such that it's better to staff up at the peak times to serve more drinks and incur the additional staffing costs, than the opportunity cost of not doing so and foregoing those orders by having punters bore and then give up / move on elsewhere. Given the relatively large capital requirements of fit-outs and the fixed cost of leases etc, I'd think that additional revenue should be all the more precious...
So, good staffing levels and an ordering app to spare you time away from friends, sobering up in a queue for 10+ minutes, has got to be a very good thing. Especially, as you note, the cocktails will take much longer than just pulling a pint!
I wonder if you are moving the market Paul! :-) They were up 10% 2.20pm on no news other than the presentation happening... and another 5% in last 15 minutes... perhaps a takeover is imminent, as you suggest...
I don't have nerves to chase with this volatile movement :-(
Hi andrea34l,
Yes, I was worried that my blog post might have moved the market, so queried with my broker what's been going on at RBG, and he replied;
"It's been building for the last day or so, i have been watching it quite closely. The RSP stopped reloading and then they took the book up"
I'm wondering if an institution might be buying, after the presentations yesterday?
Regards, Paul.
Thanks Paul - I use moneyam and the volumes don't look very big... but maybe it doesn't show all trades...? Anyway, great write-up! Will watch and wait...
Paul
Why are you worried about potentially moving the market? There are plenty of irresponsible tipsters out there who do just that, and you are giving a far more considered view than they are (as well as not tipping I know!). I don't think anyone can accuse you of talking up your own shares unreasonably, you're just giving a view, which is bound to be positive on the shares you hold. The fact that you have a large following and people sometimes follow your lead is a testament to your success, surely? I wouldn't be concerned, apart from anything if you follow this blog for more than 10 minutes you know that the author is a) sometimes wrong and b) the first person to admit it. Therefore if people are blindly buying because you say so then on their own head be it.
Thanks for the write up. I don't really see the differentiation of Revolution Bars (LON:RBG) so its not for me, but you certainly make a good case, good luck.
Mike
Very comprehensive write up on Revolution Bars (LON:RBG), thanks. A few thoughts occurred as I read it:
I have a decent chunk here, but I would view the key bear risks as being recession risk and simply staying relevant in an intensely competitive industry. When the next downturn arrives, as surely it must, will people really be happy to carry on paying £8-9 for a cocktail?
RBG's lack of debt and low rents means they might be able to survive a downturn where others don't, but the share price would surely suffer as the shake out runs its course.
Hi bestace,
Great points from you, as always!
I'd like to respond to a couple of your points;
I disagree about this just delaying price rises. By 2019 the company will be significantly bigger, thus ordering in larger size. Therefore this will trigger bigger discounts from the drinks suppliers. So I would imagine the new prices when they're negotiated in 2019 would be competitive due to the greater scale.
The CEO explained that this year was unusual, in that 4 new sites were bunched closely together, in H1. Therefore this caused a big cash outflow in the short term. As there are only 2 openings in H2, then this factor should hopefully reverse in H2.
So it seems to me that the RCF is in place to smooth out lumps & bumps in cashflow, rather than being structural debt, which the company is completely free of. I wouldn't particularly mind if the company took on a small amount of debt to expand a little faster.
Regards, Paul.
Good point on the price increases Paul, I hadn't considered that.
On the RCF and bunching of new site openings, I had assumed it was a deliberate strategy to target calendar Q4 openings to take advantage of Freshers week and the pre-Christmas spike in trade. They did similar last year, albeit with 3 new sites instead of this year's 4, but it's interesting to see that despite one additional new site, the net cash position actually improved from £0.95m net debt at the last half year to zero this time round.
The fact they opted for a RCF rather than a term loan would appear to support the view that it's for working capital purposes rather than for expansion. I agree a small amount of debt is OK, perhaps even desirable.
I was just kidding, Paul.
Great write-up on £RBG!
You've sent the SP up 15%!
Worth quite a few cocktails!
Best wishes,
Jane.
J D Wetherspoon (LON:JDW) have an 'order and pay' app too. Not sure how widely they have rolled it out yet though.
I went out with a small group for a drink in a Wetherspoon's pub a while ago and one colleague bought a few of us a drink using his 'order and pay' app, whilst the others bought at the bar in the usual way.
By the time our 'order and pay' drinks arrived, the others were half way through their pints!
Steve
PS Paul: Superb write up of your meeting with the Revolution Bars (LON:RBG) management. Thanks!
I guess that the problem is that he who shouts loudest gets served first and those at the bar shout loudest. If all drinks are offered this way though the problem goes away
Can't do a thumbs up on iPad so I'll say it here. Well done and thanks
"No other chain is doing this business model. Closest competitors are independents."
I haven't been to a Revolution de Cuba, but I'd have thought the Turtle Bay chain (cocktails/drinks + caribbean food) which I do frequent occasionally would be a pretty close competitor. (https://www.turtlebay.co.uk/)
I see there is a Revolution de Cuba in Nottingham, I think a night out with the missus for research is called for!
( Long Revolution Bars (LON:RBG) )
Great write up Paul! Thanks for giving us plebs insight into institution only meetings with management :-) I have a largish holding already bought in tranches when you first highlighted Revolution Bars (LON:RBG) last year. My own research was very positive and I really like the business model, product and target demographic, so it's great to hear the CEO is on the ball too. It's a great play on the changing nature of the UK high street too. I will probably buy more at some point because (as we know) the best investment ideas are normally already in your portfolio!
The StockRank is OK, but not spectacular;
I love the StockRank system but sometimes the combination of backward looking and forward looking elements miss really good opportunities where the fundamentals have quite clearly changed for the better. This was recently the case with Amino Technologies (LON:AMO). It's probably just me, but as essentially a value investor the overall rank seems slightly too biased to Momentum. If you look back at some of the big winners from last year like Avesco and Lavendon, I guarantee the best time to buy from a value perspective was when the SR was less than 80 when the value was glaringly obvious - and I don't just say that with hindsight!
All the best, Si
To be fair Avesco and Lavenden were both subject to takeover bids. There were plenty of of other shares that did well which have low Value ratings, just look at the high flyers screen. A few I was lucky enough to own were Boohoo.Com (LON:BOO), Burford Capital (LON:BUR), Next Fifteen Communications (LON:NFC), Tristel (LON:TSTL) none of these have high VR. Also quite a few others such as £G4M Purplebricks (LON:PURP) Fevertree Drinks (LON:FEVR). I used to be a value investor but I think other strategies are working better at the moment. I think Stockopedia is slow to pick up on changes within a company.
I think you maybe right by the time some of those reach the 90s its too late, I used to hold Inland Homes (LON:INL), I sold when the SR went up to 90, since then the share price has fallen about 30%, SR were fooled by the extended financial year to include a large sale, that really should have been in the next years figures. Sometimes knowing a bit about the companies can help that's why I don't usually just rely on the SR ratings, I also read Paul's reports. One problem I have with SR is debt this does not seem to be taken into account enough, often high VR are saddled with debt, KSK Power Ventur (LON:KSK) would be one example. OK this is easy to see and but is something that people should be aware of if doing selections based on SR alone.
To be fair Avesco and Lavendon were both subject to takeover bids.
Yes, but only because they were undervalued! If the stock market doesn't value good companies properly and re-rate the stock price accordingly, they should get taken over, and this was especially the case post June last year with weaker sterling. As a value investor these kind of pricing anomalies are exactly what I'm looking for. The SR is not always going to highlight that combination of conditions.
I think you maybe right by the time some of those reach the 90s its too late
I can only talk about my own experience but when I look at the 90+ SR stocks in my portfolio my overriding thought is to sell or top slice, rather than buy more. I suspect we have been in a market where a momentum approach has done very well for several years now, and I have been running my winners very hard to profit from that, but I don't expect that result to last forever.
All the best, Si
Hi Paul, Will you be covering Indigovision (IND) today?
Hi jaykaytee,
Hi Paul, Will you be covering Indigovision (IND) today?
Yes. I'm running behind schedule today, due to a hangover.
Regards, Paul.
" due to a hangover."
True devotion to duty, Paul!
Hi Jane,
Well, after meeting Revolution Bars yesterday, and talking about cocktails, my broker & I had a bit of a thirst afterwards! I wanted to go to the nearest Rev Bar, but it was about 15 minutes walk away. So instead we had a few pints at that restaurant/bar where they film TV's "First Dates" programme, in Paternoster Square.
I was so disappointed that Fred, and the nice barman, were not on duty! I asked if they were real staff, or actors. I was told that they are genuine restaurant staff, but they actually work at posh places in Mayfair in real life, and are brought in especially when the TV cameras are filming First Dates.
Then I walked to my club in Shoreditch, for some cocktails. I forget who it was that quipped - Cocktails are like breasts. One isn't enough, and three is too many!
Anyway, I had 4 or 5, hence the hangover today. I don't normally drink on school nights these days. So apologies for the sluggish service today.
Regards, Paul.
Great work on uncovering Revolution Bars (LON:RBG), Paul. I think that the most exciting bit about the above is the possibility to buy drinks using an app whilst you're at the table, surely something like this is going to become standard. Cocktails take about 2-3 mins to make, I reckon that most people would rather wait at the table. If that's not the case then I just have to wonder why people aren't going into the kitchen and watching the chef whilst he makes their food every time they order something to eat. If that method of ordering drinks comes in then that might eventually become standard for a lot of other restaurants and bars, if it hasn't already.
The only thing they'd have to worry about there is having enough table space when it's busy. Saying that, it's still going to drastically reduce the queues at the bar.
Brilliant write up . Thanks.
Ref RBG
Per the company
"New sites - are over-staffed to begin with, to ensure high customer service. Then efficiencies can be achieved once everyone is trained & experienced."
Nice to hear this - simple ideas are the best sometimes and they probably only get one chance to impress or annoy a lot of bods soon after opening even if its to be expected a little that if you go week one of a new outlet things may not be 100% up to speed.