
Good morning. President Trump claimed on Tuesday that no talks were ongoing with Iran, leaving tensions high in the region and no clear picture on any plan for the Strait of Hormuz. Two Chinese oil tankers are said to have u-turned in the Strait, presumably due to a lack of clarity on their safe passage.
The UAE has suspended commercial ties with Iran after the latter reportedly fired two missiles at the UAE.
Concerns are also growing that the conflict could escalate into Europe. The FT has an exclusive claiming Iran has considered striking US targets in Europe if Trump continues to escalate the conflict, citing “people close to the [Iranian] regime”.
Markets appear to remain relatively relaxed about the situation. Oil prices continue to hover around $90 and the S&P 500 is expected to open within a whisker of its all-time high.
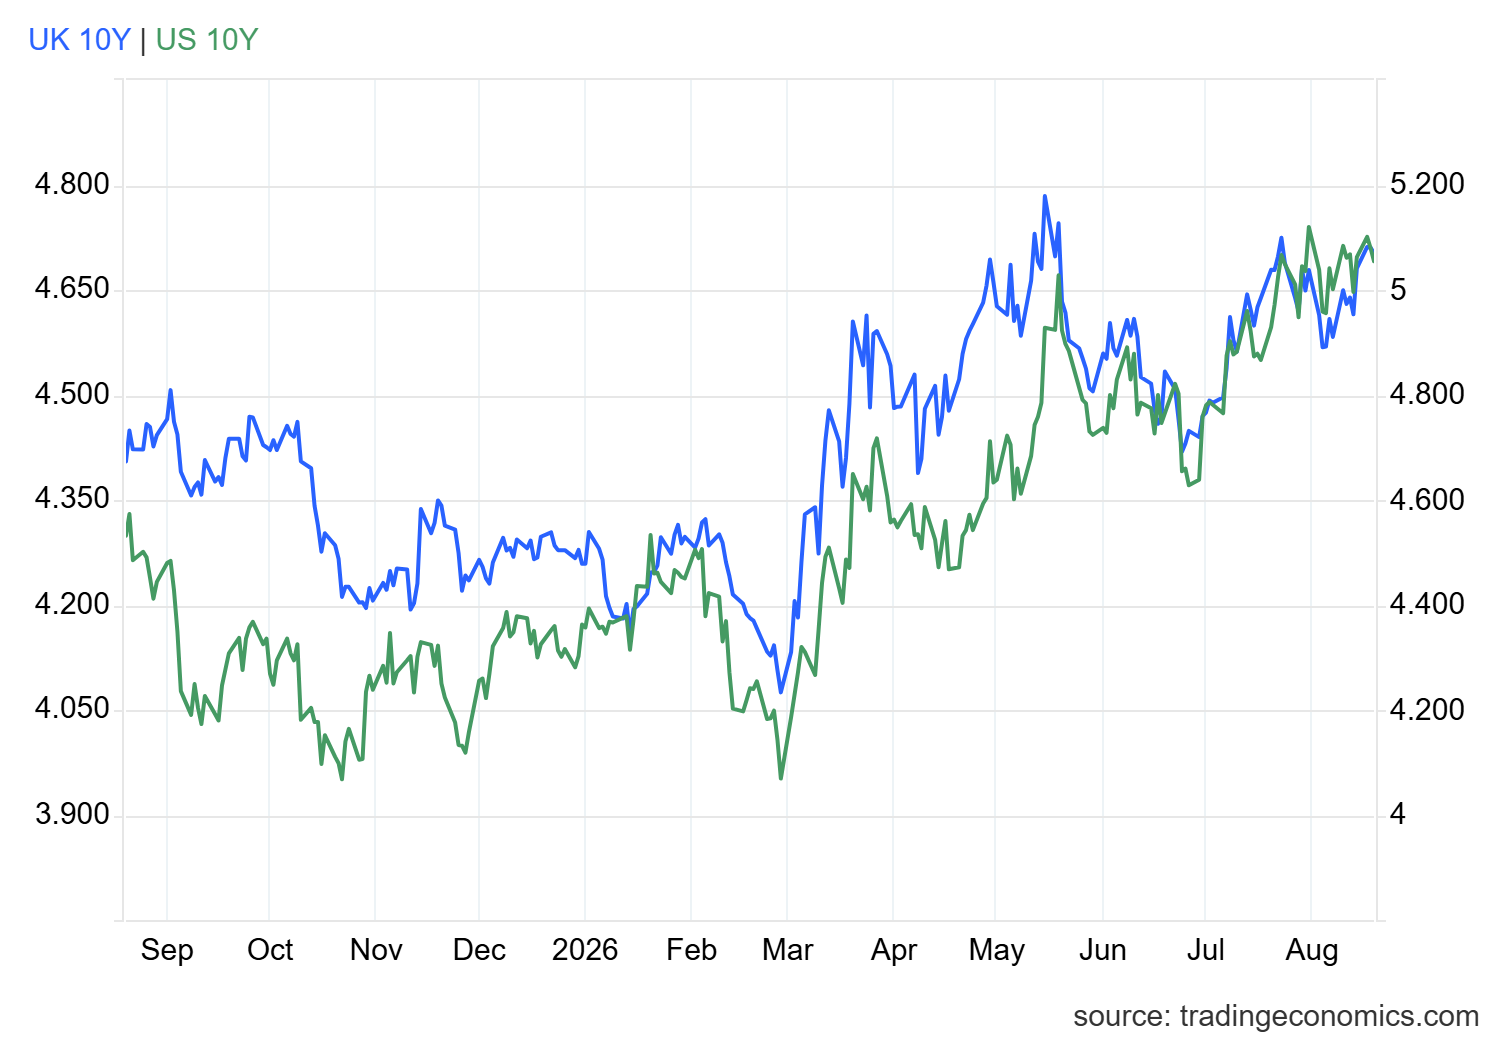
A more sober appraisal of the situation can perhaps be found in the bond market – the yields on 10-year US and UK government debt have risen this week and remain close to 5%:
Overnight market movements:
The FTSE is down 0.2% at 10,709
S&P 500 is down 0.2% at 7,680
Brent crude is up 1.0% at $90.60/bbl
Gold is flat at $4,338/oz
Bitcoin is down 0.8% at $64,156
Ed Sheldon joins me (Roland) today. It's a quiet day for news, so we're happy to take requests for any backlog items.
That's all we have time for today. I hope to see some of you at tonight's webinar, which starts at 5pm.
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Ithaca Energy (LON:ITH) (£4.2bn | SR89) | H1 production +3% to 128 kboe/d, with “record” Q2 production of 131 kboe/d. Pre-tax profit -4% to $494m with net cash flow from operating activities -5% to $954.6m. Interim dividend of $255m declared today. Outlook: production guidance unchanged, upgraded dividend guidance to $500-530m for FY26 (previously $470-530m). | ||
International Public Partnerships (LON:INPP) (£2.5bn | SR90) | Comprising 15 schools in London which have been sold to a pension investor for £58m, “a premium” to the last published valuation. | ||
Oxford Nanopore Technologies (LON:ONT) (£1.2bn | SR30) | Revenue +10.5% to £116.7m with the net loss for the period reduced to £(48.0)m. Outlook: FY26 guidance unchanged for revenue growth of 16-20%, with costs now expected to be flat or slightly lower (prev. +0-5%). No change to FY27 and FY28 guidance for adj EBITDA breakeven in FY27 and positive free cash flow in FY28. | ||
Trainline (LON:TRN) (£850m | SR94) | Company notes CMA announcement regarding the opening of an investigation into the “presentation of certain UK fees through the booking flow at Trainline”. The company says it has already engaged with the CMA and is “taking steps to enhance the presentation of certain fees”. | AMBER/GREEN = (Roland) The CMA is investigating Trainline for drip pricing – adding mandatory fees later in the booking process rather than including them upfront. My guess is that these fees aren’t likely to deter too many travellers from booking due to the superior convenience and service available from Trainline’s service. We’ve already seen some examples of the company coming under regulatory and competitive pressure over the last year, but positive operating leverage from the group’s growing scale has offset this, supporting increased profit expectations. With a forward P/E now under 10x, I am going to take a chance and leave my previous view unchanged today. | |
Empire Metals (LON:EEE) (£348m | SR23) | Upgraded MRE of 8.16 billion tonnes at 4.3% TiO2 (titanium) for 349 million tonnes of contained TiO2, across the Thomas and Cosgrove deposits. | ||
| James Latham (LON:LTHM) (£210m | SR93) | AGM Statement | Year-to-date revenue +9.8% with volumes +5.6%. Supplier price increases have "levelled out", availability is good and net profit for the year to date (April-July) is in line with expectations. | |
Scancell Holdings (LON:SCLP) (£115m | SR10) | iSCIB1+ MHRA CTA Approval for Ph3 trial | Phase 3 registrational study of iSCIB1+ in advanced melanoma to enrol 550 patients across 90 global sites. The authorization from the UK Medicines and Healthcare Products Regulatory Agency (MHRA) approval follows the IND clearance from the U.S. Food and Drug Administration (FDA). | |
Amcomri (LON:AMCO) (£91m | SR56) | H1 trading in line with expectations, with revenue +33% to £42.4m with adj EBITDA +9% to £4.7m. H1 26 net profit of £7.3m including the sale of Premier Limpet, with net debt reduced to £2.9m. | AMBER/RED = (Roland) [no section below] Today’s update appears to be in line, but only as far as H1 trading is concerned. There’s no comment on the outlook for the full year, which is perhaps a question mark. The combination of a recent disposal and a recent acquisition could mean earnings visibility is weaker than we might like. I also note the co-founders and two other shareholders have recently sold £10m of stock – the first disposal since the 2024 IPO. At first glance the stock looks quite fully priced to me relative to 2026 expectations, with a P/E of 29. Perhaps the wildcard that could change the situation is if the 79% jump in earnings forecast for FY27 is delivered. I don’t know how confident we can be of that at this stage and I note that the MomentumRank has fallen following a cut to EPS forecasts in July. More broadly, the StockRank has also fallen sharply. Without a more in-depth review, I think it’s prudent for me to leave Mark’s previous moderately cautious view unchanged today. | |
Ultimate Products (LON:ULTP) (£48m | SR98) | Revenue down 3.5% to £144.9m. Sales of UP proprietary brands up 5.3% to £128.4m. Adjusted EBITDA was £10.0m. Net bank debt of £8.6m (FY25: £14.1m), representing a net bank debt / adjusted EBITDA ratio of 0.9x. The Board currently expects FY27 trading to be similar to FY26. | AMBER = (Ed S) | |
iFOREX Financial Trading Holdings (LON:IFRX) (£41m | SR28) | Trading has been considerably weaker than anticipated, with August unusually subdued. Trading income for July 2026 was only c.$720k compared to c.$3.1 million in July 2025. The Board now expects Adjusted EBITDA for FY2026 to be in the range of $0.5 million to $2.5 million. | BLACK | |
Angling Direct (LON:ANG) (£33m | SR84) | Revenue up 5.1% to £56.4m. UK sales up 6.9%, European sales down 30.4%. £14.5m cash at period end. Additional scope for buybacks. Confident in achieving full-year consensus market expectations. | AMBER/GREEN = (Ed S) | |
| Goldplat (LON:GDP) (£30m | SR95) | Q4 Operating Results, Dividend Declaration & CFO | Achieved a Q4 pre-tax profit excluding central costs of £3.4m (Q4 25: £766k). Notes a 16% decline in the gold price in Q4 (March-June) and reports a current cash balance of “around” £6m. Has appointed a non-board CFO. | |
Riverstone Energy (LON:RSE) (£28m | SR76) | NAV per share of $16.04 (£12.12), representing a decrease in USD of 0.2% and an increase in GBP of 1.5% vs 31 December 2025. The company is advancing its Managed Wind-Down. |
Roland's Section
Trainline (LON:TRN)
Down 15% at 206p (£852m) - Response to CMA Announcement - Roland - AMBER/GREEN =
Shares in the UK’s leading rail ticket aggregator have fallen sharply this morning following news that the Competition and Markets Authority – the UK’s competition regulator – is investigating the firm for compliance with consumer protection law.
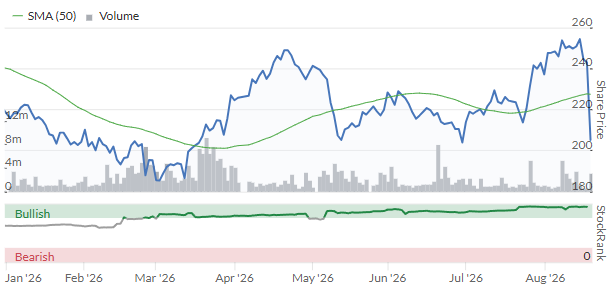
You can read the CMA announcement here, but here’s the key point:
The CMA is investigating Trainline over its presentation of mandatory fees, specifically whether these fees are included in the total price the consumer sees at the beginning of the process for purchasing train and coach tickets.
This is an initial investigation and at this stage, it should not be assumed that Trainline has broken any rules.
However, if I’ve understood correctly, the suggestion seems to be that mandatory fees – which should be included up front – may have been added later in the buying process or otherwise obscured, making it harder for consumers to see the full cost of tickets.
This technique is known as drip pricing.
In a press release today, the CMA says:
For train travel, the CMA observed transactions with fees ranging from £0.59 to £2.79. For coach bookings, it was a £1.50 booking fee. Both are costs that can add up for frequent travellers.
The CMA has also opened investigations into Virgin Atlantic and RED Driving School on similar grounds.
Trainline is “engaged with the CMA”
In Trainline’s own statement, the company says that it’s already making changes following work with the CMA:
Trainline has proactively engaged with the CMA over several months and is taking steps to enhance the presentation of certain fees. We will continue to work constructively with the CMA to ensure our customer experience remains both transparent and compliant.
Roland’s view
Trainline says it’s “committed to delivering genuine value” to customers and flags up its 4.9 star app rating (which appears to be in the Apple App store). The company has a 4.1 star rating on Trustpilot from 152k reviews.
Personally, I would say that the star rating relates to Trainline’s broader service (which I think is good) and the fact that it doesn’t have much serious competition when it comes to helping consumers navigate the crazy complexity of UK rail ticketing.
With regard to fees, I would guess that many consumers are fairly inured to having additional fees added onto travel and other online ticket bookings. In addition, some may be happy to pay a small additional fee (versus booking directly with a train operator) for the convenience the Trainline service provides.
However, as investors we need to consider the potential impact (if any) on Trainline’s trading results.
Would improved disclosure of these fees have any impact on the value or volume of Trainline’s sales? I can’t be sure, but I suspect the impact would not be that great, at least not in the core rail business.
Perhaps a more serious risk is that the fees will be reduced. In a business such as this, millions of small fees can have a powerful cumulative impact on profit margins; the underlying transaction costs are often minimal.
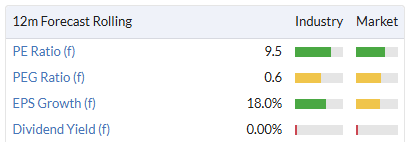
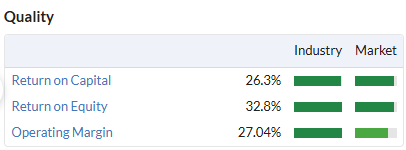
Can I stay positive? Trainline enjoys high quality metrics and looks relatively cheap – even before today’s fall, the shares were trading on a forward P/E of 10.
We haven’t looked at the business since November 2025, when I took a moderately positive AMBER/GREEN view.
At the time, I resisted the temptation to go fully positive due to regulatory risks and the possibility that new competitors might enter the market. After all, we’ve already seen recent examples of the kind of headwinds that could affect the business.
Trainline’s commission rate on UK rail tickets was cut by 0.5% last year.
The company also warned that Transport for London’s expanding contactless payment network could eat into Trainline’s own sales.
Despite the cut to commissions, positive operating leverage from higher ticket volumes supported a healthy increase in both profits and margins last year:
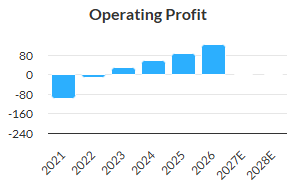
On balance, I think the likelihood of a full-service competitor appearing is relatively low, due to the embedded knowledge, complexity and market share of Trainline’s offering. I’m also encouraged by its growing scale and increased reach into adjacent markets.
My main concern is that profitability could gradually be eroded by various factors outside its control.
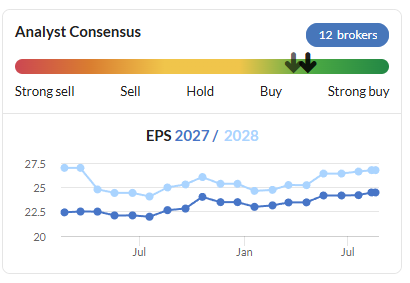
However, with a forward P/E of less than 10x and improving profit expectations, I think some downside is already priced in. I’m going to take a chance today and maintain my previous AMBER/GREEN view.
Ed S's Section
Ultimate Products (LON:ULTP)
Down 3% to 54p (£48m) - Pre-Close Trading Update - Ed S - AMBER =
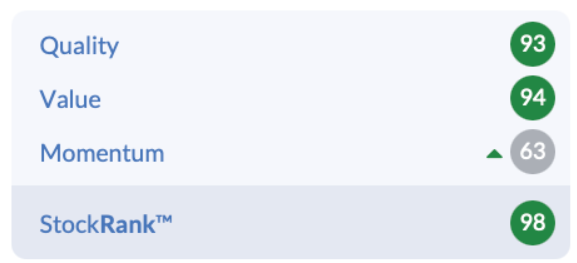
Homeware brands company Ultimate Products, which owns brands such as Salter and Beldray, has today posted a Pre-Close Trading Update for the financial year ended 31 July. The Stockopedia system really likes this stock – it currently has a StockRank of 98 and a ‘Super Stock’ rating – so let’s take a look at what’s going on.
Today’s numbers:
Unaudited group revenue of £144.9m (FY25: £150.1m), down 3.5%, reflecting subdued consumer demand for general merchandise and the planned reduction in non-core third-party clearance sales.
Sales of UP proprietary brands up 5.3% to £128.4m, as the group continued its strategic focus on building the equity of its proprietary brands.
Unaudited adjusted EBITDA was £10.0m.
Gross Margin of 22.6% (FY25: 23.2%).
Operating costs remained broadly stable at £22.8m (FY25: £22.3m) and included £760,000 of restructuring costs related to the transformation of the group's commercial function.
Net bank debt of £8.6m (FY25: £14.1m), representing a net bank debt / adjusted EBITDA ratio of 0.9x (FY25: 1.1x).
It’s worth noting that the company has provided FY26 market expectations in the update:
Revenue: £144.8m
Adjusted EBITDA: £9.9m
So, it managed to beat expectations marginally.
Current trading and outlook
Group H2 revenue was broadly flat (down 0.3% year-on-year) – an improvement on the 5.8% decline reported in H1.
For FY27, the Board expects the current backdrop of subdued consumer demand and geopolitical uncertainty to persist. As a result, it currently expects FY27 trading to be similar to FY26.
In the longer term, the Board is confident that the ongoing investment in the group's operational capabilities and commercial function will position the group to maximise future growth opportunities.
Our primary focus during the year has been the transformation of our commercial function to drive the growth of our proprietary brands. Although the broader trading environment remains challenging, we believe the changes we are making will support our ambition to grow both market share and brand equity, allowing our key brands of Salter and Beldray to fulfil their potential.
Ed S’s view:
Starting with today’s numbers, while the headline revenue growth figure looks weak, I do see several positives. For a start, sales of UP proprietary brands were up 5.3% year on year (+5.2% in H1). Second, revenue and EBITDA were slightly ahead of expectations. Third, group H2 revenue was broadly flat so that’s a decent improvement on the 5.8% drop reported in H1.
Looking beyond the growth, the reduction in debt is also a positive. A net bank debt / adjusted EBITDA ratio of 0.9x is solid.
On the downside, gross margin has fallen slightly, from 23.2% to 22.6%. The company said this was due to the sales mix.
Meanwhile, the backdrop is clearly difficult. The company points to “subdued consumer demand for general merchandise” and says that the “broader trading environment remains challenging.”
Taking a step back, Ultimate Products is currently undergoing a strategic shift in which it is focusing heavily on its UP proprietary brands. It is operating a ‘Salter & Beldray first’ strategy – having completed major re-brands of both – and it sees long-term growth potential:
Ultimate Products sees a clear runway to grow both in the UK and overseas, with Europe the standout opportunity. Strong demand from European discounters continues to offset weaker UK trading and reinforces the view that there are significant growth opportunities within that market.
The company has also shaken up its leadership team. In May, it announced that Simon Harrison will become CEO on 26 October, taking over from Andrew Gossage (you can read more about this here).
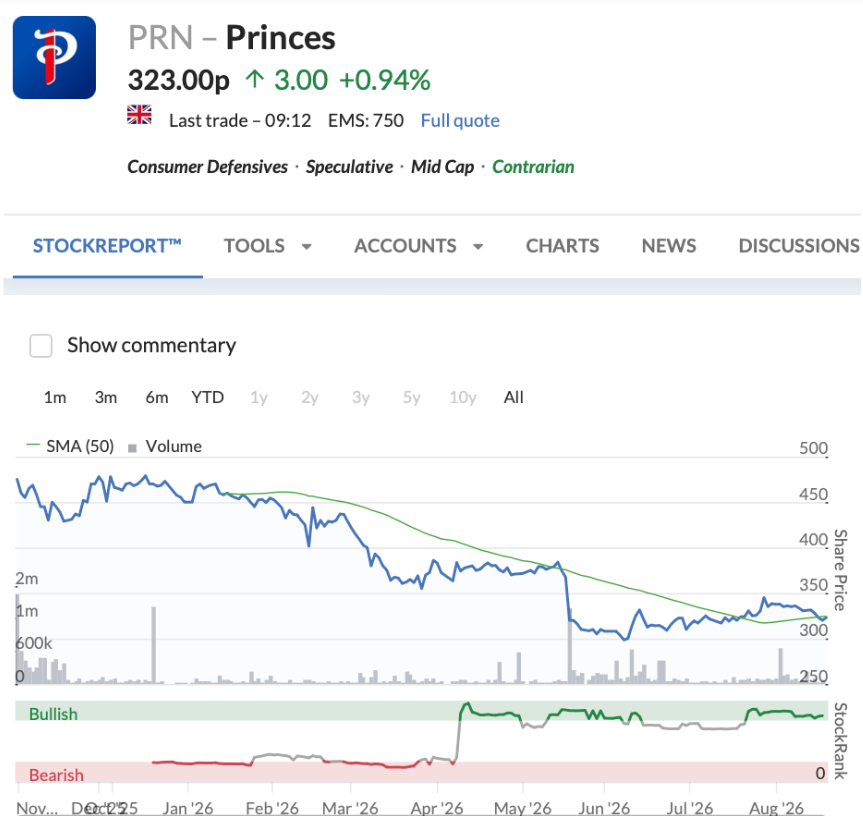
Harrison was formerly CEO of Princes Group and has more than 25 years of experience in FMCG, and the company believes that he’s the right person to take Ultimate Products forward into its next chapter. The fact that he’s joining Ultimate Products from a much larger company (Princes Group has a market cap of £785m) could suggest that he sees an opportunity.
Interestingly, when it came to light that Harrison was leaving Princes Group back in May, the PRN share price slumped. This suggests that Harrison is well regarded.
Now, there are no guarantees that Harrison will be able to boost top-line growth. Ultimate Products operate in mature markets and consumers don’t have a lot of disposable income at the moment.
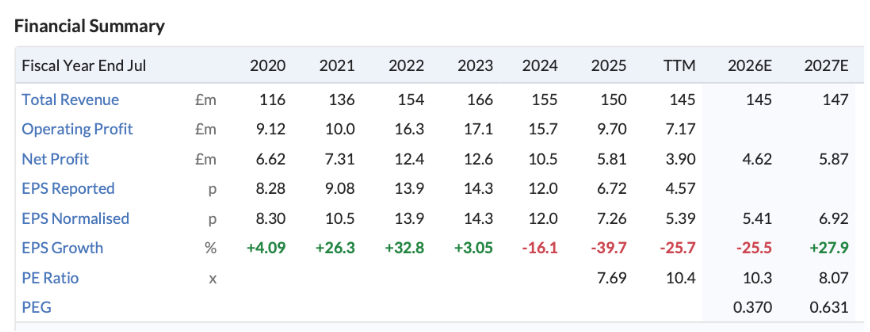
But I don’t think it would take much to see a valuation re-rating because right now, the stock looks quite cheap. The consensus EPS forecast for the financial year just ended is 5.41p, which puts the stock on a P/E ratio of around 10.
Looking beyond the valuation, there’s a decent dividend here. The consensus forecast payout for FY26 is 2.71p per share, which translates to a yield of around 5% (the current policy is to return 50% of post-tax profits to shareholders through dividends).
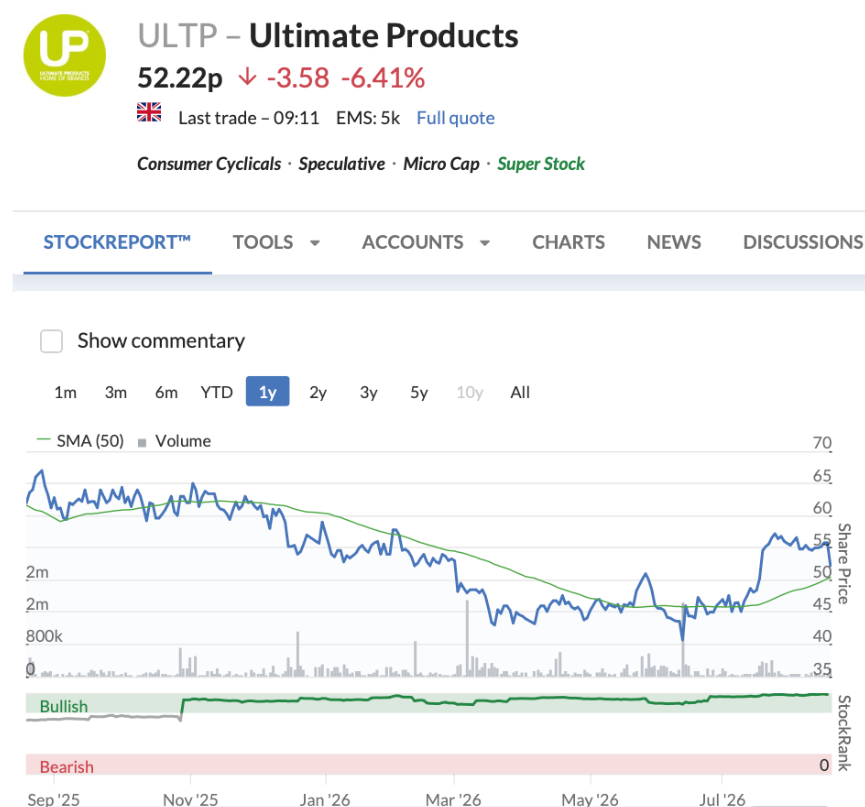
In terms of the chart, the share price has been trending up recently. The 50-day moving average might provide some support after today’s pullback.
One risk worth highlighting is earnings expectations. At present, analysts expect a 28% jump in EPS this year – that may be a little optimistic.
Overall though, I think this stock looks interesting from a value/turnaround perspective. There are risks around consumer spending but it’s relatively cheap at present, so I’m going to keep it at AMBER.
Angling Direct (LON:ANG)
Up 1% to 47.5p (£33m) - Half Year Trading Update and Notice of Results - Ed S - AMBER/GREEN =
Fishing retailer Angling Direct has provided us with a half-year trading update for the six-month period ended 31 July. Here are the key numbers:
Revenue up 5.1% to £56.4m.
UK retail store sales up 6.4% to £32.4m.
UK online sales up 7.5% to £22.1m.
Total UK sales up 6.9% to £54.6m.
UK LFL sales up 2.9%.
Total European sales down 30.4% to £1.8m.
Net cash at period end of £14.5m.
Outlook:
We remain confident in achieving our full year consensus market expectations* and are well positioned to capitalise on the attractive long-term growth opportunities across our markets as we deliver our medium-term objectives.
* Company-provided market expectations: revenue of £109 million and adjusted EBITDA of £5.7 million.
Ed S’s view:
This is a relatively solid update, in my view. UK online sales growth of 7.5% is not bad given the consumer backdrop.
European sales are no doubt a bit of a disaster. However, these only represent a small fraction of total sales.
In the update, the company says that there is additional scope for buy backs – beyond the £1.4m outstanding under its existing Buyback Programme – given its strong cash flow generation. This is a positive although I’m sure a lot of investors would love to see a dividend here.
It also notes that it is developing a pipeline of additional store and stock only acquisitions as the challenging consumer backdrop creates potential for further consolidation in the UK market. After opening three new stores in H1, it now has 60 stores in operation across England and Wales.
One other thing worth highlighting is that the company had 696k subscribers to its MyAD customer loyalty club at the end of July, versus 600k in January. This signals that its customers are engaged and that they value the retailer.
Looking at earnings forecasts here, the valuation seems very reasonable. With the consensus EPS forecast for FY27 sitting at 3.61p, the stock is currently trading on a forward-looking P/E ratio of 13.2.
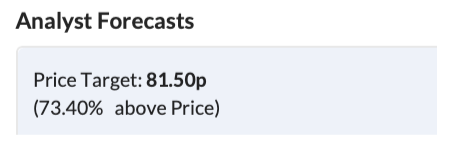
That strikes me as good value given the company’s track record, financials, and rate of growth. For what it’s worth, the average analyst price target is miles above the current share price (these targets should always be taken with a pinch of salt).
In terms of negatives, return on capital employed (ROCE) is low, especially for a company generating a large chunk of its sales online. Over the last four years, it has averaged less than 5%, which tells us that top-line growth isn't translating into value creation for shareholders.
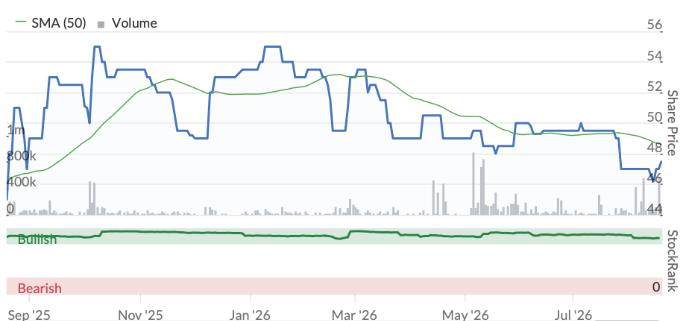
The chart also looks weak at the moment (the Stockopedia momentum rank is just 39). The share price has been trending down in 2026 and it is currently sitting below the 50-day moving average.
On balance though, I can see appeal in the stock at current levels. I’m happy to leave it at AMBER/GREEN.
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.