
Good morning all, the Iranian situation continues to escalate with more economic threats from the 47th President of the United States. Oil remains near or above $90, with the near-term October contract trading close to $92.
His threats now appear to be aimed at the likes of China and others who buy from Iran:
ANY country that allows its financial institutions, businesses, airports, or government entities to provide any type of lifeline to Iran will itself face TREMENDOUS Economic Consequences.”
The poorly-observed ceasefire between the US and Iran expired on Monday.
UK inflation is currently running at 2.9% year-on-year, according to the figures released yesterday. This reading was in line with expectations.
Personal note: many thanks to Roland for covering my spot in yesterday’s webinar, as I had to take time out to care for a family member. Much appreciated!
Overnight market movements:
The FTSE is unchanged at 10,750
S&P 500 is unchanged at 7,715
Brent crude (November) is up 0.2% at $89.85/bbl
Gold is down 0.9% at $4,485/oz
Bitcoin is up 0.5% at $69,350
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Standard Life (LON:SDLF) (£9.1bn | SR69) | Strategic partnership to expand SL’s Pension Risk Transfer business to support schemes across a broader range of sizes, including the largest and most complex defined benefit schemes. Initial capital commitment of up to £2bn. | PROFIT WARNING (AMBER/RED =) (Graham) Perhaps I’m too pessimistic, and a recovery to the profitability of prior years is on the cards. I just don’t see why that is going to happen. Once again I'm considerably more negative than the StockRank. | |
JD Sports Fashion (LON:JD.). (£4.5bn | SR96) | Q2 organic sales -1.3% (Q1: -0.1%). Q2 LFL sales of -3.1% (Q1: -2.5%). “Noting our underlying H1 sales trends and the promotional market backdrop, which may persist into H2, we now anticipate FY27 profit before tax and adjusting items of £700m to £800m (previously £750m to £850m).” | PROFIT WARNING (AMBER ↓) (Roland) Today’s cut to guidance follows a relatively weak update in May. With hindsight I should have been a little more cautious back then, although the share price remains above the level seen at that time. My impression is that JD’s problems may reflect both cost-of-living pressures and the weak performance of its key supplier, Nike, which I believe accounts for c.40% of sales. On balance I think this remains a decent business at a reasonable price, but the situation isn’t without risk and the timing of a recovery remains uncertain. I think it makes sense to cut our view to neutral today. | |
Resolute Mining (LON:RSG) (£1.42bn | SR50) | H1 profit after income tax +129% ($163m). Production (gold poured) for H1 of 104,795 oz vs. 151,460 oz in H1 2025. Group production guidance on track to be around the lower end of the 250 - 275 koz guidance range. Group AISC of $2,000 - 2,200/oz is maintained, however it is subject to change with elevated gold prices and higher fuel costs. | ||
Hays (LON:HAS) (£1.12bn | SR83) | Net fees down 8% LfL. Adjusted operating profit +3% (£48.6m). Statutory loss £54.5m after an exceptional restructuring charge. “Current trading in July and August has been in line with our expectations with no significant change to activity levels from Q4. September is the key trading month in our first quarter, and it is too early to assess trends.” | ||
Ashtead Technology Holdings (LON:AT.). (£347m | SR54) | “The Board now anticipates full year revenues to be around 5% below the current market consensus. The deferral of rental revenues, in particular, will adversely impact the revenue mix of the Group in 2026. Combined with the operating leverage in the business, this is likely to contribute to lower margins and Adjusted EBITA around 15% below the current market consensus.” Broker Zeus cuts FY26E adj EPS by 17% to 37.7p. | PROFIT WARNING (AMBER ↓) (Roland) The failure to resolve the conflict in the Middle East appears to have prompted some of Ashtead’s customers to draw a line under 2026 and start planning for 2027. Slightly more surprising to me is the news of project delays in Europe and The Americas, albeit the relative impact of these is not clear to me. While I don’t see anything fundamentally wrong with this business, it appears to be at the mercy of events outside its control – never a great situation. I think it makes sense to be neutral here in the absence of in-depth sector insight and research. | |
Capital (LON:CAPD) (£243m | SR85) | Revenue +37.6%. Operating profit +96.3% ($31.8m). “On the back of a strong H1, we are pleased to announce an increase in our 2026 Group revenue guidance to $430 - $450 million (from $410 - $440 million)... We remain confident in the Group's outlook as we mobilise into several new contracts, with robust industry demand and attractive growth opportunities present across all divisions.” Panmure Liberum cuts FY26E adj EPS by 8.2% to 14.1c | AMBER/GREEN = (Roland) Today’s results look solid to me and suggest continued operational progress across all Capital’s main operating segments. This is a specialist business run by a founder-manager with significant skin in the game. While there will be some lumpiness to results at times, I don’t see any reason to change our previous moderately-positive view today, despite a slight (tax-related) cut to broker earnings forecasts. | |
Ab Dynamics (LON:ABDP) (£179m | SR30) | eMpulse designs and supplies advanced servoelectric test systems to the automotive industry for applications in noise, vibration and harshness, structural and durability testing. Initial consideration is expected to be c.£9.5m, with contingent consideration of up to $15m. | ||
Castings (LON:CGS) (£131m | SR95) | Orders and forward schedules are improving from both heavy truck customers and new business, largely associated with wind energy. Performance at the William Lee site has been affected by operational issues that have persisted from the power supply issue earlier this year. Outlook: management expect full year result to be in line with expectations. | AMBER/GREEN ↑ (Roland - I hold) [no section below] I’m gaining confidence in the turnaround here. June’s guidance for a 5%-10% increase in forward demand appears to remain unchanged and was translated into a modest uplift in broker forecasts. These remain unchanged today despite some lingering impact (now resolved) from an earlier power supply issue. It’s also encouraging to see management confirm that increased demand is being driven both by a recovery in the heavy truck sector and continued growth in wind energy. Diversifying the business to reduce cyclicality is a medium-term goal that I hope will also improve through-cycle returns on capital – a weakness of this business. With a rock-solid balance sheet, unchanged forecasts and improving outlook, I think it’s fair to mirror the StockRanks and turn more positive, so I’m moving our view up by one notch today. | |
IG Design (LON:IGR) (£96m | SR97) | CFO Rohan Cummings will step down with effect from 31 August 2026. He’ll be replaced by Ari Bensoussan from 1 September 2026. Bensoussan has 30 years of experience, including almost 25 years at Nestlé. | ||
Shield Therapeutics (LON:STX) (£47m | SR13) | H1 revenue +42% to $30.4m with net loss reduced to $(2.3)m (H1 25: $(9.5)m). Cash of $8.3m. ACCRUFeR prescriptions +21% to c.102,000 with average net selling price of $199 (H1 25: $214). Outlook: group remains on track for operating profitability in 2026. | ||
Atome (LON:ATOM) (£28m | SRn/a) | Entered into an agreement with a development bank to provide support for a feasibility study on the implementation of ATOME’s projected 300MWp solar PV project in Villeta, Paraguay. | Shares are currently suspended. | |
Rome Resources (LON:RMR) (£24m | SR23) | “Two new mineralised zones, MINZ8 and MINZ9, identified at Kalayi, extending the interpreted mineralised system and providing priority targets for follow-up drilling and future resource growth.” | ||
Robinson (LON:RBN) (£22m | SR88) | “Very challenging trading environment”. H1 revenue +5% to £28.9m with lower gross margin and underlying operating profit -55% to £0.9m. FY26 Outlook: now expects underlying operating profit of £2.2-2.6m (prev. £3.4m). | PROFIT WARNING (AMBER/RED ↓) (Graham) I was previously happy to take a neutral stance as this company was at least profitable and looked set to eliminate its net debt. Those positives are still likely to be true, but on the back of this profit warning I am going to take us back down to AMBER/RED. There are potential attractions for patient, “deep value” investors who are willing to wait it out until 2028-2029. But for me today, the company’s apparent lack of pricing power, along with the near-term headwinds it faces, demand a cautious stance. This is a rare case where I’m in sharp disagreement with the Stockopedia ranking, which calls it a Super Stock. | |
Potter & Moore (LON:PAM) (£16m | SR72) | Q1 trading was “challenging” and year-to-date revenue is behind the same period last year, but broadly in line with expectations. Gross margin is also below last year. Management continues to expect an H2 weighting to results. | ||
Fulcrum Metals (LON:FMET) (£12m | SR9) | Airborne geophysical programme to commence at Charlot-Neely Lake Project, to be fully funded by option partner Terra North, under its C$3.25m minimum spend commitment. | ||
Mila Resources (LON:MILA) (£10m | SR24) | Basilica Prospect:Three dipole-dipole IP lines have been surveyed and modelled across the Basilica and Jazza targets all confirmed to good data quality. Childs Prospect: Porphyry-like characteristics demonstrated. |
Graham's Section
Robinson (LON:RBN)
Down 8% at 122p (£20m) - Interim Results - Graham - PROFIT WARNING (AMBER/RED ↓)
Robinson plc ("Robinson", the "Company", or the "Group"; stock code: RBN), the custom manufacturer of plastic and paperboard packaging based in Chesterfield, announces its interim results for the six months ended 30 June 2026.
This is a “whoops” moment for me, as I upgraded our stance on Robinson to neutral in May.
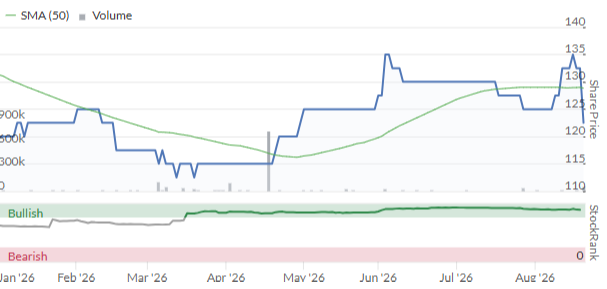
Although in hindsight, maybe neutral wasn’t such a terrible call? Today’s profit warning takes the share price back to where it was in May:
These interim results aren’t too great:
Revenue +5% to £28.9m with sales volumes up 3%.
Gross margin falls from 22% to 20%
Underlying operating profit halves from £2m to £0.9m.
Net debt increases to £6.4m (from £5.4m) despite the company making property sales for £1.5m.
I’m expecting a lot more cash flow from surplus property sales, and this is a big part of the reason why I upgraded our stance back in May.
Before going any further, let’s make sure the property situation is still encouraging.
From the Chairman’s statement, we have the following information.
The company sold an option for a property; if it’s exercised that would bring in £2.85m, payable in instalments.
Sale agreed on two other properties for £2.2m.
So that’s £5m that could be on the way before too long, which would be enough to eliminate most debt if the business itself wasn’t burning cash.
Let’s now turn to the business itself.
Unfortunately today we have a profit warning, with the last one having been in December 2025.
The Chairman’s statement (emphasis added):
"The results for the first half of 2026 reflect a very challenging trading environment. Increased competition in our end markets contributed to the loss of some business, while operational challenges, together with uncertainty and input-cost inflation arising from the ongoing crisis in the Middle East, also affected performance…
Several pressures affecting the first half are expected to continue for longer than previously anticipated. The conflict in the Middle East has kept polymer, energy and freight costs elevated, and constrained material availability, while recovery through customer pricing remains uncertain.”
New guidance: 2026 underlying profit of between £2.2m and £2.6m, although reported profit will benefit from property disposals.
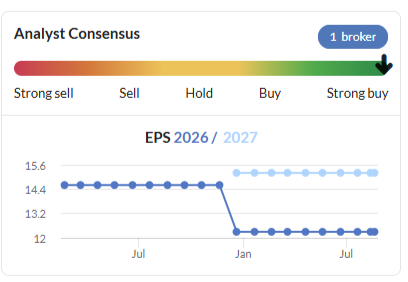
Estimates: Cavendish have cut their 2026 adj. EPS forecast by 42% (from 12.3p to 7.1p) and their 2027 adj. EPS forecast by 27% (from 15.2p to 11.1p).
At today’s share price, that gives a P/E multiple for 2026 of 17x and for 2027 of 11x.
In H1, the company was hit by two fundamental issues.
1. Lower gross margins (20% vs. 22%)
So is this permanent or temporary? The reasons given sound mostly temporary, e.g. “additional material costs… to secure availability during the Middle East crisis”.
However, even though the reasons given sound temporary I wouldn’t have all that much confidence in a significant recovery in margins.
The company has been honest enough to admit that increased competition is a factor, and that it’s having trouble passing on input price increases to its customers.
While that honesty is to be applauded, it’s also a serious problem for the investment case here, at least from my point of view. Pricing power and competitive positioning are key to how much I’m willing to pay for a stock. So the way I’m interpreting this, the lower gross margin is not just a consequence of the Middle East crisis, but also reflects the very competitive nature of the packaging industry.
Cavendish also do not forecast a recovery in the gross profit margin, at least not this year or next year.
2. Higher operating costs (up 18% to £4.9m)
Compounding the problem of lower gross profits are higher operating costs, which have grown far quicker than general inflation rates.
The company’s explanation emphasises “higher distribution and external storage costs” and “net investment in additional capability to support the new functionally led structure and refreshed group strategy”. Perhaps some of the increased costs might reverse? I'm not sure.
Graham’s view
Packaging is the type of industry where I’d be very selective, and I’d definitely not want to overpay for an average business.
I was previously happy to take a neutral stance as the company was at least profitable and looked set to eliminate net debt.
Those positives are still likely to be true, but on the back of this profit warning I am going to take us back down to AMBER/RED.
I’d also like to point out that the company doesn’t seem to offer much value in the short-term, even if it hits new forecasts for 2026/2027. Continued recovery through 2028-2029 will be needed.
On the other hand, the balance sheet does have a tangible book value of over £24m, higher than the current market cap.
So there are potential attractions for patient, “deep value” investors who are willing to wait it out until 2028-2029. But for me today, the company’s apparent lack of pricing power, along with the near-term headwinds it faces, demand a cautious stance.
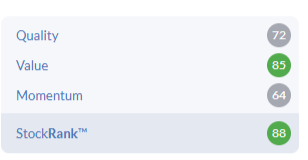
This is a rare case where I’m in sharp disagreement with the Stockopedia ranking, which calls it a Super Stock:
Hays (LON:HAS)
Down 7% at 66.7p (£1.05bn) - Graham - AMBER/RED =
In what feels like a trend among larger companies, Hays has elected not to format its results for the RNS announcement. The only way to read this is to download the PDF.
These results show the continued decline in recruitment activity:
Net fees down 8% LfL
Adjusted operating profit up 3% LfL to £48.6m
Statutory loss £54.5m after an exceptional restructuring charge.
They introduce a new “Momentum strategy”.
It sounds like retreating into a less ambitious but perhaps more logical structure:
A focused growth strategy delivered through market leadership in a narrower country portfolio and six global specialisms, placing high-skilled roles in target industries.
The strategy includes “c. £50 million per annum structural cost savings in FY27”, a meaningful figure that exceeds the entire adjusted operating profit figure for FY26. But it sounds like this will also mean a substantially smaller size for the group as a whole.
Current trading/outlook: it sounds like there is very little real visibility at this stage.
Current trading in July and August has been in line with our expectations with no significant change to activity levels from Q4. September is the key trading month in our first quarter, and it is too early to assess trends.
CEO comment trumpets the expected benefits of the new strategy. Lots of corporate jargon here I’m afraid:
Our new Momentum strategy addresses the future hiring needs of our clients, sharpens our focus and captures the benefits associated with market leadership. As we leverage our sources of competitive advantage, we will drive higher market share, further material productivity growth and a significant reduction in overhead costs generating increased profitability, client and candidate satisfaction, longterm growth and improved returns
The strategy blurb explains how the company is going to focus on finding the highest-quality candidates for its clients: candidates who have not just the technical skills needed, but also the interpersonal skills, “including values and behavioural alignment”.
It reads well but I don’t think there’s anything special here - surely Hays has always attempted to do this?
The overriding picture here is that the company is pulling back to focus on six specialisms in 16 countries.
The specialisms are Technology, Finance, Engineering, Construction/Property, Life Sciences and HR.
Geographically, the company will continue to pull back from countries which aren’t profitable enough. There’s a surprisingly long list of these, including countries in Europe, Asia and South America.
Graham’s view
I don’t think it’s a negative that Hays is retreating.
On the contrary, I think it’s logical. When business is doing badly, and there is no realistic prospect for improvement, then it makes sense.
We’ve discussed many times in this report how the recruitment industry has been under pressure. Hays is a great example of this, and the fact that it’s simply going to withdraw from many countries and collapse the industries it serves only goes to prove the point.
These shares have performed well in recent weeks:
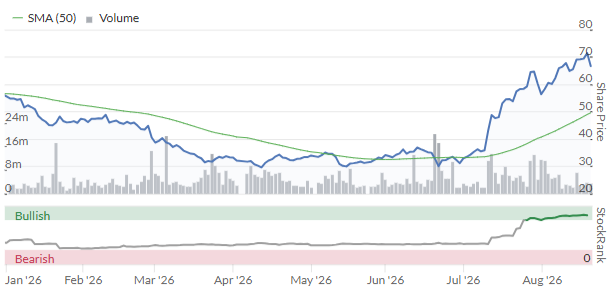
Roland was AMBER/RED on it last year at a market cap of £920m and I’m inclined to stay AMBER/RED on it today.
At the end of the day, this is a very difficult industry these days. Even the best-in-class recruiters are struggling badly - with the exception of some blue-collar or highly specialist players. I'm still inclined to believe that there are structural factors at play.
And when it comes to Hays in particular, I don’t see much to attract investors at the current valuation.
As far as its financial strength is concerned, it has slashed its full-year dividends by two-thirds, from 1.24p to 0.44p.
The balance sheet looks like it’s still ok, with £112m of year-end cash vs. bank overdrafts of £27m and bank loans of £65m (total bank borrowings: £92m). But it was healthier last year, when year-end cash was £169m. And remember that monthly cash flow can be volatile in this type of business, so the year-end figure doesn't tell us the whole story.
The company says “we removed our £100 million cash buffer to provide greater flexibility through the cycle as our cash position rebuilds over the longer term”. I read this to mean that the company’s poor performance has eaten into its cash buffer.
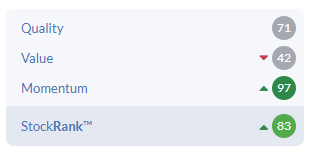
Perhaps I’m too pessimistic, and a recovery to the profitability of prior years is on the cards. I just don’t see why that is going to happen.
Once again I'm considerably more negative than the StockRank:
Roland's Section
JD Sports Fashion (LON:JD.).
Down 15% at 79p (£4.0bn) - Q2 2026/27 Trading Statement - Roland - PROFIT WARNING
Sales at footwear retailer JD Sports Fashion are inevitably exposed to consumer spending. They are also linked to demand for products made by Leverage Shares 2x Nike Etp (LON:NKE2), which I believe generate around 40% of the retailer’s revenue.
Unfortunately, Nike’s revenue has fallen by 10% since 2024 and is expected to fall again this year. Consumer spending is also under pressure in many of the markets where JD operates.
My impression is that both of these factors lie behind today’s profit warning from JD, which has seen the company cut its adjusted pre-tax profit guidance by 6% to a range of £700-800m (previously £750m to £850m).
Q2 summary: “footwear remained soft”
Headline sales figures tell us that sales trends worsened during the second quarter. This is said to reflect weaker demand for footwear “given consumer pressures”.
Q2 sales -1.3% (Q1: -0.1%)
Q2 like-for-like sales: -3.1% (Q1 LFL: -2.5%)
The company also appears to give a nod towards turnaround efforts at Nike (and others?), saying that “ongoing product cycle evolution across key brand partners” also contributed to weaker footwear sales.
Apparel and accessories performed more strongly, but these are secondary to the group’s main footwear focus.
None of this seems very encouraging to me, given that the period in question included the World Cup and the start of the summer season.
Looking across the company’s markets, only Asia Pacific managed to generate a positive performance in H1:
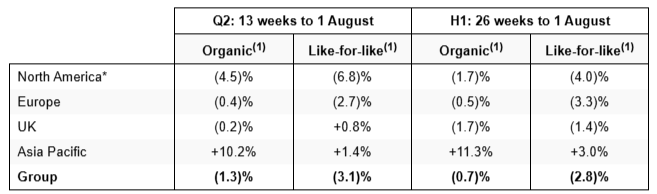
Unfortunately the Asia Pacific region only generated 5% of the group’s sales during the first half of the year.
The bulk of trade comes from North America (35%), Europe (34%) and the UK (26%). These regions are also where the company’s problems appear to lie:
North America: organic sales fell by 4.5% (-6.8% LFL)
Overall sales performance appears to have been held back by Finish Line stores. Excluding these, organic sales only fell by 1.0%. JD is in the process of converting Finish Line stores to the JD fascia and says this process is on track, with 145 stores remaining.
More broadly, the company says sales were down due to soft consumer demand and “deferred July “back-to-school” demand”. JD-branded stores are said to have outperformed regional fascias. “Promotional intensity” (i.e. discounting) is said to be higher than normal, with footwear sales also held back by some timing-related effects due to product launch schedules.
Europe: organic sales fell by 0.4% (-2.7% LFL)
Sales were held back by consumer weakness and promotional market conditions.
The group’s Sporting Goods businesses in Southern Europe were more resilient, but JD cites the same issues with end-of-cycle product lines and weaker footwear demand as in North America.
United Kingdom: organic sales -0.2% (+0.8% LFL)
The UK was relatively stronger than Europe and North America, with good demand for apparel and accessories helping to offset the same headwinds in footwear seen elsewhere.
Football replica kit is singled at as a positive feature – unsurprisingly – but interestingly the company says online business was affected by promotional market conditions. It seems that store LFL was positive despite lower footfall, but online was not.
Outlook & FY27 guidance
To its credit, JD Sports does at least provide clear financial guidance within its trading updates, providing a relatively even playing field for investors regardless of access to broker coverage.
Two sets of guidance numbers are provided today:
FY27 adj pre-tax profit: now expected to be £700m to £800m (previously £750m to £850m)
FY27 free cash flow: £460 to £520m (unchanged)
The company has maintained its free cash flow guidance despite trimming profit forecasts, citing “ongoing cost and capital discipline”.
Taking the mid-points of today’s free cash flow guidance gives me a figure of £490m. That’s equivalent to a free cash flow yield of 12% after today’s fall. If that figure is calculated without too many exclusions, then I think this could be a pretty attractive valuation.
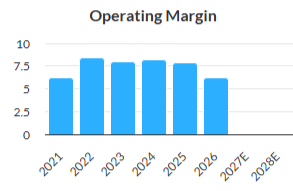
Turning to earnings, my guesstimate suggests EPS forecasts could fall to c.10.7p after today’s warning, putting JD on a P/E of 8.
While this seems quite modest, profitability has deteriorated at this retailer and sales trends are also weak, making it harder to justify a significant re-rating:
Roland’s view
I have to hold my hands up here – when I wrote about JD Sports in May, I gave the company the benefit of the doubt and maintained our moderately positive view, despite management warning of “a wider range of profit guidance” than previously.
With hindsight, I should probably have been a little more cautious given JD’s persistently declining earnings trend:
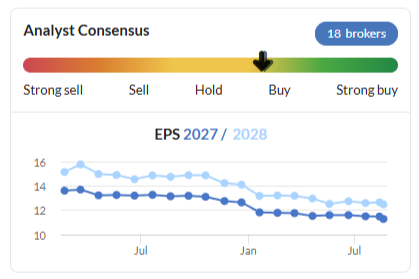
Some of JD’s persistent weakness is obviously due to consumer conditions that are outside its control. But I think some of the headwinds being faced by the group reflect its dependence on a few key brands to drive sales.
In fairness, it’s probably worth keeping the situation in perspective. This is still a large, profitable and cash-generative retailer that’s expected to generate sales of £12.8bn this year.
I think there’s a good chance performance will recover when external conditions become more favourable.
It’s also possible that JD might soon end up with a new CEO – the current incumbent has already reportedly fought off one effort to unseat him by the former chair, but issuing another profit warning could prompt the incoming chair to review the situation.
I’m going to move our view down by one notch to neutral today, in line with our normal approach to profit warnings.
I think JD Sports remains worth watching and could be good value, but the situation isn’t without risk. Even if a more positive view is ultimately correct, the timing of a recovery seems uncertain at the moment, raising the potential opportunity cost of holding.
Ashtead Technology Holdings (LON:AT.).
Down 15% at 362p (£292m) - Trading Update - Roland - PROFIT WARNING ( AMBER ↓)
This oil and gas equipment rental specialist looked quite cheap prior to today’s profit warning – and perhaps now we know why.
My initial impression is that today’s warning was solely due to the impact of the Middle East conflict, but on further reading it turns out that delays are creeping in elsewhere too:
Middle East: full-year guidance was contingent on the easing of the conflict, but this hasn’t happened. As a result, a number of projects in the region earmarked for H2 have now been postponed until 2027.
Europe & The Americas: “The continued and broader economic uncertainty, and changes to vessel scheduling” have led to project delays.
Net debt: leverage is expected to be 1.3x at the year end, which the company says reflects a “strong” balance sheet. I am not entirely convinced: broker Zeus now expects net debt to be c.£95m at the year end, up from £82.5m previously. While this should be manageable, I am not sure I’d describe it as strong.
Outlook & Impact
Full-year revenue is now expected to be around 5% below previous consensus of £214.2m.
Unfortunately, the deferral of (higher margin) rental revenue and the negative operating leverage resulting from lower utilisation mean that the impact on profit will be significantly greater:
Adjusted EBITDA is expected to be “around 15%” below current consensus of £59.2m
My calculations suggest revised figures of £203.5m and £50.3m for revenue and EBITDA, respectively.
With thanks to broker Zeus on Research Tree, we can see how this is expected to translate into earnings. Notably, Zeus has also cut its forecasts for 2027 today, sensibly suggesting the impact of current headwinds is expected to roll over into next year:
FY26E adj EPS: 37.7p (-17% vs 45.2p previously)
FY27E adj EPS: 46.6p (-9% vs 51.3p previously)
These estimates leave Ashtead on a largely-unchanged forward P/E of about 9, following this morning’s share price drop:
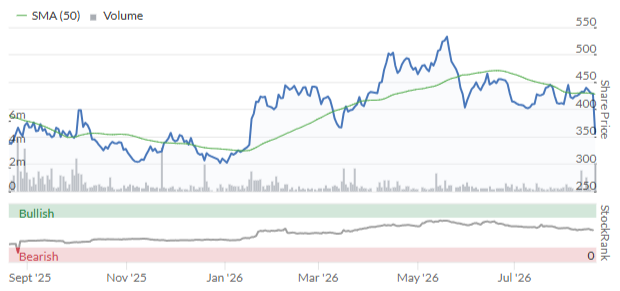
Roland’s view
Mark and I were AMBER/GREEN on Ashtead in March and July respectively, following in line updates on both occasions.
If memory serves me correctly, the situation in the Middle East seemed somewhat closer to a resolution one month ago than it does today. With H2 now nearly one-third complete and the situation more uncertain than ever, I guess operators in the region have decided to rule out any hope of improvement in 2026 and look ahead to next year.
There’s not enough information in today’s update to allow us to gauge the relative impact of delays in Europe and the Americas. As far as I can see, this is the first mention of such issues. I would imagine the impact is secondary to the problems in the Middle East, but I think it’s something to watch.
Fundamentally, I don’t think there’s anything wrong here. While leverage appears to be nudging higher, I don’t think it’s likely to become an issue unless trading worsens significantly.
However, Ashtead is clearly both cyclical and at the mercy of events outside its control – never a great situation.
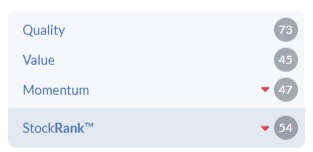
I think this might be a stock that could reward sector knowledge and in-depth research, but from my generalist perspective I think it makes sense to mirror the StockRanks and adopt a neutral view today. Personally, I’d be inclined to stay on the sidelines until more clarity emerges.
Capital (LON:CAPD)
Up 9.4% at 118p (£264m) - H1 2026 Results - Roland - AMBER/GREN =
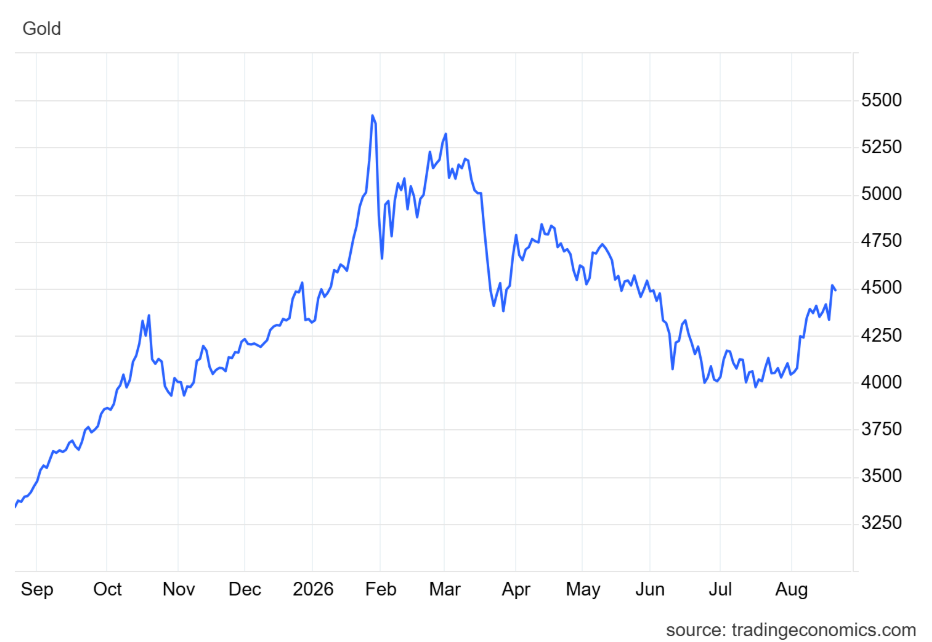
Gold mining services contractor Capital appears to have enjoyed a strong start to the year. The company has upgraded its full-year revenue guidance today, despite the weakness in the gold price so far this year.
Today’s results show a strong performance in both the group’s operations and its concentrated investment portfolio:
Revenue up 37.6% to $219.0m
Operating profit up 96.3% to $31.8m
Investment gain: $7.0m (H1 25: $19.3m)
Net profit after tax: up 43.9% to $21.3m
Operational (adjusted) earnings per share up 581% to 7.5 cents
Net debt reduced by 21.8% to $43.3m
Investments held at fair value up 19.5% $116.5m (from 31 Dec 25)
These figures show Capital’s operating margin rising to 14.5% (H1 25: 10.2%) and suggest a positive performance across its operating units. A breakdown of revenue largely confirms this view:
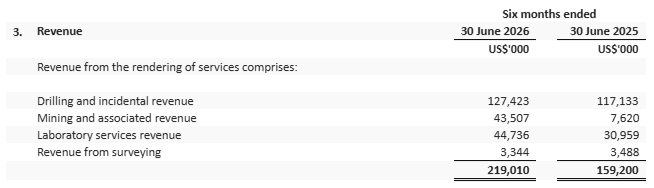
Source: Capital H1 2026 results
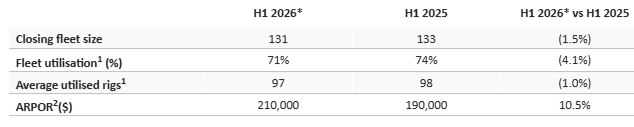
Drilling: revenue rose and the company was awarded a number of multi-year contracts during the period. However, the planned withdrawal from two ceased contracts and the impact of rigs in transit meant that both fleet size and utilisation fell during the half year. Fortunately, there was strong growth in average monthly revenue per operating rig (ARPOR), suggesting underlying demand remains strong:
Mining: contract mining operations at the company’s flagship Reko Diq project “continue to perform well and in line with the contract”. A new waste stripping contract was also awarded at the Sukari Gold Mine.
MSALABS: laboratory utilisation improved to 54% in H1, from 45% in H1 25. This is not quite as bad as it sounds – Capital has been opening new laboratories and now has 33, up from 28 at the end of 2025. New sites naturally take a little while to gain utilisation.
Investments: the portfolio saw $7.2m of gains and income in H1, achieving a 7.4% return. During the same period, the VanEck Junior Gold Miners ETC apparently decreased by 14.1%. The company’s concentrated portfolio appears to be performing well and Capital made a further $11.8m of investment purchases during the half year, primarily by contributing to equity raises at existing holdings.
Outlook
There are a few moving parts to digest here – earnings forecasts have been cut today, despite an increase to revenue guidance:
2026 revenue guidance is now $430m to $450m, from $410m to $440m previously.
This increase appears to be driven by Drilling and/or Mining Services, as MSALABS guidance is unchanged at $85m to $95m.
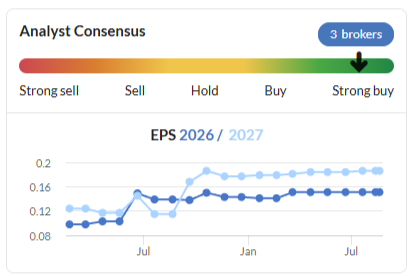
Updated broker forecasts: Capital chose not to comment on profit expectations in today’s update. Fortunately we have access to broker forecasts, with thanks to broker Panmure Liberum on Research Tree. These show a slightly nuanced picture:
FY26E adj pre-tax profit: $57.5m (unchanged)
FY27E adj EPS: 14.1c (-8.2% vs 15.3c previously)
Unchanged pre-tax profit forecasts reflect an expected increase in operating costs this year. I don’t know how much of this is related to cost inflation and how much reflects investment in additional capacity. I would guess that it could be a combination of the two.
The reduction in EPS forecasts is said to be due to a one-off high tax rate in Tanzania, the impact of which is expected to normalise next year.
However, PanLib has also trimmed its earnings forecasts for both 2027 and 2028:
FY27E adj EPS: 19.6c (-3.5% vs 20.3c previously)
FY28E adj EPS: 22.7c (-3.5% vs 23.5c previously)
The broker emphasises that its estimates are conservative, so perhaps there will be room for further upgrades when visibility improves:
Roland’s view
Capital’s share price has been weak in recent months, mirroring the decline in the gold price. Today’s share price rise still leaves the stock well below levels seen earlier this year:
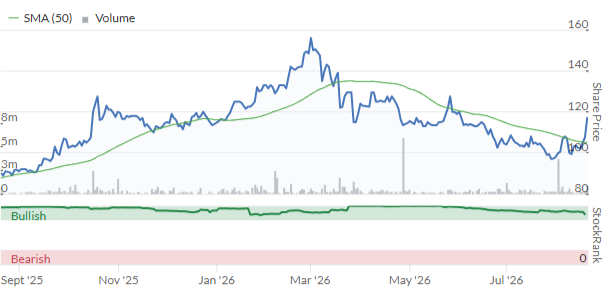
The stock continues to trade slightly below its book value of c.130p and operational progress appears to remain positive.
This is a specialist business run by a founder-manager with significant skin in the game. While there will be some lumpiness to results at times, I don’t see any reason to change our previous AMBER/GREEN view today, despite the modest revision to earnings.
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.