
Anthropic IPO: Bloomberg confirms that Anthropic “expects to match or beat” SpaceX’s IPO size.
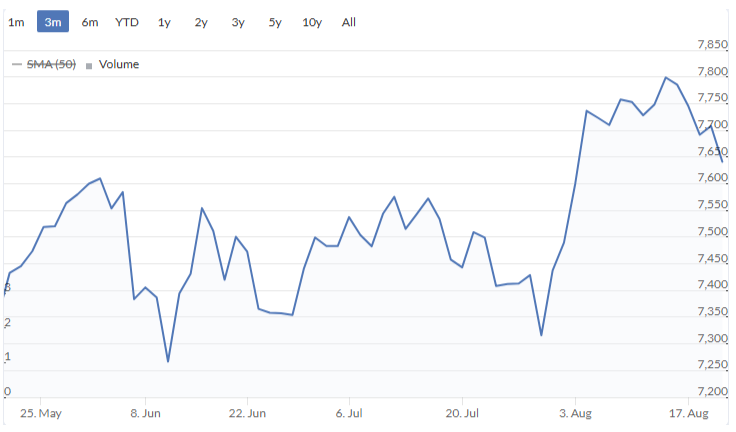
When Space Exploration Technologies (NSQ:SPCX) hit the market in June, I thought that its overwhelming size might become a headwind for US equity markets. But the major indexes show no sign of slowing down yet. The S&P 500 (which doesn’t include SpaceX) has reached new highs:
With the market having digested SpaceX so easily, the AI giants are now on the way.
SpaceX raised $86 billion in total; if reports are to be believed, Anthropic is likely to raise even more than this.
As for the valuation it might achieve, the IPO markets on IG* currently suggest that Anthropic’s Day 1 Market Cap will be c. $1.97 trillion, using the midpoint of the spread. That’s just shy of the $2.1 trillion achieved by SpaceX on its first day of trading. Exciting times!
(*I'm long IGG.)
Overnight market movements:
The FTSE is unchanged at 10,765
S&P 500 is unchanged at 7,650
Brent crude (November) is down 0.6% at $91.50/bbl
Gold is up 0.7% at $4,550/oz
Bitcoin is up 3.7% at $75,300
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Spire Healthcare (LON:SPI) (£951m | SR72) | “Toscafund has confirmed to the Board that its due diligence has concluded and that it continues to work towards the announcement of a 250 pence per Spire Healthcare share recommended offer.” | TAKEOVER (Graham) [no section below] | |
Hunting (LON:HTG) (£720m | SR87) | “The Directors anticipate continued year-on-year growth into 2027 given Hunting's diversified portfolio. Dependent on the timing and outcome of the KOC (Kuwait Oil Company) tender, it will have a maximum adverse impact of c.$10m on current 2027 EBITDA consensus.” | PROFIT WARNING (AMBER/RED ↓) (Graham) Hunting is a highly reputable, well-diversified organisation with a long and proud history. In many ways, this is a blue-chip stock. However, there’s no getting away from the downgrade today - and we already considered it to be fully valued. I’m therefore taking a moderately negative stance on this one today. | |
PPHE Hotel (LON:PPH) (£659m | SR22) | Sale of the freehold site to a US real estate developer for the purchase price of $33.5m. The sale proceeds were used to repay the associated debt of $6.75m. | GREEN = (Graham) [no section below] With takeover talks having collapsed here, these shares continue to trade and we can continue to speculate on what they might be worth. I'm fascinated by the fact that Eli Papouchado, the largest shareholder (through Euro Plaza Holdings), turned his nose up at a £22 per share offer. I've long suspected that PPHE might be worth something closer to net asset value, which according to real estate accounting rules is c. £27 per share, rather than the much lower levels at which it typically trades. With a current share price of only about £16, I am going to stick to my guns and stay GREEN on this one. Acquirers were apparently willing to pay £22; I think it's worth our while staying positive here. | |
| Metals Exploration (LON:MTL) (£454m | SR66) | La India Development Update | SP +4% First gold production at La India (Nicaragua) remains on track for December 2026. US$27 million equipment loan completed with a local Nicaraguan bank - an initial US$20.2 million drawn down. | AMBER ↑ (Graham) [no section below] Mark was moderately negative on this in April at a share price of 13.7p, after a 20% cut to production guidance. I'll put us back on neutral today on the grounds that Mark himself thought that the shares were not necessarily expensive at that price, and today's update is encouraging. La India (Nicaragua) has some pretty impressive resource estimates: 66,000 ounces at a high grade (9.9 grams/tonne), and vastly more estimated to exist at lower grades, including 194,000 ounces at medium-grade (6.2 grams/tonne). Total indicated and inferred gold is some 2.3 million ounces, although only a fraction of this might be mined economically. With La India on track, there is also positive news from the Philippines with gold production at MTL's Runruno mine now forecast at the upper end of the 2026 production guidance. MTL is trading at 5x earnings according to the StockReport and while I tend not to pay the P/E multiple much attention when it comes to mining companies, it seems reasonable to at least be neutral on this one. |
BTG Consulting (LON:BTG) (£176m | SR77) | In Q2 2026, the number of UK businesses in 'critical' financial distress increased by 9.0% year-on-year to 53,756. Leisure & Cultural Activities +27.1%, Hotels & Accommodation +26.5%, Sports & Health Clubs +21%, Food & Drug Retailers +18.4%. | AMBER/GREEN = (Graham) We’ve been moderately positive on BTG and I see no reason to change stance on it today. The valuation is reasonably full for a professional services business but deservedly so, in my opinion. Today's Red Flag Alert provides the company with some nice PR while also giving us some interesting insights into general business health. | |
Knights group (LON:KGH) (£150m | SR78) | FY25: Moore Barlow delivered revenue of £42m and profits distributable to members (ie pre-partner drawings) of £12m. Draft accounts for FY26 show revenue of £45m and profits distributable to members of £13m. Total cash consideration of £27m, of which £18m is paid upfront. | ||
Springfield Properties (LON:SPR) (£127m | SR91) | SP +4% Seeking the approval of shareholders for the repurchase of up to 5,957,372 shares, with flexibility to extend up to the full Buyback Authority limit of 11,904,240 shares. The Concert Party will not be obliged to make a mandatory offer for the entire company. | GREEN = (Graham) [no section below] Like so many housebuilders, Springfield are trading at quite a chunky discount to book value, despite trading profitably. The problem with all "deep value" investments is time - how long to wait until a catalyst appears? A buyback is one of my favourite such catalysts and Springfirled are now looking for permission to buy up to 12 million shares - 10% of the existing share count. That's a meaningful amount and a vote is needed because of the Adam family's shareholding (Chairman Sandy Adam is the grandson of Springfield's founder). A buyback could increase the family's percentage ownership of the company, and this would ordinarily trigger a mandatory takeover offer from the Adam family. SPR's shareholders are being asked to approve a waiver so that a takeover offer will not legally required. I'd be very much inclined to approve this! The company reported a net cash position of £1m for May 2026, and it made a land sale recently for £12m. About half of that land sale cash was used to settle an acquisition from several years ago, but the rest is presumably available for this planned buyback. With annual forecast after-tax profits running at c. £10m, this buyback looks to me like it's probably an excellent use of surplus cash. | |
Real Estate Investors (LON:RLE) (£54m | SR45) | Sale of £10.7m at 92% of Dec 2025 book value. “The completion of scheduled sales in Q4 2026, combined with the conclusion of sales in our legal pipeline will repay the Company's entire debt in full, allowing us to commence capital returns to our shareholders.” | ||
Corero Network Security (LON:CNS) (£37m | SR18) | CNS announces AI-Augmented Cloud-Assist for SmartWall ONE™, extending its automated DDoS protection with cloud-delivered AI analysis, threat intelligence, and policy optimisation. | Reach announcement (non-regulatory press release). | |
Amigo Resources (LON:AMGO) (£35m | SR86) | MoU with the State Mining Corporation of Tanzania establishes a strategic collaboration framework to evaluate a significant graphite tailings recovery and beneficiation project in Tanzania. | ||
Tekcapital (LON:TEK) (£9m | SR43) | Innovative Eyewear has developed significant new features for its smart eyewear products, delivered via the Lucyd app for iOS and Android. In particular, the Newscast widget allows users to create custom, generative AI news reports to be read out on Lucyd eyewear. |
Graham's Section
Hunting (LON:HTG)
Down 13% at 412p (£624m) - Graham - PROFIT WARNING (AMBER/RED ↓)
Hunting are specialists in “the global manufacture, trade and rental of high quality equipment for the energy industry.”
Their advanced manufacturing capabilities are also used in the Aerospace/Defence, Telecoms, Medical and Transportation industries.
We’ve been neutral on it (see Mark’s coverage here), arguing that it’s priced about right and also noting some soggy EPS forecasts:
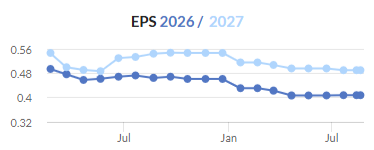
Today’s interim results bring a fresh downgrade to forecasts. Let’s fast-forward to the key sentence outlining the problem.
Kuwait Oil Company “has provided a verbal indication to all vendors that it will now re-run the OCTG tender process, which was originally issued in April 2026.”
OCTG stands for “oil country tubular goods”. Hunting won orders worth over $200m from Kuwait in recent years. However, the most recent orders have been disrupted by the conflict in the Middle East, and now they have to run the tender again:
As previously guided, Hunting's earnings profile for 2026 will be weighted towards the second half. The KOC tender process delay will have an impact of c.$10m on 2026 EBITDA, resulting in a revised 2026 EBITDA guidance range of $138-141m, slightly below previous guidance. Projected year-end total cash and bank position is broadly unchanged at c.$50-$60m as working capital investments in H1 unwind.
So 2026 is going to be “slightly below guidance”.
2027 is where the bigger impact lies:
The Directors anticipate continued year-on-year growth into 2027 given Hunting's diversified portfolio. Dependent on the timing and outcome of the KOC tender, it will have a maximum adverse impact of
c.$10m on current 2027 EBITDA consensus.
Prior consensus was for 2027 EBITDA of $165m.
So let’s call that a 6% downgrade to next year’s profit forecast.
H1 results
The results for the H1 period to June 2026 are not too exciting: revenues down 6%, and adjusted PBT down 21%. The sales order book is also significantly lower year-on-year:
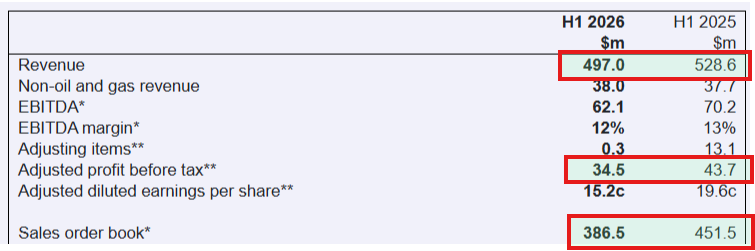
On the bright side, let’s give the company credit for posting results with almost no adjusting items.
The soon-to-retire Chief Executive seems happy with strategic progress:
Today's results demonstrate the benefits of the transformation of Hunting's portfolio and our ability to capitalise on the structural growth opportunities in the end-markets we serve. In particular, the strong margins delivered from our Subsea product group, following our strategic repositioning in this area over the past seven years, are strengthening the quality of our earnings into the long-term, a key deliverable of our 2030 strategic ambition. We have also seen encouraging momentum in our Perforating Systems product group, as our technology offering continues to be embraced by the industry, with record international sales supporting the Group's overall results.
The company balance sheet is very large with $863m of net assets, of which only about $100m is tangible.
In that context, and considering the large EBITDA numbers, the latest net debt figure of $51.4m, including leases, doesn’t worry me very much.
Graham’s view
Hunting is a highly reputable, well-diversified organisation with a long and proud history. In many ways, this is a blue-chip stock.
However, there’s no getting away from the downgrade today - and we already considered it to be fully valued.
I’m therefore taking a moderately negative stance on this one today.
If peace and harmony break out in the Middle East, then I agree with it that activity in the region will “rapidly recover”. So that’s something to look forward to - although when it might happen is anyone’s guess.
Until then, we have a large industrial stock that needs a new CEO and is earning pretty average returns.
BTG Consulting (LON:BTG)
Up 1% at 110.4p (£176m) - Latest Red Flag Alert for Q2 2026 - Graham - AMBER/GREEN
We have the latest quarterly Red Flag Alert from BTG Consulting, i.e. Begbies Traynor. It provides a nice bit of PR for an insolvency practitioner while also giving us some insights into the financial health of businesses across the country.
This is quite an interesting report. Some headlines:
The number of businesses in “critical” financial distress is up by 9% year-on-year to 53,800.
Consumer facing industries under the most pressure, e.g. Leisure & Cultural Activities and Hotels & Accommodation in distress up 27% year-on-year.
Number of businesses in “significant” financial distress up 1.1% to 674,000.
So the growth in “significant” distress is very mild, but there’s an escalation when it comes to “critical” distress.
As for winding-up petitions, they increased by 15.7% in 2025 vs. 2024.
Comment by Ric Traynor:
"Against a backdrop of ongoing geopolitical challenges, there appears to be no relief in sight for distressed UK businesses. Whilst the extent of the impact is still unknown, the escalation in winding-up petitions is an ominous sign…
"Rising energy prices are likely to push inflation higher again this autumn, squeezing consumers just as borrowing costs remain elevated…
"Sadly, when confidence and spending remain subdued, I expect the resulting shockwaves to be felt across many other industries later this year and into 2027."
We should bear in mind that insolvency practitioners have an incentive to talk down the economy! Bad news for them is good news for everyone else.
But I do tend to trust this Red Flag Report; it has been published for many years and it rings true. The rise in insolvencies in recent years has coincided with very strong trading at BTG (mostly organic growth, I think):
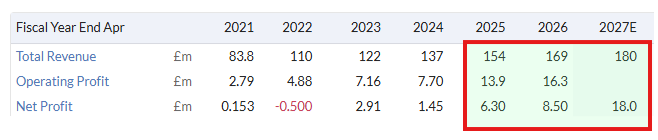
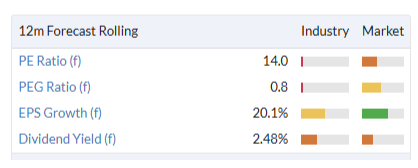
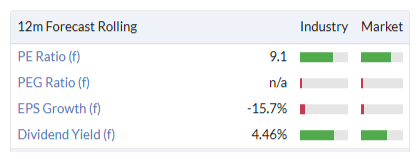
We’ve been moderately positive on BTG and I see no reason to change stance on it today. The valuation is reasonably full for a professional services business but deservedly so, in my opinion:
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.