
Good morning. US Treasury Yields continue to grab headlines following last week’s buyback launch – essentially, the US Treasury is expected to repurchase long-dated bonds (pushing down their yields) with funds raised by issuing more short-term debt (potentially raising the yield of shorter-dated Treasuries).
It’s an effort to reduce the cost of long-term US government borrowing, but to me it seems like the kind of strategy the market will attempt to exploit - it doesn't address the core issue, which is that the US government's spending significantly exceeds its income. With US national debt now standing at $40tn, this is starting to concern markets.
Investors will certainly be keen to see what Federal Reserve chair Kevin Warsh has to say about the economy at his first Jackson Hole symposium later this week.
In the Middle East, the US focus appears to remain on inflicting new economic pain on Iran. Secretary Bessent has taken time out from trying to manage Treasury yields to publish a piece in the FT titled “... an economic D-Day is coming for Iran”.
Closer to home, Prime Minister Burnham is heading to Ukraine on his first official overseas visit as UK PM. He’s expected to offer additional long-range missiles while in Kyiv.
Finally, some possible good news: productivity in the UK economy could be stronger than previously thought. That’s the conclusion from new analysis by the Resolution Foundation, which suggests official figures could understate recent productivity.
On this rare positive note, let’s take a look at today’s news.
Overnight market movements:
The FTSE is unchanged at 10,810
S&P 500 is down 0.2% at 7,662
Brent crude is down 1.5% at $91.47/bbl
Gold is up 0.2% at $4,643/oz
Bitcoin is down 0.7% at $77,183
Ed Sheldon joins me (Roland) today. It's looking pretty quiet today, so we're happy to take requests for any recent backlog items.
Wrapping it up there for today (12:00). See you in the morning!
Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
GSK (LON:GSK) (£78bn | SR84) | First global approval for Hibsago in Japan & US FDA to review Jemperli for rectal cancer | Hibsago (bepirovirsen) approved in Japan as the first and only functional cure for chronic hepatitis B. Jemperli (dostarlimab) accepted for priority review by the US FDA for dMMR/MSI-H locally advanced rectal cancer. The submission is supported by AZUR-1 data showing a significant proportion of participants with no detectable signs of cancer one year or more after treatment. | AMBER = (Roland - I hold) [no section below] It’s difficult for non-expert investors to understand the potential impact of product approval and review notifications such as these from GSK this morning. The key question is whether these drugs are likely to be big sellers for GSK in the future – will they move the needle and help offset the impact of patent expiries elsewhere? Helpfully, the Reuters newswire provides some additional useful info today: - GSK has predicted that bepirovirsen could bring in “over £2 billion” in peak annual sales. - The US FDA has targeted a Feb 27 action date for the dostarlimab review. While I am broadly positive on GSK at the current valuation, I don’t think there’s enough here to justify altering our previous neutral view, so I’m leaving it unchanged today, in line with the StockRanks' neutral styling. |
MS International (LON:MSI) (£261m | SR66) | Contract to Supply Counter Uncrewed Aerial System to NATO Nation | The contract is worth €19.4m and will see MSI supply three MSI-DS 30mm naval gun systems. Deliveries are expected to begin towards the end of 2027. | GREEN = (Ed S) MSI INTERNATIONAL is increasingly focusing on defence and security, so the backdrop looks favourable to me. Today’s contract news is encouraging. At face value, the stock looks a little bit expensive, however, there is a fair bit of quality here – and plenty of long-term growth potential – so a higher valuation could be justified. |
Iofina (LON:IOF) (£96m | SR78) | An additional brine water source at IO#11 is now installed. When operational, it’s expected to support an increase in crystalline iodine production by c.45-65 tonnes annually (a 50% increase). The construction of IO#12 continues to progress as planned. | AMBER = (Roland) [no section below] We don’t cover this iodine production business very often, but I wonder if this should change. Broker forecasts were upgraded earlier this year, with a significant step up in earnings predicted for both 2026 and 2027. Today’s update confirms the business remains on track to deliver significant production growth. Against this backdrop: the valuation doesn’t look unreasonable to me if Iofina can deliver on current expectations. Exposure to commodity pricing and a relatively capital-intensive model suggest some caution remains appropriate, but I’m intrigued by the double-digit returns that were generated last year. I’m going to stay neutral ahead of September’s half-year results, but I think this could be worth reviewing again when we have more current details on financial performance. | |
Tracsis (LON:TRCS) (£95m | SR62) | Trading Update, Completion of Acquisition and Notice of Results | FY26 performance in line with expectations. Revenue expected to be +4.4% at c.£85.5m, with adj EBITDA to be +7.1% at c.£13.5m. Pro forma net debt/EBITDA leverage following completion of the recent Mistral Data acquisition is expected to be c.1.5x. Singer Capital EPS estimates: - FY27E adj EPS: 34.6p - FY28E adj EPS: 41.9p | AMBER/GREEN ↑ (Roland) These FY26 numbers are in line and suggest that revenue and profits would have fallen following the Event disposal if Tracsis hadn’t made the (much larger) acquisition of Mistral Data. However, the net result of the two transactions appears to be that the earnings outlook for FY27 and FY28 has improved, at least according to forecasts from Singer Capital. I think the combination of a forward P/E of <10 and possible upgrades to consensus EPS estimates supports a more positive view on Tracsis than we’ve had previously. |
Cora Gold (LON:CORA) (£67m | SR22) | "The renewal of the Sanankoro II exploration permit is a part of an ongoing permit reshaping exercise, needed to get all mining infrastructure under one mining permit area, and a significant step towards being awarded a mining permit for Sanankoro.” | ||
Zephyr Energy (LON:ZPHR) (£63m | SR26) | Zephyr's board has elected to fund additional engineering and well work to prepare for a higher production rate during the initial phase of the project's development. The company is confident it will receive permission to uprate the existing 16-inch pipeline. | ||
Batm Advanced Communications (LON:BVC) (£40m | SR59) | H1 revenue from continuing operations +5% to $41.7m, with adj operating profit +75% to $0.7m. H1 performance in line with expectations, full-year outlook unchanged. | AMBER = (Ed S) | |
Georgina Energy (LON:GEX) (£38m | SR21) | Has raised £1.25m. Proceeds of the placing will be used for the Hussar drilling programme and general working capital. | ||
Edx Medical (LON:EDX) (£36m | SR1) | Has raised £2.7m. The proceeds of the fundraising will be used to support the expansion of the company's new employee health screening service. | ||
Amigo Resources (LON:AMGO) (£36m | SR86) | Letter to Update Shareholders from Craig Ransley, Executive Chair | The Board has formally adopted its first dividend policy. The target under this new policy is to deliver an inaugural dividend within the next 12 months. | |
Synectics (LON:SNX) (£33m | SR60) | The company has secured a £1.4m contract to provide an integrated security and surveillance solution to global energy company Eni for its Kutei Floating Production, Storage and Offloading (FPSO) Project in Southeast Asia. | AMBER/RED = (Roland) [no section below] Today’s contract win looks positive enough in itself, but there’s no indication of any change to expectations and this contract isn’t expected to contribute anything to FY26 revenue. For some context, £1.4m represents 2% of FY27 forecast revenue, so while useful, it’s unlikely to have a huge impact on next year’s earnings. For me, the main point here is that broker forecasts have been cut twice so far in 2026. Weak profitability also remains a concern for me, most recently with the H1 resultson 18 August. Those numbers looked fairly weak to us, so I’d want to see more evidence of recovery before upgrading our view here. | |
Skinbiotherapeutics (LON:SBTX) (£25m | SR15) | Anita Slater appointed as Interim CFO for an initial six-month term. Ms Slater has 30 years' experience in commercial and financial senior leadership roles including Board positions. | ||
Quantum Helium (LON:QHE) (£12m | SR20) | The company is finalising an engineering assessment to define the next phase of testing, stimulation and field development. It has now also provided all requested documentation in connection with its proposed OTC Markets listing in the US. |
Roland's Section
Tracsis (LON:TRCS)
Up 7% at 343p (£103m) - Trading Update, Completion of Acquisition and Notice of Results - Roland - AMBER =
Transport technology provider Tracsis recently doubled-down on its exposure to UK rail with the £48m acquisition of Mistral Data from FirstGroup. The acquisition – on a multiple of 12x EBITDA – wiped out the group’s long-standing net cash position and moved Tracsis into debt.
Graham reviewed this acquisition at the time and concluded that it added both risk and potential reward. Mistral is a business Tracsis knows well, with complementary products. But the addition of leverage and the relatively high multiple paid mean that generating satisfactory returns on this expenditure is not guaranteed.
Today’s update confirms the completion of the Mistral acquisition and provides an update on trading for the year ended 31 July 2026.
FY26 summary
We won’t see the impact of Mistral until later in the current year. But the good news is that Tracsis’s FY26 results are expected to be in line with market forecasts:
The Group has delivered full-year performance in line with market expectations and ahead of FY25.
The headline financial figures provided today suggest mid-single digit percentage growth:
Revenue up 4.4% to c.£85.5m
Adj EBITDA up 7.1% to c.£13.5m
Pro forma leverage following Mistral acquisition of c.1.5x
These figures include a contribution from the Events business that was sold on 31 July.
We aren’t told the FY26 performance of the Events business, but we do know that in FY25, Events generated revenue of c.£20.4m and adj EBITDA of c.£1.9m.
Given this, it seems fair to suggest that FY26 revenue and EBITDA from the continuing Tracsis business (excluding Events) might be c.£65m and c.£11.5m.
Outlook
Looking ahead, Tracsis is better positioned than ever, with a portfolio aligned to attractive long-term growth markets, a higher proportion of recurring revenue and an increasing emphasis on scalable software products.
With a simplified operating model, enhanced capabilities and a clear strategic focus, we are well placed to benefit from sustained investment in rail technology driven by the industry's need for greater efficiency, productivity, safety and customer experience. Our priority is now to integrate Mistral Data successfully and capitalise on the significant opportunities ahead.
The addition of Mistral should mean that the company’s FY27 results show a significant increase in both revenue and earnings.
With thanks to broker Singer Capital we can see how this might look:
FY26E adj EPS: 27.3p
FY27E adj EPS: 34.6p (+27% vs FY26E)
FY28E adj EPS: 41.9p (+21% vs FY27E)
These estimates put Tracsis on an FY27E P/E of 10, falling to a FY27E P/E of 8.4.
Roland’s view
These are undemanding earnings multiples for a business with significant market share in its UK rail niche and some other potentially attractive software businesses.
Another potential positive is that the group’s cash generation has generally been pretty strong. The StockReport shows Tracsis trading on a trailing price to free cash flow ratio of 10x. If this performance can be maintained, repaying the debt used for the Mistral acquisition shouldn’t be a serious issue. Indeed management has already said that leverage is expected to fall to c.1.0x EBITDA by the end of 2027.
So why aren’t Tracsis shares more highly rated? For me, there are two possible reasons:
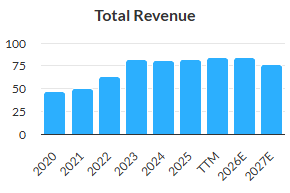
A lack of organic growth: while Tracsis has regularly expanded through acquisitions, the level of organic growth within the business has often appeared to be quite weak. Revenue expectations prior to the acquisition of Mistral Data were for the top line to broadly flat at FY23 levels:
Poor profitability: the other bugbear I have with this business is that reported measures of profitability are pretty low:
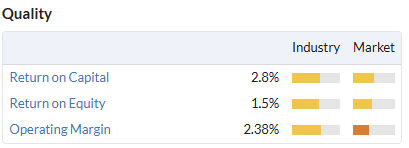
Some of this may reflect one-off exceptional items and restructuring costs.
However, when I see a combination of strong free cash flow and low reported profitability in an acquisitive business, I often suspect that past acquisitions have been made at high valuations. This can result in high levels of goodwill on the balance sheet (lowering ROCE) while also giving rise to large non-cash amortisation charges each year (lowering operating margins and ROE).
Tracsis’s goodwill balance has risen from £3m in FY26 to £18m in FY25, prior to the Mistral acquisition. For a business where operating profit is measured in single digit millions, this will have had a material impact on reported returns.
The question for shareholders now is whether the enlarged scale and increasing recurring revenue focus of the business will translate into higher returns over time, justifying past capital allocation decisions.
I am tempted to maintain our neutral view, but on balance I’m starting to think this could be overly harsh. As far as I can see, broker upgrades to reflect the Mistral acquisition have not yet been incorporated into the consensus earnings estimates on the StockReport. When they are, the net effect should be a useful upgrade to current EPS forecasts.
With a forward P/E multiple of <10x even after this morning’s share price gain, I think it’s fair to move our view of Tracsis up by one notch to AMBER/GREEN.
Ed S's Section
MS International (LON:MSI)
Up 5% to 1,670p (£261m) - Contract to Supply Counter Uncrewed Aerial System to NATO Nation - Ed S - GREEN =
Engineering company MS INTERNATIONAL plc – which is increasingly focusing on the defence industry – has posted a brief operational update today.
It tells us that its wholly owned subsidiary, MSI Defence Systems Limited, has been awarded a €19.4m contract by a NATO nation to supply three MSI-DS naval gun systems. These systems will provide Counter-Uncrewed Aerial System protection alongside the MSI-DS system's established naval capability.
The company says that the MSI-DS 30mm gun systems will be supplied with radar and optical detection capability, together with the MSI-DS Fire Control System.
This integrated configuration will provide the vessels with protection against surface, semi-submersible and aerial threats at a time when adaptable weapon systems are increasingly required.
Delivery of the systems is expected to begin towards the end of 2027, in line with the overall programme requirements.
Ed S’s view:
This stock is not going to be for everyone given its focus on defence and weapon systems. However, I think it looks quite interesting.
To recap, MS INTERNATIONAL is a relatively broad engineering business with operations in multiple areas including defence and security, forgings, petrol station superstructures, and corporate branding. However, last year, it announced that it would be focusing more on defence and security, and look to sell off its other divisions.
In July, it told us that it was in talks with potential buyers for the sale of the petrol station superstructures and branding businesses. At the time, it said that it was hoping an announcement would be made by the end of Summer, so we may hear some news here shortly.
It also said that it had received unsolicited interest in the forgings business but had not yet undertaken a formal sale process. It plans to revisit this once the petrol station superstructures sale is approaching a satisfactory conclusion.
Zooming in on the defence business, it offers a range of products including naval gun systems, mobile land-based defence systems, and optical systems. These kinds of products should see robust demand in the years ahead given NATO’s commitment to higher levels of defence spending.
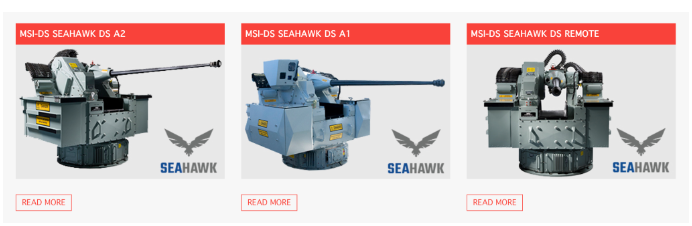
Note that in July, the company said it was receiving “substantial international interest” for its range of defence and security products – especially its counter-drone capabilities. It added that it was anticipating that much of this international interest would convert to orders and that it already has the facilities and capacity to meet this demand when it crystalises.
There is hardly a conversation or story worldwide about the future of defence that doesn't refer to drones. Our equipment is at the forefront of counter-drone capabilities, which has stimulated a substantial level of international recognition and interest in our combat proven systems.
On the downside, contract wins are lumpy here. As a result, there can be long periods without much news (which can lead to downward drifts in the share price).
It’s worth pointing out that in July, management expressed frustration at delays in worldwide defence procurement decisions. Despite the recent NATO spending commitments, order intake has been slow.
It's very encouraging that most Governments now regularly state that defence should have a higher priority. However, getting to the point where these objectives translate into firm defence orders is a jump that's taking longer than reasonably anticipated.
Turning to the financials, there’s a lot to like:
High return on capital employed (ROCE): Over the last three years, ROCE has averaged 22.5%, so we are looking at quite a profitable company.
Strong balance sheet: At the end of April, the company had cash and cash equivalents of £46.53m (2025: £27.78m).
Rising dividends: The total dividend for last financial year was 26p per share (2025: 23p), giving us a yield of about 1.6%.
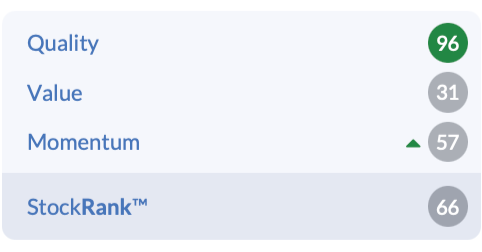
Note that the Stockopedia system gives the company a 96 rating for Quality.
In terms of the valuation, there are no broker forecasts here at present so we don’t have an earnings forecast for the current financial year. Diluted earnings per share last financial year was 65.7p, which puts the stock on a trailing P/E ratio of 25.4.
That looks a little bit expensive at face value, however, if significant defence orders start to materialise, it’s probably justified, in my view. Note that defence giant BAE Systems is currently trading on a trailing P/E ratio of about 28.
As for the chart, it looks attractive. The long-term trend is clearly up.
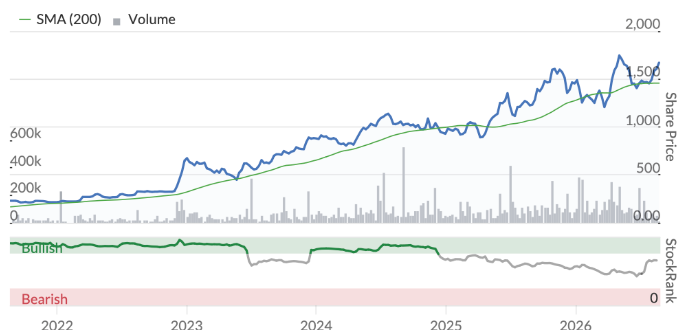
Back in January, Graham gave MSI a GREEN rating. In July, Roland reiterated that rating.
I’m happy to reiterate it too. There are risks around contract lumpiness in the short term, but taking a longer-term view, I see considerable potential here given the defence spending backdrop.
Batm Advanced Communications (LON:BVC)
Flat at 11.85p (£40m) - Interim Results - Ed S - AMBER =
Israeli tech company BATM Advanced Communications has today posted its interim results for the period ended 30 June 2026.
Key numbers:
Revenue: $41.7m versus $39.7m a year earlier (last year’s figure is adjusted for business divestitures).
Gross profit: $14.6m versus $13.9m.
Gross margin: 34.9% versus 34.9%.
Adjusted* operating profit (constant exchange rates): $0.7m versus $0.4m.
Adjusted* operating profit: $0.2m versus $0.4m.
Cash and short-term investments at 30 June 2026 were $22.5m (31 December 2025: $23.4m).
* Adjustments include amortisation of intangible assets, share-based payments, and in H1 2025 exceptional expenses related to corporate activity.
Operational Highlights:
H1 performance in line with management's expectations – strong growth at BATM Networks and increasing momentum at BATM Cyber.
Significant progress on strategy to transform BATM into a focused, high-growth and higher-margin technology business centred on secure managed networking and advanced cybersecurity, including quantum-era-ready encryption.
Entered an agreement for the potential sale of three of the four remaining non-core activities.
Continued to explore potential opportunities to add capabilities via strategic M&A.
Division performance:
BATM Networks: revenue of $8.0m (H1 2025: $6.6m), driven by its new portfolio of carrier ethernet products.
BATM Cyber: revenue of $4.8m (H1 2025: $5.1m), reflecting the timing of budget release by the group's long-standing customer.
We have made significant progress in reshaping BATM into a high-growth, higher-margin technology business focused on secure managed networking and advanced cybersecurity, most notably through the agreement for the proposed disposal of almost all our remaining non-core activities. This represents a major step in sharpening our strategic focus and building a stronger platform for future growth.
Outlook:
The company says that it entered the second half of the year with increasing momentum across the business and remains on track to deliver results for the full year in line with market expectations, including revenue growth for the core business of networking and cybersecurity. It points to a strong pipeline in BATM Networks – where revenues are typically weighted towards the second half of the year – and by the orderbook in BATM Cyber, although it says that the timing of certain cyber orders could be affected by the Israeli national elections expected in October and any associated impact on the release of government budgets.
The company expects to exit the year as a substantially transformed business, operating in the high-growth, high-margin markets of secure managed networking and advanced cybersecurity, with a simplified operating structure and a strengthened balance sheet. The Board believes that the group's strategic repositioning, supported by the anticipated disposal proceeds and positive momentum across its core activities, materially enhances BATM's future prospects.
Looking ahead, we remain on track to deliver underlying revenue growth for the full year in line with management's expectations, supported by our strong pipeline and orderbook. More importantly, we expect to exit 2026 as a substantially transformed business, with greater capacity to invest in growth and to create value for shareholders.
Ed S’s view:
The story here is all about the company’s strategic transformation. This appears to be going well, and it should lead to a more attractive, higher growth, higher margin business.
During the first six months of 2026, the Group made substantial progress in executing its strategy to transform BATM into a focused, high-growth and higher-margin technology business centred on secure managed networking and advanced cybersecurity, including quantum-era-ready encryption.
In today’s update, it says that in H1:
It reached an agreement for the proposed disposal of three of the group's four remaining non-core activities – comprising seven corporate entities – for a cash consideration of $13.3m, representing a valuation of 33x the disposed businesses' adjusted net profit for 2025.
One of the disposed businesses entered into an agreement to sell 96,794,500 ordinary shares of BATM at a price of 18.15p per ordinary share, representing a cash consideration of approximately £17.6m (c. $23.3m).
Together, these agreements represent an aggregate cash consideration of approximately $36.6m, subject to fluctuations in the exchange rate.
It also completed the sale of Laborator A.M.S 2000 SRL, its non-core analytical laboratory business, for cash consideration of $1.0m.
The company says that the proposed transactions provide it with a significant opportunity to crystallise value, strengthen its financial position, and accelerate investment in its core technology businesses. Its aim is to focus on areas where it has the greatest opportunity to deliver sustainable, high-margin growth.
The Group will emerge as a focused high-technology specialist providing mission-critical secure managed networking, quantum encryption and advanced cybersecurity solutions to governments, critical infrastructure providers and global enterprises. This will create a clearer investment proposition and position the Group to capture the growing demand for resilient connectivity, secure communications and next-generation cybersecurity solutions.
At present, the market is giving the company no credit for its strategic transformation:
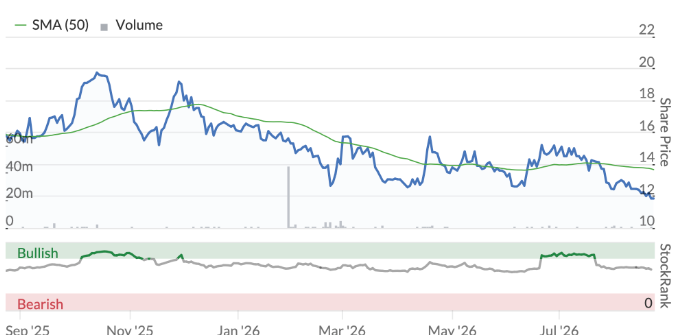
Could there be an opportunity here given the lack of investor interest? Potentially.
Today’s outlook said that the company remains on track to deliver results for the full year in line with market expectations. It didn’t confirm what these are but Stockopedia shows revenue of $95.1m and EPS of 4 cents here.
If it was to achieve 4 cents per share in earnings (I certainly wouldn’t rely on that forecast), we are looking at a P/E ratio of just four. So, there could be some potential here from a value perspective.
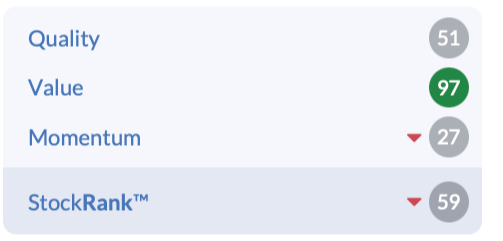
For now though, I’m going to leave the stock on AMBER. I’d want to see evidence of the new strategy delivering growth and higher margins before upgrading it.
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.