
Oil is lower by $5 per barrel since yesterday, down below $86 now (looking at the November contract), as Iran and Oman appear to be working together to come up with a plan to reopen the Strait of Hormuz.
The elephant in the room is of course the lack of involvement of the United States in these talks.
However, Oman has been one of the mediators in US-Iran negotiations, which suggests that it may be able to influence the US and help find a resolution that’s acceptable to all sides.
President Trump’s latest Hormuz statement says that “all mines have been removed and/or detonated from within the International Waters of the Strait of Hormuz. Iran has been notified that any ship or boat placing new mines will be immediately and systematically destroyed.”
It seems that all sides want the Strait of Hormuz to reopen; all that’s missing is an acceptable compromise that would allow it to actually reopen.
Overnight market movements:
The FTSE is up 0.2% at 10,900
S&P 500 is down 0.1% at 7,665
Brent crude (November) is down 1.5% at $85.90/bbl
Gold is down 0.4% at $4,640/oz
Bitcoin is up 1.2% at $79,150
All done for today, cheers! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
Hochschild Mining (LON:HOC) (£3.2bn | SR54) | Revenue up 62% at $844.4m. Profit before income tax of $365.8m. Guidance: Attributable production target reiterated. Revised operations attributable AISC target. $2,380-$2,500 per ounce (previously $2,157-$2,320). | PROFIT WARNING (higher AISC guidance - but the market has shrugged it off thanks to the strong earnings number, share price up 7%) | |
Applied Nutrition (LON:APN) (£804m | SR53) | Board now expects FY July 2026 adjusted EBITDA to be ahead of consensus market expectations, up 40% year-on-year to £43.3m (expectations were £42m). Revenue also ahead of expectations. FY27 revenue and adj. EBITDA also expected to be ahead of consensus (adj. EBITDA guidance c. £49m vs. £47.7m consensus). | AMBER/GREEN ↓ (Roland) This is yet another upgrade from this sports nutrition business. It’s a strong story that’s seen the share price (almost) double over the last year. However, the company is also warning of cost inflation and lower margins this year. Sales growth is also expected to ease as the business continues to scale. The combination of slower sales growth and lower margins means that earnings growth is currently expected to slow to much more normal levels this year. APN shares have already re-rated over the last year and now have a ValueRank of just 11. I think it makes sense to moderate our view slightly, while remaining broadly positive. | |
Rockhopper Exploration (LON:RKH) (£631m | SR n/a) | Independent technical report shows that overall gross resource volumes and Net Present Values have increased when compared with the previous independent resource evaluation. Increase of approximately $788 million in the 2P + 2C Net Present Value of the Rockhopper 35% interest in the Sea Lion development. | Currently suspended from trading. | |
Central Asia Metals (LON:CAML) (£298m | SR82) | SP +9% Revenue of $145.5 million, up 46%. Profit before tax of $59.3 million, 203% higher. Cash in the bank of $97.2m. Production on track to meet guidance for FY2026. TSX listing application under way. Cavendish broker forecasts largely unchanged: FY26E adj EPS 42.3c (prev. 42.0c) and dividend of 18p. | AMBER/GREEN = (Roland) [no section below] Copper prices have risen by 50% over the last year to record highs. These results show the benefit of owning a low-cost producer in a high commodity price environment. While this continues, CAML’s core Kounrad copper recovery operation should continue to generate plenty of cash and the company’s decision to spend A$232m on a copper-gold mining acquisition could look clever. If commodity prices fall then the situation could become a little more complex. I’ve previously expressed concerns that the company’s acquisitions may dilute the quality and profitability of the core business. A detailed evaluation of the intrinsic valuation of CAML’s assets is beyond the scope of this report, but in general terms I think the valuation looks reasonable and expect the 9%+ dividend yield to be well-supported by cash generation this year. I don’t see any reason to change my previous broadly-positive view. | |
S&U (LON:SUS) (£239m | SR70) | Total capital receivables up 20% year-on-year. Up-to-date receivables at Advantage at 73% of the book against 69% last year. Total borrowings of £285m compared to £330m of facilities. Major refinancing and securitisation project to be announced in September. | GREEN = (Graham) | |
Aew UK Reit (LON:AEWU) (£168m | SR77) | NAV per share falls from 108.38p to 107.8p. NAV total return of 1.31% for the quarter. 0.11% like-for-like portfolio valuation increase for the quarter. “We remain confident in the outlook for AEWU's strategy.” AEWU confirms that it does not intend to make a firm offer for AIRE. Glenstone, AIRE’s major shareholder, would not support an offer from AEWU. | ||
Camellia (LON:CAM) (£149m | SR90) | SP -4% Camellia’s 50.7%-owned subsidiary, Kakuzi Plc says “our net earnings for the period ended 31st December 2026 may be at least 25% lower than that reported for the year ended 31st December 2025. Exceptionally dry conditions on the farm at the end of 2025 and the Middle East conflict along with a softening of the international macadamia market are anticipated to negatively impact results.” | PROFIT WARNING (AMBER/GREEN =) (Graham) I’m going to leave our AMBER/GREEN stance unchanged today, for balance sheet reasons. At the time of the full-year results, Panmure Liberum estimated that the company would end FY26 with cash and equivalents of £119m. That was before the additional tea estate and artwork disposals announced in recent months. So perhaps the company can have year-end cash in the region of £134m, even after it carries out its capex plans? With that sort of financial fortress behind it, I would be fully GREEN on Camellia if not for today’s profit warning, which does cast some doubt on its ability to generate a meaningful trading profit this year. | |
Andrada Mining (LON:ATM) (£134m | SR30) | The fourth batch of results comprising 14 Diamond Drill holes from the Lithium Ridge Project. “Once again, these exceptional drill results confirm the world-class potential of our Lithium Ridge asset…” | ||
H-Power (LON:HPOW) (£123m | SR13) | LC30 fuel cell generator has received an Attestation of Conformity from TÜV SÜD, the German certification agency. | ||
Brave Bison (LON:BBSN) (£93m | SR34) | Net revenue +98% (not organic). Adj. PBT +120% (£4.1m). Actual PBT £2.1m. “Trading remains in-line with the Board's expectations” with an H2 weighting as previously announced. Will continue to communicate the merits of its proposed takeover offer to System1 shareholders. | ||
Jubilee Metals (LON:JLP) (£81m | SR27) | Preferred purchase selected for $35m Large Waste Project sale. Subject to completion of the legal framework, a $2.25m deposit will be paid for a 45-day period of exclusivity for due diligence. Following successful completion, the buyer will pay the balance of the $35m over an agreed three-year instalment period. This transaction incorporates and replaces the previously-announced sale of 10Mt of waste material from the LWP for $6.75m. | ||
Tpximpact Holdings (LON:TPX) (£77m | SR81) | £19m contract uplift and one year extension secured with HM Land Registry, extending the contract to May 2028. TPX has also secured a new £5m , 30-month contract with the British Library for its manifesto agency to provide digital product development services. No change to Cavendish broker forecasts for FY27 or FY28. | GREEN ↑ (Roland) Today’s wins were already reflected in current forecasts, but the news highlights the positive momentum in the business at present. While historic profitability has been minimal, last year’s results show cash generation underpinning the current valuation and I expect the economics of the business to improve further as it scales. The latest broker earnings forecasts appear to be higher than those shown on the StockReport, implying a FY27E P/E of 10x. I think that’s cheap enough to take a positive view here. | |
Cora Gold (LON:CORA) (£75m | SR24) | Following the signing of a binding term sheet for a $120m gold stream facility in April, Cora has been engaging with West African focused banks with a view to securing $60m of senior debt. The company expects to secure an agreement in due course and has now agreed with the stream provider to extend the deadline for Cora to replace 50% of the stream with senior debt from 15 Dec 26 to the later of 30 Oct 27 or 6 months after the grant of a mining rights permit by the government of Mali. | ||
4Basebio (LON:4BB) (£73m | SR7) | Strategic Collaboration and Marketing Agreement with Genezen | Company has signed a non-exclusive agreement with Genezen, a best-in-class viral vector contract development and manufacturing organization to provide drug developers access to 4basebio's Research Use Only, High-Quality, and GMP-grade hpDNA® technology for starting material for development and clinical programs. | |
Alternative Income REIT (LON:AIRE) (£57m | SR47) | AIRE board comments on Glenstone’s latest offer, noting that it remains “at a material discount” to AIRE’s latest published NAV and provides no certainty on the timing or value of returns that would be delivered by its proposed wind-down. | TAKEOVER | |
Gelion (LON:GELN) (£41m | SR6) | APC ARMD4 programme with QinetiQ provides independent validation of Gelion's NES™ sulfur cathode technology in high-power, drone mission profiles. Li-S batteries constructed using Gelion technology successfully completed “representative drone mission profiles”. | ||
Kendrick Resources (LON:KEN) (£30m | SR17) | Metallurgical test work on the Teufelskuppe project is being carried out by German firm Anzaplan, which will shortly receive three bulk samples from Kendrick’s Bonya REE project for assessment. | ||
Eden Research (LON:EDEN) (£19m | SR15) | Y/E 31 March 26: revenue +14% to £4.9m with increased operating loss of £2.9m (CY24: £2.2m). Secured approval of flagship fungicide product (Mevalone) for control of powdery mildew on grapes in California. Completed a £10.8m fundraise around the year end. FY27 outlook unchanged, but “subject to a number of variables”. | ||
KRM22 (LON:KRM) (£18m | SR14) | New two-year contract for Limits Manager application will deliver ARR of $0.3m and represents a cross-sale with an existing Futures Commission Merchant customer. Group ARR has now increased by £0.5m to £8.0m since 31 Dec 25. | ||
Empresaria (LON:EMR) (£12m | SR72) | H1 revenue flat at £118m with net fee income +10% LFL and adj pre-tax profit +256% to £3.2m. 2026 outlook: pre-tax profit for the full year now expected to be “at least £6.2m”, ahead of previous guidance of £5.2m. Allenby upgraded forecasts: - FY26E adj EPS: 1.1p (prev. 0.5p) | AMBER/RED = (Roland) [no section below] While revenue was flat, lower costs and higher fee income drove a significant improvement in profitability in H1. This is positive, but the group’s unchanged net debt of £17m remains a concern for me – it’s greater than the £12m market cap and implies leverage of 1.7x. That’s not so far below the group’s covenant limit of 2.2x. Perhaps more worryingly, working capital outflows during the half year meant that headroom on the group’s main lending facilities fell to £3.2m at the end of June, from £5.4m at the end of 2025. That seems potentially tight to me for a business with annual revenue of c.£240m. I note that today’s upgraded forecasts from Allenby only indicate a modest reduction in net debt to £16m by the end of this year and still leave the stock priced on a FY26E P/E of 22! On balance, I share Graham’s previous view that this could be a high risk, high reward bet on the company’s new management. However, I’d want to see a stronger balance sheet before considering a more positive view on this micro cap recruiter. | |
Mila Resources (LON:MILA) (£11m | SR23) | Upgraded JORC Resource of 41.3koz Gold at Coffey, Kathleen Valley, based on 599kt at 2.1g/t Au with a 0.5g/t Au cut-off. |
Graham's Section
S&U (LON:SUS)
Unchanged at 1970p (£239m) - Trading Statement - Graham - GREEN =
S&U’s share price has been flat since I covered its trading statement in May:
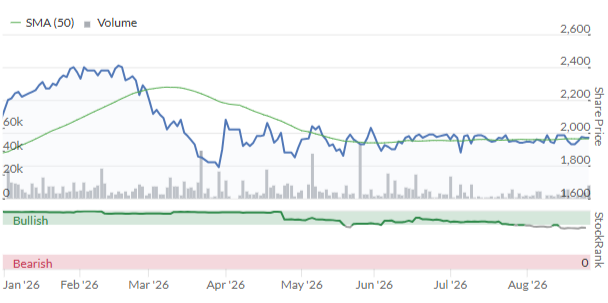
A nice feature of the current market cap is that it’s below last-reported net assets (£249m).
With that context, here are the key points from today’s Q2 trading update, for the period from the beginning of May to the first week of August.
Growth: 20% growth year-on-year in what the company calls “capital receivables”. This is the principal amount of loans outstanding. This includes both car loans (Advantage Finance) and property bridging (Aspen Bridging).
Debt quality: 73% of the motor finance book is up-to-date, compared to 69% last year. Meanwhile in property bridging, “late payers are well within budget”.
Unpicking “up-to-date” vs “collection rate”:
The 73% number deserves comment as it sounds quite alarming, even for a lender to customers with less-then-perfect credit histories.
However, this number is separate to the “collection rate”, which is much higher at 92% (up from 90% last year).
As you can see, there’s a big difference between “up to date receivables” and the “collection rate”.
Let’s compare these metrics with what they were pre-FCA intervention.
At its interim results in 2023 for example, S&U said “with over 50,000 of 64,620 live customers currently completely up to date, Advantage's collecting is both effective and appreciated by its loyal customers.”
So the “up to date” percentage then was about 77-78%. And that was considered very good. The collection rate then was 94%.
In other words, 78% of borrowers were paying on time. Roughly another 16% were paying, but were late.
Therefore, when we hear that 73% of the motor finance book is up-to-date, and the collection rate is 92%, I interpret these as good, but still with some room for improvement to pre-intervention levels.
I got sidetracked a bit there, let’s continue with today’s trading statement. This paragraph is important on funding:
S&U's level of growth has required additional investment of over £100m over the past year. Borrowing now stands at £285m. Although well below existing facilities our prospects for the future require greater, more flexible and competitively priced funding. Hence, S&U's securitisation project is currently reaching its conclusion, which we expect to unveil at our results in September.
Total facilities of £330m are available. In order to keep growing, therefore, requires access to more debt. It’s great that they are proactively working on this and I’m intrigued to learn what this securitisation project might mean for future returns.
Motor finance: deal numbers are up 50% as the company continues to bounce back despite weakness in the overall car finance market. There will be “minimal” financial impact from the latest redress scheme.
Aspen Bridging: “Aspen has seen a period of slower growth” due to the “still somnolent property market”, but late payers are still only 7% of total.
Chairman comment from Anthony Coombs is full of personality, as usual:
"S&U's steady performance reflects the strength of our business through varied economic conditions. As yet another new government sets its course, we are reminded of Abraham Lincoln's enduring dictum - "You don't strengthen the weak by weakening the strong." We remain cautiously optimistic that a pro-growth approach will prevail. S&U will prosper regardless."
Graham’s view
I’ve been GREEN on this as I’m a long-term fan of the business. The major attractions are:
Family owned and family managed, with a very long history.
With the FCA no longer involved, the company is free to grow again.
For the same reason, its metrics are improving as we discussed above.
Trading at a small discount to last-reported book value.
Targeting double-digit ROE, which historically is something it did achieve.
The risks? The only ones I can think of are the obvious ones, which are all to do with the sector it’s in. It’s a lender with exposure to sub-prime borrowers in the highly regulated car market, and to borrowers who need a bridging loan in the property market. So there’s a heady mixture of economic and regulatory risks to deal with.
Personally, I think that the known risks are priced in at the current valuation. Your mileage may vary!
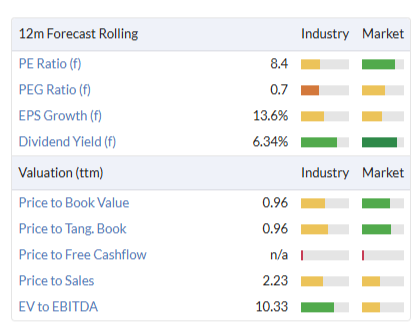
Camellia (LON:CAM)
Down 4.4% at £56.40 (£143m) - Graham - PROFIT WARNING (AMBER/GREEN =)
Kakuzi is pretty small within Camellia: it has 3,700 hectares of mature land in Kenya devoted to tea, macademias, avocados and forestry, in which Camellia has a 50.7% interest. Camellia’s total mature land portfolio is some 48,000 hectares (source: 2025 annual report).
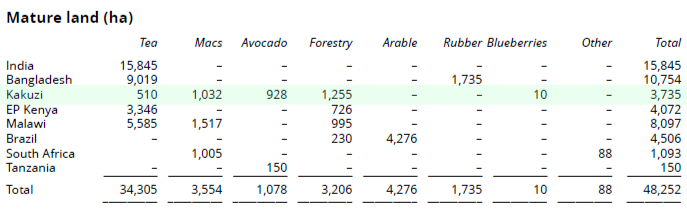
But Kakuzi did make a useful trading profit of some £3.1m in 2025, and this was very important for Camellia as its overall trading profit for the entire group was just £1m. That makes today’s profit warning quite unfortunate, but I wouldn’t blow it out of proportion. There are many other subsidiaries that can potentially pick up the slack.
Graham’s view
I’m going to leave our AMBER/GREEN stance unchanged today, for balance sheet reasons (and also because we haven’t looked at Camellia in a while, so I don’t feel like I “have” to downgrade our most recent stance on the back of a profit warning).
The company reported 2025 year-end net cash of £133.6m.
Since then it has paid a £5.6m dividend but also made some major disposals: about £15m by the time the full-year results were published (but not included in the year-end cash figure), and another c. £15m since then.
There was the £1.5m sale of a tea estate in late May, and the £14m sale of South Asian art in June.
In other words, we can add about £30m onto that 2025 year-end figure, minus the dividend.
But be warned: heavy capex of c. £29m is planned for 2026.
At the time of the full-year results, Panmure Liberum estimated that the company would end FY26 with cash and equivalents of £119m. That was before the additional tea estate and artwork disposals. So maybe the company can have year-end cash in the region of £134m, even after it carries out its capex plans?
With that sort of financial fortress behind it, I would be fully GREEN on Camellia if not for today’s profit warning, which does cast some doubt on its ability to generate a meaningful trading profit this year. But it’s not much of a stretch to say that the agricultural assets of the company are almost thrown in “for free”, considering the amount of cash at hand.
The StockReport has also noticed the value on offer and calls it a Super Stock:
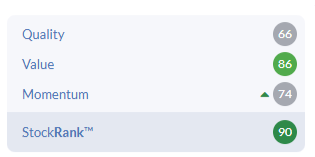
I’d sum this up as an adventurous idea that might reward detailed research
Roland's Section
Applied Nutrition (LON:APN)
Down 1% at 319p (£825m) - FY26 Trading Update - Roland - AMBER/GREEN ↓
One of the main themes we highlighted in the recent webinar was the power and persistence of strong earnings momentum. Today we have another example of this, with upgraded FY26 and FY27 guidance from sports nutrition brand Applied Nutrition.
FY26 year-end update: ahead of expectations
Today’s update covers the year ended 31 July 2026. It’s brief, but positive:
Following June’s update (see here), trading has remained strong “across the Group’s markets and channels”. Excluding any contribution from the Nutrablend acquisition in June, FY26 adj EBITDA is expected to be up by 40% to c.£43.3m, ahead of consensus (£42.0m).
FY26 revenue rose by 50% to £160m, ahead of consensus (£148.4m).
Year-end net cash (excluding leases) was £15.9m.
While this upgrade is certainly positive, I think it’s worth noting that today’s guidance also implies that Applied Nutrition’s FY26 EBITDA margin will be c.27%, down from June’s guidance of c.28%.
FY27 outlook: ahead of expectations
Strong sales momentum is expected to persist, prompting management to upgrade guidance for the current year:
FY27 revenue is expected to rise to c.£205m, ahead of previous consensus of £186.2m.
FY27 adj EBITDA is now expected to rise by 13% to approximately £49m, ahead of previous consensus of £47.7m.
The trend of falling margins is expected to continue into FY27 – these figures imply the group’s EBITDA margin will fall to 23.3% during the current year.
The company provides some comment on this in today’s update (my emphasis):
FY27 EBITDA margin is expected to decrease slightly from FY26 levels. This reflects an increased revenue contribution from the US, together with significantly higher whey protein costs and a greater proportion of sales from whey-based products, partly following the very successful relaunch of Critical Whey in FY26.
The rising cost of whey protein is a broader issue affecting most companies in this sector. Demand for whey protein has soared to meet demand for protein-enhanced products, bolstered by demand for weight-loss drugs.
My understanding is that whey protein prices have roughly doubled over the last 12 months.
Today’s updated broker forecasts suggest the group’s operating margin could fall by 3% to 4% this year. Personally, I am not sure I would describe this as a slight decrease (as the company does). In my view, it’s more material than that.
Updated broker forecasts
With thanks to brokers Panmure Liberum and Cavendish, we have access to two updated sets of forecasts today. Assuming other brokers covering Applied Nutrition make similar changes, these new forecasts suggest that an an earnings level, today’s upgrade is actually quite modest:
| Forecast | Panmure Liberum | Cavendish | Previous StockReport consensus |
|---|---|---|---|
FY26E adj EPS | 12.0p (prev. 11.6p) | 12.4p (prev. 12.0p) | 12.1p |
FY27E adj EPS | 13.1p (prev. 12.8p) | 13.5p (prev. 13.1p) | 13.5p |
Roland’s view
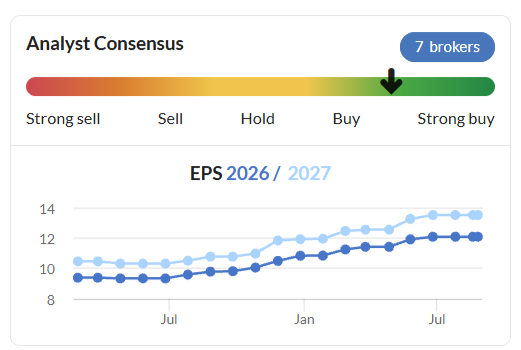
This business has repeatedly upgraded earnings forecasts repeatedly over the last year. Using the mid-point of the new forecasts above, FY26 estimates have risen by 25% in 12 months::
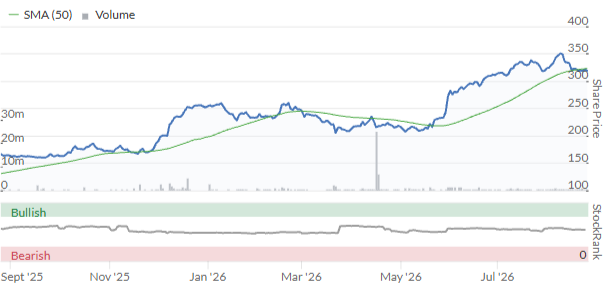
Applied Nutrition’s share price has also made progress over the last year, gaining just over 90%:
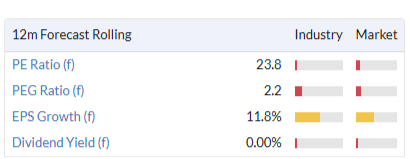
When a share price rises more quickly than underlying earnings estimates, we say the stock has re-rated to a higher valuation. In this case, Applied Nutrition’s rolling forecast P/E is currently about 23x, up from 17x one year ago:
Graham was GREEN on Applied Nutrition in June and this appears to have been a correct call – the company has upgraded its earnings guidance again less than three months later.
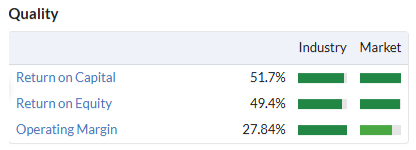
Excellent quality metrics paired with double-digit growth rates appear to justify a premium valuation:
However, the market isn’t feeling the love for today’s upgrade. After an initial bounce when the market opened, Applied Nutrition’s share price has actually fallen today.
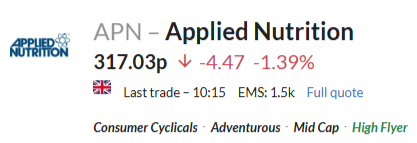
I think the explanation for this lacklustre reaction is probably the unfortunate combination of slower sales growth and falling margins that’s now expected over the next year.
Revenue is expected to rise by 28% in FY27, compared to an increase of 50% in FY26. While 28% is still an excellent growth rate, it’s well below the company’s five-year average rate of 45%.
Slower revenue growth plus lower margins mean reverse operating leverage will kick in – profit growth is expected to be significantly lower than sales growth this year:
FY26E adj EPS growth: c.33%
FY27E adj EPS growth: c.10%
The trend of slower sales and profit growth is expected to continue into FY28. PanLib’s forecasts suggest revenue growth will fall to 10% next year, with EPS growth falling to around 7.5%.
I think the situation is summed up quite fairly by the StockRanks:
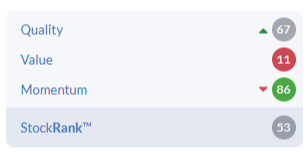
I think the opportunity here is that sales growth will exceed expectations. If that happens, it could cancel out any weakness in margins and result in earnings ahead of current forecasts.
That seems to have been what’s happened in FY26 – despite margins falling since June, profits are still expected to be higher than previously guided.
The question is how quickly the supply-demand balance for whey protein will ease – and whether Applied Nutrition can continue to build higher-margin market share with its branded products, without becoming too dependent on lower-margin white label production (the focus of the recent Nutrablend acquisition).
I don’t know the answer to this, but my impression is that this is an increasingly competitive market where a certain level of commoditisation is likely. That may not bode very well for pricing power, unless brands can demonstrate genuine differentiation – not necessarily easy.
My personal impression from researching nutritional supplements in a different area of the market recently is that this is mostly a marketing game. With the exception of a few premium brands, there seems to be very little differentiation – and even less evidence to support it.
While I think Applied Nutrition is a decent business, I am not sure it has the combination of value and competitive advantage that’s needed to justify a fully positive rating following today’s update.
For these reasons, I’m going to move our view down by one notch to AMBER/GREEN today.
Tpximpact Holdings (LON:TPX)
Up 8% at 87p (£82m) - Contract Wins and Uplifts Totalling £24m - Roland - GREEN ↑
Today’s update is the second big contract update announced in the last month. Mark commented on the previous deal on 13 August, noting that it was already in broker forecasts, according to Cavendish.
Does today’s deal move the needle?
Here are the main details:
HM Land Registry: £19m contract uplift
TPXImpact was appointed as the Land Registry’s “primary Digital, Data, and Technology (DDaT) Delivery Partner” on a four-year contract in May 2023. This deal has now been extended by one year until May 2028.
British Library: £5m contract win
The Group's digital experience agency, manifesto, has recorded its largest ever win, having been selected as the successful bidder to provide digital product development services for the British Library as part of its landmark Future Web Programme.
This contract has an initial value of £5m over a 30-month term, with options to extend.
Outlook & Broker Estimates
Thanks to Cavendish again, we learn that this revenue was already included in current forecasts:
Forecasts are reiterated with improved visibility through latter FY27 and FY28.
In fairness, the broker does suggest that the prospect of upgrades to FY27 and FY28 forecasts is improving, given the evident momentum in contract wins.
I think it’s also worth highlighting that Cavendish’s latest forecasts are significantly higher than the StockReport EPS estimates, which I think may be stale.
Cavendish is the company’s NOMAD and house broker, so its estimates should be a reasonable guide to management expectations – I would be inclined to rely on these figures:
FY27E adj EPS: 8.3p
FY28E adj EPS: 10.3p
These estimates put TPXImpact on a FY27E P/E of 10.3, falling to a P/E of 8.4 in FY28.
Roland’s view
Mark was AMBER/GREEN on 13 August, noting that only the lack of a profitable trading history was preventing him from taking a fully positive view.
While today’s update hasn’t triggered a broker upgrade, the trend is certainly positive here – FY26 EPS forecasts have risen by 80% over the last year (using the Cavendish estimate above):
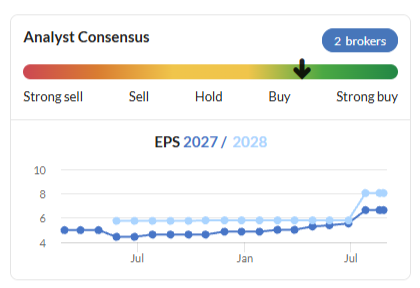
Can I make the leap to GREEN today? I think there are some points in TPXImpact’s favour:
Based on recent and forecast earnings, I think the valuation remains very reasonable.
Last year’s profits were backed by solid free cash conversion, giving the stock a c.5% free cash flow yield on historic earnings. Broker forecasts suggest this positive cash performance will continue this year, supporting a year-end net cash position for the first time.
Positive operating leverage: profit margins are expected to improve as the group’s cost base is spread across a larger revenue base.
In addition to weak historic profitability, the main risks I can see relate to client concentration and the group’s dependence on large but potentially lumpy government contracts.
In FY26, 90% of revenue came from public sector clients, with 70% from the Central Government. The top five clients contributed 60% of revenue with the top 10 contributing c.75%.
In the company’s defence, client retention seems strong, with 75% of FY26 revenue coming from customers of at least three years’ standing. This suggests that customers are relatively happy with the company’s services.
What do the StockRanks say? TPXImpact has High Flyer styling, with excellent momentum, strong quality and weak value:
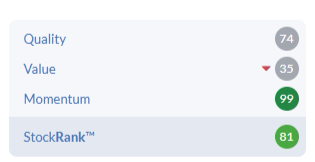
I would speculate that if performance remains on track, these quality and value scores might improve following the company’s half-year results later this year.
As things stand, I think that last year’s results underpin most of the current valuation. I would expect the economics of this business to continue improving as it scales.
More broadly, I think that there’s likely to be a structural growth trend in public sector IT spending over the coming years, so well-positioned companies could benefit for some time to come.
While I recognise the risks relating to the group’s dependence on the UK public sector, I think this could be an interesting GARP situation – growth at a reasonable price. I’m going to upgrade our view to GREEN today.
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.