
Good morning and happy Friday!
News has been quiet overnight, but one interesting piece of corporate news is that Stripe and private equity firm Advent have reportedly given up on their planned takeover of PayPal Holdings (NSQ:PYPL).
Paypal shares are lower by 14.6% in overnight trading, but still higher than they were before the proposal was officially announced in July.
Stripe is valued at about $159 billion in the private market, c. three times PayPal’s market cap. I imagine that it envied PayPal in its early years - but it's now a far more successful business.
Overnight market movements:
The FTSE is up 0.1% at 10,810
S&P 500 is down 0.1% at 7,720
Brent crude (November) is down 0.4% at $88.20/bbl
Gold is down 0.6% at $4,575/oz
Bitcoin is down 0.5% at $79,700
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
HUTCHMED (China) (LON:HCM) (£1.62bn | SR16) | New Drug Application for fanregratinib has been granted conditional approval by the China National Medical Products Administration for the treatment of adult patients with intrahepatic cholangiocarcinoma. | ||
Goodwin (LON:GDWN) (£1.37bn | SR32) | Revenue £280m (2025: £220m). Operating profit £78.6m (2025: £37.1m). Dividend to increase 18% to 330p. “The proposed disposal includes Goodwin Steel Castings Limited, Goodwin International Limited, Noreva GmbH, Easat Group and Pumps. The sale process is progressing well…” | AMBER = (Graham) | |
Caledonia Mining (LON:CMCL) (£363m | SR61) | Blanket Mine M&I Resources Increases by 22% & Maiden Mineral Resource Estimate at Motapa | Blanket: 22% increase to the underground measured and indicated mineral resource estimates to 2.178 million ounces of gold. Motapa: Maiden measured and indicated mineral resource estimate of 7.8 million tonnes at a grade of 1.51 g/t, containing 379,000 ounces of gold at a cut-off grade of 0.5 g/t. | |
Halo Minerals (LON:HALO) (£358m | SR8) | AIM admission raised £4m. Continued advancement of the Company's flagship Playa Verde copper and gold tailings reprocessing project in Chile. | ||
McBride (LON:MCB) (£291m | SR84) | Strategic partnership securing two long-term contract manufacturing agreements with E.H. Group B.V. ("Vestacy"), the global home care company behind brands including Air Wick, Calgon, Cillit Bang and Mortein. Transaction to be materially earnings accretive. | ||
Andrada Mining (LON:ATM) (£139m | SR30) | Financial Results For Year Ended 28 Feb 2026 & Board Changes | Revenue up 34%. Operating loss improved to £2.6 million (FY2025: loss of £3.9 million). Operating Cash Flow increased by £8.7m to £4.7m (FY2025: loss £4.0m). “Andrada enters the next phase of its development from a materially stronger position.” Changes to NEDs on the Board. | |
Somero Enterprises (LON:SOM) (£124m | SR94) | SP +6% Amendments to the company’s bylaws (bringing them closer to UK standards). Search ongoing for a new NED. Executive Vice President of Sales will transition from the Board and assume the title of Chief Commercial Officer. | AMBER/GREEN = (Graham) [no section below] I'm leaving Roland's AMBER/GREEN stance from July unchanged. But it's worth noting the scale of investor dissent here, after all resolutions at the June AGM saw a majority of votes against them. As Somero is a Delaware company, some of these resolutions managed to get passed anyway (the resolutions for the re-election of Directors). Somero said that the other resolutions, such as those ratifying the Annual Report, did not need to be passed under Delaware law anyway. Today's announcement helps to bring Somero in line with some UK governance standards, which means that future nominees will need a majority of votes rather than merely a plurality. I continue to have doubts about Somero's competitive positioning, but I don't see any need to adjust our stance on the back of today's update. | |
Borders & Southern Petroleum (LON:BOR) (£109m | SR60) | Welcomes the recent news from Navitas and Rockhopper regarding the accelerated development of Sea Lion. | ||
Everyman Media (LON:EMAN) (£51m | SR56) | New NED as another steps back for health reasons. “The Board continues to engage with stakeholders regarding the potential cancellation of trading in the Company's ordinary shares on AIM… A further announcement in relation to a Delisting is expected to be made in due course.” | RED = (Graham) I continue to view this as a "Heads we win, tails you lose" situation, with the threat of a delisting looming over small shareholders. We first learned of the desire of several board members to delist the company in June. What's odd is that the company might finally be about to post some good results, e.g. the H1 update in July showed admissions up by over 20% and adjusted EBITDA up by 32%. The statutory numbers at Everyman have always been poor but I'm wondering if that might be about to change - and if there could be some connection between that and the timing of the delisting proposal. Whatever the truth of the matter, I think it's generally the right call to avoid a stock where the directors and the major shareholders no longer want it to be listed, unless we are truly content to own unlisted shares. So my RED remains in force. | |
Watkin Jones (LON:WJG) (£46m | SR38) | SP -8% “…the Group has been engaged with investors on a small number of transactions with the potential to conclude in Q4… the Board has concluded that it is now unlikely that all of these transactions will be finalised by the year end. As a result, the Group is expected to deliver adjusted operating profit for the full year at a similar level to H1.” | PROFIT WARNING (AMBER/GREEN=) (Graham) | |
System1 (LON:SYS1) (£43m | SR67) | “The Board does not see the Revised Offer or the Alternative Offer as representing an acceptable fair value for all shareholders and, as a result, the Board of System1 continues to unanimously and unequivocally reject the Cash and Share Offer and the Alternative Offer.” | TAKEOVER (rejected by the Board) (Graham) [no section below] | |
Kr1 (LON:KR1) (£24m | SR15) | Aggregate infrastructure income (year-to-date, unaudited): £587,625. NAV £31.4m, NAV per share 17.7p as of July 2026. | ||
FIH (LON:FIH) (£23m | SR52) | Revenue from continuing operations of £37.4 million (up £0.8m). Pre-tax loss from continuing operations was £2.9 million (2025: £7.2 million loss) including non-trading items. Underlying pre-tax loss £0.3m. Post-year end, announced a £7.6m disposal. | ||
Power Metal Resources (LON:POW) (£14m | SR40) | On-site work has now commenced at POW’s 100% owned Tati Gold Project located on the Tati Greenstone Belt near Francistown, Botswana. | ||
Tekcapital (LON:TEK) (£9m | SR45) | Guident CORP, a leader in autonomous vehicle remote monitoring and human-in-the-loop operations, has announced a strategic collaboration with Florida State College at Jacksonville. | Reach announcement - non regulatory press release. |
Graham's Section
Watkin Jones (LON:WJG)
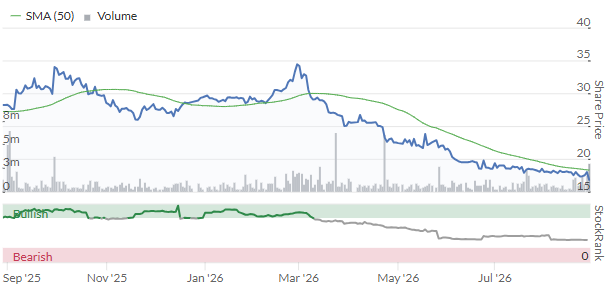
Down 8% at 16.55p (£43m) - Graham - PROFIT WARNING (AMBER/GREEN =)
I already looked at this at the end of July, saying (if you can forgive me for quoting myself):
Despite my lack of confidence in the ability of the company to hit forecasts, I’m inclined to leave our AMBER/GREEN stance unchanged here. My reasoning is simple: our AMBER/GREEN stance, at least as far as I’m concerned, is a view on the balance sheet, not earnings.
The share price that day was 18.2p.
The company said then that it was working on “a small number of transactions”, and that these would have to conclude in Q4 (i.e. by the end of September) in order for the company to grow its operating profit in H2. This seemed highly uncertain, and I assumed there was “at least a 50% chance of a profit warning”.
Surprise, surprise: today we have that profit warning.
As set out in the Q3 trading update, the Group has been engaged with investors on a small number of transactions with the potential to conclude in Q4. Whilst investor engagement in each of these schemes remains active, the Board has concluded that it is now unlikely that all of these transactions will be finalised by the year end. As a result, the Group is expected to deliver adjusted operating profit for the full year at a similar level to H1.
Adjusted operating profit in H1 was only £0.4m, and so the company is not going to generate very material profits this year.
(One bright spot in the H1 report was the lack of any adjustments - hopefully we’ll see the same in the full year?)
You could be forgiven for thinking that the delayed transactions will go straight into the FY27 result, and that FY27 forecasts should therefore be raised on the back of this update. This rarely happens in practice - but I'd still hope that FY27 would be slightly more resilient.
Estimates at Progressive have been reduced. Revenue gets cut all the way from £272m to £223m, and adj. operating profit gets cut from £6m to around breakeven.
A few other titbits from today’s update:
Provisions:
We have made further progress on our building safety rectification obligations with four projects currently on site of which two buildings are expected to be completed in FY26. The Group's provision will continue to be kept under review, reflecting ongoing building investigations and discussions with owners and supply chain.
The company’s building safety provision was £38m at the interim result, after being discounted to its present value. It’s expected to be incurred over four years. This is a legitimate source of uncertainty. WJG said it was “in discussions with a number of property owners whereby the legal responsibility or confirmation of fire safety remediation requirements remains uncertain”.
Cash: year-end net cash is expected to end FY26 above the £61m figure at the half-year report. Progressive had a £76m forecast, which they have today reduced to £63m.
Graham’s view
At a market cap of only £43m today, I’m going to ignore the profit warning as far as our colour rating is concerned.
I very rarely do this. Here at Stockopedia, we respect PEAD (post-earnings announcement drift). Positive surprises lead to positive drift, and negative surprises lead to negative drift.
But as I said one month ago, I no longer think that earnings are particularly relevant for Watkin Jones, at least not in the short-term.
It’s true that eventually, it will need to either earn a real profit or return capital to shareholders.
But as far its fundamental value is concerned, this is primarily a balance sheet play, in my view.
Net cash exceeds the market cap. If we deduct the present value of the building safety provision from the cash forecast, we are still left with a “net net” cash figure of £25m.
But cash is not the only asset on the balance sheet. The March 2026 figures showed the company having equity of £125m, of which only £10m was intangible. Indeed, most of the company’s assets are considered "current" and have real, easily measurable value: there's £92m of inventory/work-in-progress, £28m of "contract assets", £29m of receivables, etc.
Therefore, I’m going to leave this stubbornly on AMBER/GREEN. I’m not fully GREEN because any deep value investment can require a lot of patience, and it’s not clear to me what the catalyst might be for the share price to start reflecting fundamental value here.
There’s also some uncertainty around building safety provisions, which could eat into a chunk of value.
But overall, I continue to like this as a deep value play. Today’s profit warning doesn’t come as a surprise, so I don’t see why I should have to change stance.
It's an ugly chart, which goes with the territory when it comes to deep value investments:
Goodwin (LON:GDWN)
Up 7% at £194 (£1.46bn) - Graham - AMBER =
There are some excellent comments today from readers, including from John Smith who points out the slightly bizarre sequence of events here in terms of news flow.
Goodwin is a family-owned engineering business. Many value investors (including myself) love family businesses. We like businesses where the founders, or their descendants, continue to own and run it. This can help to create a wonderful alignment between management, the Board and external shareholders. Everybody is in it for long-term success rather than short-term gains.
But there are downsides to this, and I think Goodwin helps to highlight one or two of them.
There is no question that it has been a roaring success for its shareholders over the long-term.
But over the last year, strange communication has created an (unnecessarily?) volatile share price chart:
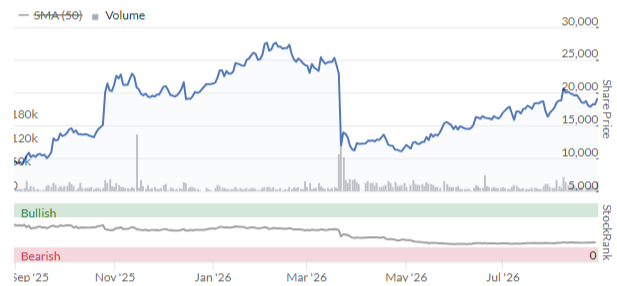
“Buy-and-forget” investors won’t have worried about this too much. But most of us feel like we want to have some idea about how our investments are doing. And in the case of Goodwin, unorthodox communication created an information vacuum in which confusion reigned.
This is a business which eschews providing investors with normal forecasts:
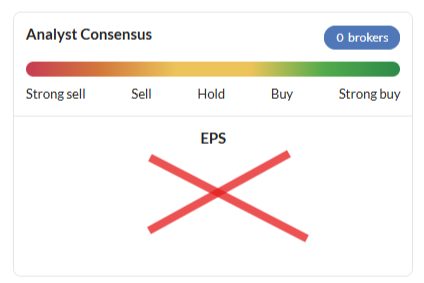
Personally, I don’t have a big problem with that. But it does mean that anybody getting involved here needs to accept that neither the company itself, nor the City, might help you very much to understand what results might look like from one year to the next.
The announcements to the LSE are all we are given, and anything else you need to work out for yourself.
And if these announcements are all you rely on, you could be forgiven for being confused.
In March, the company announced a horrible profit warning. The share price crashed 35%, to £150 per share - given that this company’s worth is now measured in the billions, it was a pretty significant financial event!
Maybe TJW Goodwin got up on the wrong side of bed the day he wrote that trading update, but there was barely even a sliver of good news to be found in that update. The Iran war was not even a month old at the time - maybe he was particularly worried about that? He even suggested cutting the dividend policy, “given the escalating Gulf situation and the broader economic environment.”
Fast forward to today’s results for FY26, and we get the following:
Revenue up 27% to £280m
Trading profit up 118% to £77.5m (the company did previously tell us that this would be in excess of £71m).
Dividend up 18% to 330p.
And everything is rosy in the garden:
Whilst there has been growth in all our manufacturing companies, the Mechanical Engineering division in particular has continued to experience a substantial increase in customers' demand for precision-machined, high-integrity castings into mission critical defence and nuclear applications… Goodwin has positioned itself to be a leading supplier on many UK and US Navy frigate and submarine programmes.
Disposal: the company acknowledged earlier this month that it was looking at options including “the potential sale of a substantial part of the Mechanical Engineering Division".
There’s an important update on that front today:
The significant improvement in the performance of the Mechanical Engineering division… has substantially enhanced its strategic value and generated considerable external interest… the Board committed to pursuing a potential disposal of a substantial part of the Mechanical Engineering Division and appointed Rothschild & Co as its financial adviser to initiate an active sale process of its constituent business units… The proposed disposal includes Goodwin Steel Castings Limited, Goodwin International Limited, Noreva GmbH, Easat Group and Pumps.
This looks to be the majority of the entire group.
With Mechanical now classified as a “discontinued operation” (because it’s up for sale), the company breaks out its FY26 performance as follows.
Continuing operations (Refractory & Technological): revenue £69m, trading profit £10m.
Mechanical: revenue £211m, trading profit £67m.
As you can see, without Mechanical, Goodwin would be left with a much smaller and less profitable group. They say that they would have “a simpler, more focused portfolio of specialist businesses with strong market positions and attractive long-term growth prospects”.
Net debt: £29m, after paying out a £40m dividend.
Outlook: no outlook statement, as usual.
Estimates: no estimates. Shore Capital provides some coverage, but not in a forward-looking manner.
Graham’s view
I raised our stance on this to AMBER when news of the potential disposal was confirmed. They have a target to complete this transaction in the next 12 months. I'm guessing there could be some large, well known defence/industrial concerns examining this opportunity.
As far as my stance goes, I don’t think I can do better than AMBER on this again today.
Earnings per share for FY26 are 738p, which puts the shares on a trailing P/E multiple of 26x.
The FY27 outlook presumably remains clouded by the issues raised in the March update.
The wildcard is the potential disposal price for the Mechanical division. What might a suitor pay for this? Presumably quite a lot, if external interest has motivated the company to sell. But I don’t really believe in buying shares just because a takeover is considered likely, especially when any potential takeover price is still a mystery.
So for me, the picture here remains as cloudy as ever, and the colour is AMBER.
The StockRank takes a harsher view, calling it a Falling Star:
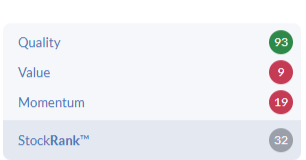
Goodwin may reward detailed research, and it has rewarded its long-term shareholders handsomely for many years. But for me, I’m afraid that it remains inscrutable.
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.