
Watchers of Boohoo (LON:DEBS) and Asos (LON:ASC) may be interested to see that SHEIN Global Holdings (HKG:625) is now listed in Hong Kong, as of last night.
Shein initially attempted to list in the United States, and then in the UK, but both of these efforts failed. Instead, its shares have found a home in Hong Kong.
While this is a blow to the investment bankers in London who might have worked on the deal, and to the City in general, perhaps it is a reasonable compromise Shein’s products are manufactured and sourced in mainland China, and Chinese regulators did not want the company to list abroad.
The valuation is also a compromise: an IPO market cap of just $26.5 billion, far lower than the almost $100 billion valuation that Shein achieved in private funding rounds back in 2022. The shares have fallen by 8% in their first session.
Overnight market movements:
The FTSE is unchanged at 10,770
S&P 500 is unchanged at 7,690
Brent crude (November) is up 0.5% at $90.95/bbl
Gold is down 0.1% at $4,440/oz
Bitcoin is up 0.4% at $79,150
Roland Head joins me today.
Leaving it there, thank you. Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
AstraZeneca (LON:AZN) (£186bn | SR51) | Tagrisso plus Orpathys demonstrated statistically significant and highly clinically meaningful improvement in progression-free lung cancer survival. | ||
GSK (LON:GSK) (£75bn | SR83) | Positive phase II data for GSK’s mRNA seasonal influenza (flu) vaccine candidate. | ||
Bunzl (LON:BNZL) (£9.1bn | SR93) | Underlying revenue growth 3.2%, adjusted operating profit +8% at constant exchange rates (£440.6m). 2026 outlook upgraded; continue to expect modest underlying revenue growth, and now expect operating margin to be broadly flat year-on-year. | ||
Frasers (LON:FRAS) (£3.7bn | SR95) | “Frasers' current intention is to further increase its interest in HUGO BOSS… with the objective of taking an interest in excess of 50.00%... Frasers is currently reviewing whether it continues to support Mr. Stephan Sturm in his position as Chairman.” | ||
Old Mutual (LON:OMU) (£2.45bn | SR63) | Life APE (annual premium equivalent) sales increased by 21%. Gross written premiums +3%. Profit result from operations in H1 expected to increase by 2% to 12%. | ||
HUTCHMED (China) (LON:HCM) (£1.58bn | SR14) | Positive high-level results from the SANOVO China Phase III trial in treatment-naïve patients with locally advanced or metastatic non-small cell lung cancer. | ||
Bodycote (LON:BOY) (£1.55bn | SR82) | Cash offer of 940p per Bodycote share from Veritas, including a 7.2p interim dividend. This represents a 36.5% premium to the volume-weighted average price for the three months to 21 May 2026 (the undisturbed period prior to the start of bid speculation). | TAKEOVER (Graham) | |
Gamma Communications (LON:GAMA) (£1.02bn | SR77) | SP +1% | TAKEOVER (Graham) [no section below] | |
A.G. Barr (LON:BAG) (£668m | SR54) | Appoints Darren Shapland as an independent NED and Chair of the Board. He currently serves as the Non-Executive Chair of Hollywood Bowl Group and as an independent NED at JD Sports. | ||
Acceler8 Ventures (LON:AC8) (£609m | SR20) | Hui10 Inc. has commenced the rollout of its Sports Lottery+ platform following its successful deployment in Hohhot, Inner Mongolia. An enhanced consumer lottery experience. | ||
ACG Metals (LON:ACG) (£479m | SR53) | "Producing our first copper concentrate marks ACG's transition into a copper producer and is a defining milestone for the Company.” | ||
Central Asia Metals (LON:CAML) (£316m | SR87) | Conditional approval from the Toronto Stock Exchange for the listing of shares in CAML on the TSX, including the new shares that will be issued to the shareholders in Cygnus Metals Limited. | ||
Ashtead Technology Holdings (LON:AT.). (£280m | SR46) | Revenue +1.1%. Adjusted EBITA down 7.3%. PBT down 1.5% (£17.5m). “The Board's expectations for the full year are unchanged from our trading update on 20 August 2026.” | AMBER = (Roland) Today’s results follow a profit warning 12 days ago, so I wasn’t expecting any further surprises. The company clarifies today that its recent comments on project delays in Europe and the Americas reflected scheduling delays only, not a change in market conditions. My review of the numbers confirms that the profitability of this business remains at attractive levels and I think Ashtead could offer value based on historic profits. I’m staying neutral today to reflect the negative trend in EPS forecasts and the potential for further knock-on impact from events in the Middle East. I do think this could be a business worthy of further research, though. | |
Capricorn Energy (LON:CNE) (£245m | SR95) | Cash offer of US$5.214 per Capricorn share, including a $0.99 special dividend. This offer is equivalent to 384p per Capricorn share and represents a 45% premium to the closing price on 10 March 2026 (the undisturbed share price). It’s a 10% premium to the previous Genel offer for Capricorn. | TAKEOVER | |
Serabi Gold (LON:SRB) (£244m | SR95) | CFO has decided to step down, taking effect 28th August. He is thanked for 13 years of service. Nick Box has been appointed interim CFO with effect from 28th August while SRB searches for a permanent successor. | ||
Dialight (LON:DIA) (£224m | SR82) | “Whilst there remains a significant proportion of the financial year still to be delivered, based on performance to date and the current outlook, the Board now believes the Group's adjusted profit before tax for the financial year ending 31 March 2027 is likely to be significantly ahead of its' previous expectations.” | AMBER/GREEN ↑ (Roland) Some of our previous concerns with this business have been addressed since our last view in January. Current momentum seems strong, with a number of EPS upgrades over the last 12 months. However, visibility appears relatively limited and the stock now trades on a FY27E P/E of 27. As a result, I am unsure of the value on offer here without more insight into the company’s end markets and order book. I’m upgrading to AMBER/GREEN today to reflect Dialight’s improved balance sheet and evident momentum. But I would be quick to turn neutral if future updates suggest any sign of a slowdown. | |
Beeks Financial Cloud (LON:BKS) (£150m | SR33) | Signs a multi-year agreement with the Stock Exchange of Thailand for the deployment of Beeks' Exchange Cloud® platform across the SET market. | ||
Mkango Resources (LON:MKA) (£146m | SR1) | Half Year 2026 Results & Mkango Completes Acquisition of Remloy | Cash position of US$13.6m as of June 2026. Minimal sales, $3m loss. “Mkango is now uniquely positioned across the whole rare earth supply chain in Europe and North America…” Has now completed the acquisition of the Remloy rare earth magnet recycling business from Heraeus Amloy Technologies GmbH for €8m. | |
Michelmersh Brick Holdings (LON:MBH) (£68m | SR68) | Revenue -9.5% to £32.4m with gross margin +3.4% to 37% and pre-tax profit -3.4% at £2.8m. Outperformed UK market, with despatch volumes down c.2% vs -9% for the UK market. Outlook: “trading within full year market expectations”, but “remain watchful of the impact” of political uncertainty in the UK and the conflict in the Middle East. | AMBER = (Roland) Michelmersh’s house broker has cut its earnings forecasts today and noted an H2 weighting to profits. My reading of the company’s commentary is that there’s still some risk that H2 results could miss forecasts. The underlying issue is that the timing of a housing market recovery remains uncertain and seems to keep slipping back. Until momentum improves, Michelmersh’s profitability is likely to remain under pressure. I think the stock offers value at current levels, but I’m staying neutral today to reflect the negative earnings trend and the possible opportunity cost of entering the trade too early. | |
Ondine Biomedical (LON:OBI) (£66m | SR12) | The trial met its primary efficacy endpoint. Nasal photodisinfection in addition to standard of care was associated with an estimated 40% relative reduction in 30-day surgical site infections compared with standard of care alone in the primary analysis. No treatment-related serious safety concerns were identified. | ||
Taylor Maritime (LON:TMI) (£52m | SR92) | Sold three vessels for gross cash consideration estimated at $48.6m. Completion is expected in Q3 2026, with net sale proceeds expected to be returned to shareholders through a compulsory partial redemption of shares. These disposals will leave the company with two remaining vessels. | ||
Chariot (LON:CHAR) (£49m | SR42) | Chariot has signed an agreement to provide services and support to Etu Energias in its acquisition of an additional 31% working interest in Block 14 and 15.5% interest in Block 14K offshore Angola. In return for services and support, Chariot will benefit from future cash flows equivalent to c.4,000 bopd. | ||
Oxford Metrics (LON:OMG) (£44m | SR47) | Captive Devices is a “specialist provider of facial capture technology”, producing head-mounted camera systems and software that enables markerless facial performance capture. Captive generated revenue of £0.5m for the year to 30 April 26 and is being acquired for up to £0.75m in cash, equity and performance-based earn-out. | ||
Novacyt SA (LON:NCYT) (£30m | SR32) | Novacyt has entered into a collaboration agreement Illumina (NSQ:ILMN) for an initial five-year term. The Agreement establishes a framework under which the parties may explore potential future collaboration in areas of mutual interest, subject to separate written project agreements. | ||
Europa Oil & Gas (Holdings) (LON:EOG) (£24m | SR25) | The longstop date for completion of the transaction with Fuhai Group has been extended to 30 Sept 26 by mutual agreement. Further data requests from the Chinese authorities have delayed approval. | ||
East Star Resources (LON:EST) (£24m | SE12) | East Star has formed a JV with Nova to develop the Rulihka copper project in Kazakhstan. The JV will appoint Orion Development Ltd as Rulikha operator. East Star will retain at least 25% exposure to future production without any up front cost. | ||
Great Southern Copper (LON:GSCU) (£21m | SR7) | Artemisa North scout RC hole RC009 tested beneath artisanal workings with oxide copper and intersected 106m @ 0.33% Cu and 42 ppm Mo from surface. “This outstanding result for hole RC009 has greatly exceeded our expectations for the reconnaissance drilling programme …” | ||
Ampeak Energy (LON:AMP) (£19m | SR13) | JBR Energy Holdings (an SPV of Jones Bros) has acquired a 24.7% equity stake in AW1 Storage Holdings from Ampeak for £7.8m, comprising £3.9m in equity and £3.9m for the purchase of a shareholder loan. £3.9m of the funds raised have been ringfenced for the AW1 expansion project, on which Jones Bros is the principal contractor. | ||
Renalytix (LON:RENX) (£18m | SR12) | Announced partnership with US firm Quest Diagnostics to make kidneyintelX.dkd blood testing available to physicians and patients served by Quest in the United States. Renalytix intends to raise £9.5m through a placing and retail offer at 6p (a 44.6% premium to the most recent closing price). Shares will be suspended this morning, pending an announcement. | ||
Sancus Lending (LON:LEND) (£14m | SR53) | AUM rose to £339m (31 Dec 25: £307m) with revenue +36% to £13.1m. The H1 operating loss increased to c.£(3.4)m, compared to £(0.9)m last year. The company blames macro factors but also notes higher operating expenses, an increase in bad debt charges relating to legacy loans and higher funding costs. Together, these totalled c.£2.3m of additional cost. | ||
Pennant International (LON:PEN) (£14m | SR39) | H1 revenue +29% to £5.8m with ARR of £2.6m and adj EBITDA of £0.5m. Adj pre-tax loss of £0.3m, reduced from a loss of £2m last year. 2026 outlook: on track to achieve full year expectations. H2 is expected to be stronger than H1. | ||
Alien Metals (LON:UFO) (£11m | SR25) | West Coast Silver is Alien’s JV partner in the Elizabeth Hill Silver Project. | ||
Croma Security Solutions (LON:CSSG) (£10m | SR53) | Acquired A. Butler & Sons, a commercial locksmith in Holborn trading under the name William Channon, with turnover of £1.1m, net assets of £1.1m and a pre-tax loss of £0.06m in 2025. Consideration for the acquisition was c.£1.0m in cash. |
Graham's Section
Bodycote (LON:BOY)
Up 4% at 951p (£1.62bn) - Recommended Cash Acquisition & Statement Regarding Possible Offer - Graham - TAKEOVER
Bodycote is “the world's largest provider of heat treatment and specialist thermal processing services, operating a global network of approximately 130 facilities across 22 countries with a workforce of approximately 4,000 employees.” It’s a familiar name for many of us, and is a component of the FTSE-250 Index.
It has been in play since early August when two near-identical proposals were disclosed: one at 915p from CVC, and one at 914p from Veritas. There had been interest at 885p from Apollo a few months previously.
Bodycote must be highly attractive to private equity firms, given all of this interest.
Today’s announcement is a recommended offer, with the board supporting a 940p takeover price.
This includes a 7.2p interim dividend, which would be due to be paid to shareholders in November, regardless of the takeover offer.
940p is a 24.3% premium to the price at which Bodycote shares were trading just before the interest from private equity firms was revealed. That’s typical for the sort of premium that UK shareholders tend to be open to accepting.
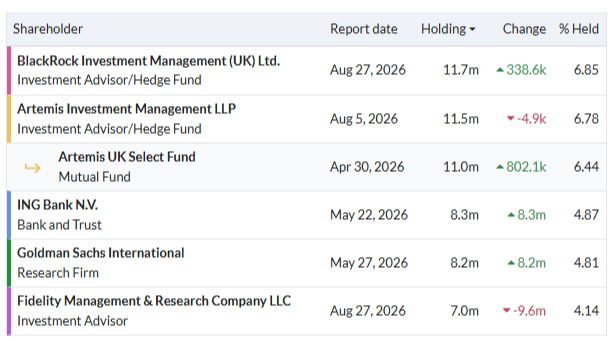
So the mainstream asset managers on the shareholder register would probably agree to this, I suspect:
But at 7:48am this morning, CVC also made an announcement:
CVC… notes the firm intention announcement made by Veritas and the Company and its terms and conditions…
CVC is considering its position and a further announcement will be made when appropriate.
Bodycote shareholders are strongly advised to take no action in response to the Veritas Offer in the meantime.
It’s not really CVC’s place to offer advice to Bodycote shareholders, but clearly they want to have the option to come in with a counter offer.
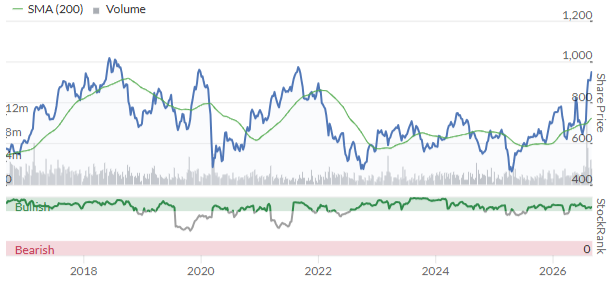
So the current share price in the market of 950p makes a lot of sense: there’s every chance of a slightly higher bid from CVC (or maybe even Apollo?).
Rationale: Bodycote has been listed in London for over 50 years. Why sell out to a US private equity firm now? The simple answer is the price offered:
"The Bodycote Board believes that this offer from Veritas reflects the high quality of Bodycote's business and management, and delivers shareholders excellent value in cash… The Board remains highly confident in Bodycote's prospects and believes that this offer recognises that value today and is therefore recommending it to shareholders."
Based on EPS forecasts, the earnings multiple at 940p is 19x (current year) or 16.5x (next year).
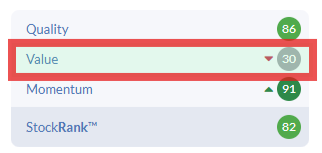
The StockRanks consider it to be fully-valued here, also highlighting the Quality and Momentum it offers:
The company is carrying some debt (net debt £135.2m at the interims), but I don’t think it’s enough to make any huge difference to the valuation.
Graham’s view
I’ll have mixed feelings about this one leaving the LSE. The price being offered is not terrible, and it’s up to Bodycote’s shareholders if they are happy to sell at this price. It seems to me that it would be reasonable for them to hold out for a premium of 30%+. As a general point, I think it would be healthier for investors and their Board representative to hold out for 30%+ in takeover talks.
The main problem I have with this is that Bodycote won’t be replaced by a company of equal standing. The exodus continues.
Roland's Section
Dialight (LON:DIA)
Up 7% at 594p (£241m) - AGM Trading Update - Roland - AMBER/GREEN ↑
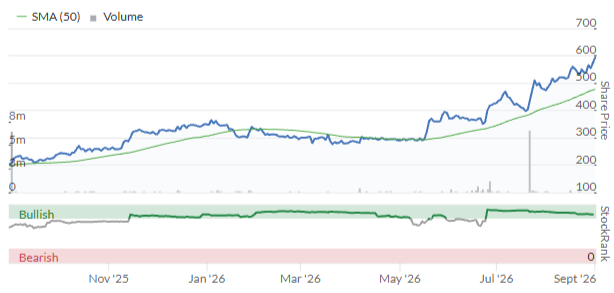
Dialight’s share price has risen by 70% since our last (cautious) view in January, so it seems like a good time to take a fresh look and see what’s changed since then for this LED lighting manufacturer:
Let’s start with a look at today’s AGM update, which includes upgraded guidance for the year ending 31 March 2027.
Dialight’s management recap the positive guidance provided in previous updates and confirm a positive outlook for the second quarter of the current year:
23 June (Final Results): the group reported a strong and growing backlog that was well ahead of the previous year.
22 July (Trading Statement): first-quarter sales growth “comfortably exceeded” management expectations for 3% to 5% growth.
Today: “This rate of expected growth is now likely to continue in the second quarter of the year-to-date.”
Profitability also appears to be holding up well. Dialight’s gross margin has “continued to comfortably exceed” the company’s target of 45% in Q2.
Higher gross margins are said to be flowing “directly through to increased underlying profitability”. This suggests to me that operating costs are remaining stable despite higher sales. That’s an indicator of positive operating leverage, so we could see an improvement in operating margins if this situation continues:
This has also meant that the Group is likely to meet the newly issued, and upgraded, return on sales target of 15% plus in the first half of the year.
(Return on sales is effectively the same as operating margin)
One point I’d make about the company’s commentary this morning is that it only refers to Q2/H1. This seems to suggest that visibility on H2 may still be quite limited.
Balance sheet & cash flow: in January, Mark highlighted our concerns about Dialight’s balance sheet and use of adjusted profits. However, this situation seems to have improved since then:
June’s full-year results showed net debt reduced to $1.9m.
In July the company said it had moved to a net cash position.
Today’s update reports an improved net cash position and expectations for “further cash generation” during the remainder of the year.
Updated outlook: today’s upgraded outlook sounds quite positive, but frustratingly Dialight has chosen not to include details of current expectations or any specific detail on revised guidance:
Whilst there remains a significant proportion of the financial year still to be delivered, based on performance to date and the current outlook, the Board now believes the Group's adjusted profit before tax for the financial year ending 31 March 2027 is likely to be significantly ahead of its’ [sic] previous expectations.
We don’t have access to any broker coverage for Dialight, so we’re left guessing.
What we can see is that consensus expectations have already been upgraded several times over the last year:
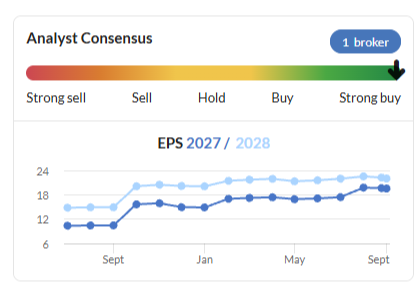
Use of the word “significantly” suggests to me we can expect an upgrade of 5% to 10% from current estimates.
That suggests an adjusted EPS figure of perhaps 21p to 22p this year, giving a FY27E P/E of about 27x.
Roland’s view
Mark was AMBER/RED on Dialight in January, but it’s clear that a number of our previous concerns have now moderated, so I will be upgrading our view today.
I am still inclined to be relatively cautious on a couple of points, though. The $16m reduction in net debt last year appears to have been driven entirely by the $16.6m reduction in inventories over the same period. That’s valuable, but is likely to be a one-time benefit.
With profits expected to rebound this year, I’ll be interested to see what level of free cash conversion is achieved from earnings.
The other point I think is worth highlighting is the valuation:
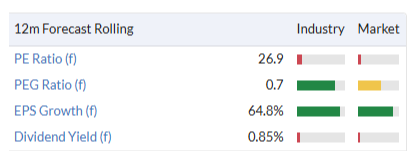
While the PEG ratio of 0.7x suggests some value may remain here, it’s been eight years since Dialight achieved a double-digit operating margin (unadjusted).
If Diaglight can achieve a 15% operating margin without relying on adjustments…
If the current performance is maintained into H2…
And if earnings are converted to free cash flow, then I can see that there could still be some upside left here.
The valuation is too rich for me personally, but I’m going to take a moderately-positive view today out of respect for the evident momentum here. The StockRanks are also positive, with High Flyer styling:
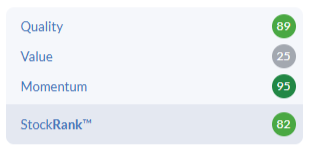
If I was interested in investing in Dialight, my next step would be to learn more about the company’s end customers and its order book, in order to try and gauge if the current momentum is likely to be sustainable.
I’m going AMBER/GREEN today, but I’d be quick to turn neutral on any sign of slowing growth.
Michelmersh Brick Holdings (LON:MBH)
Up 0.6% at 75p (£69m) - Half Year Results - Roland - AMBER =
I highlighted this premium brick manufacturer in The Week Ahead last week – it’s a stock that’s been on my radar for a while as a possible value play on the UK housing sector.
My hope for today’s results was that they would be in line and not show any serious deterioration in either the outlook or Michelmersh’s balance sheet.
Let’s see how things have panned out.
Half-year results summary
The headline numbers from today’s results suggest a rather mixed picture for H1:
Revenue down 9.5% to £32.4m
Gross margin up 3.4% to 37.0%
Operating profit up 3.3% to £3.1m
Pre-tax profit down 3.4% to £2.8m
Reported earnings per share up 3.6% to 2.56p
Adjusted earnings per share up 0.9% to 3.33p
Interim dividend unchanged at 1.6p per share
Stepping through these figures provides some insight into the factors that lie behind these results.
Revenue: sales fell as expected, reflecting a 9% decline in UK brick market despatch volumes during the period. Michelmersh says its volumes only fell by around 2%, suggesting it may have gained some market share during the period. The company says the diversity of its end markets and the quality of its (premium) products helped to support sales.
Profits: Michelmersh’s gross margin of 37% is still below the 40%+ peak levels seen in the past, but I think it’s a decent result in current market conditions. The 3.4% increase in gross margin during the first half reflects more efficient operations and the benefit of recent restructuring.
Some of the changes during the period included the closure of the company’s Charnwood plant, where freehold property is now being reviewed for potential sale.
There was also a 30% reduction in production volumes at the Freshfield Lane site “to address specific ongoing demand challenges” in London and the South East – sufficient inventory is available to respond to any sudden increase in demand.
More positively, Michelmersh restarted production at its Romsey site in May, with “near-full production” from August and improved margins expected in H2.
Despite (because of?) these changes, the group’s operating costs fell slightly during the period to £8.2m. When combined with lower revenue, this drove a 1% increase in Michelmersh’s operating margin to 9.5% (H1 25: 8.5%). 90%+ of energy costs are hedged for the remainder of the year, reducing any impact from further price rises.
An increase in finance costs was largely offset by a lower tax charge to drive a small increase to post-tax earnings per share.
Pricing pressure & returns on capital: crunching the numbers suggests to me that Michelmersh’s trailing 12-month return on capital employed has improved slightly to 4.4% (FY25: 4.2%) – albeit still well below the group’s cost of capital.
ROCE has peaked at over 10% in past cycles, so I’d expect this figure to improve when market conditions recover and demand supports an increase in both capacity utilisation and pricing.
Competitive market conditions are currently weighting on profitability – management reports a "competitive pricing environment” in which they are trying to achieve “stable average selling prices to support customers”. In other words, Michelmersh isn’t even trying to raise prices, only hoping to avoid cutting them.
Cash & Balance Sheet: I think it’s fair to say the H1 cash performance may have been slightly below expectations.
The accounts show operating cash flow fell by 50% to £1.6m during the half year, “mainly due to timing of receivables” following a weaker Q1 and stronger Q2.
I’m not too worried, but this situation does mean that the group ended the period with net debt of £5m (FY25: £0.7m). Forecasts suggest strong cash generation in H2, reducing year-end net debt.
Dividend: the interim dividend has been left unchanged, but my feeling is that despite the expected improvement in H2, cash cover for the payout could be marginal this year.
However, the current 4.6p dividend offers a 6.1% yield. This looks attractive to me, if it can be maintained without being funded from borrowed money.
Outlook & Broker Estimates: Michelmersh says its order book is continuing to run ahead of manufacturing volumes, but says that predicting call-off rates “remains challenging”.
As I understand it, the order book reflects contracted or reserved volumes, but call-off rates trigger despatch and invoicing. My reading of the company’s comments is that there’s some risk that committed orders could slip into later quarters.
In terms of profit guidance, today’s outlook statement is technically in line. However, the wording and caveats included suggest to me that there’s some risk full-year results could miss forecasts:
We continue to expect the Company to deliver performance within full-year expectations, but we remain watchful of the impact from political uncertainty in the UK and overseas from the ongoing conflict in the Middle East combining to further undermine consumer confidence
Fortunately, Michelmersh’s house broker Canaccord Genuity has issued updated forecasts today and made these available on Research Tree.
Unfortunately, Canaccord has cut earnings forecasts slightly for 2026 through 2028:
FY26E adj EPS: 7.6p (-2.2% vs 7.7p previously)
FY27E adj EPS: 7.8p (-6.7% vs 8.4p previously)
FY28E adj EPS: 8.3p (-6.3% vs 8.8p previously)
Essentially, this looks like the company has pushed back expectations for any improvement in market conditions, particularly in housing.
Roland’s view
The reality is that no one really knows when demand will improve. In a year’s time, Canaccord might be upgrading forecasts to reflect a rosier outlook. Or it might not be.
However, Michelmersh says that current UK brick despatch volumes are currently more than 25% below the highs seen in 2022.
When I look at this metric against the reported demand for new housing, my conclusion is that the issues holding back new housebuilding will have to be resolved at some point, either through market action (price changes) or political action. I’m starting to feel this could happen sooner rather than later.
I think it’s worth noting that despite today’s cut to forecasts, Michelmersh’s share price is unchanged. The market is not punishing the slightly disappointing outlook. This suggests to me that we could be close to the bottom for both market conditions and sentiment.
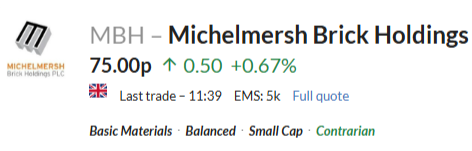
I think the value metrics for Michelmersh shares probably support the view that it could offer a Contrarian opportunity.
The stock currently trades on a P/E of 10, with a 6.1% dividend yield.
At 75p, Michelmersh shares are trading at 24% discount to today’s reported net asset value of 98p.
The current share price is in line with the latest tangible net asset value of 75p per share.
This looks like an interesting potential entry point to me, especially as the company has indicated there is investment land and freehold property on the balance sheet that could potentially be sold.
The problem is that any turnaround depends on wider housing market conditions. The timing for a recovery in this sector seems to keep slipping back:
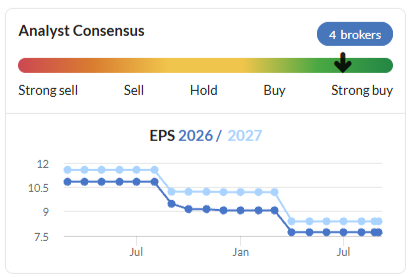
On balance, my view on this business isn’t much changed by today’s results. After a five-year decline, I think an opportunity is emerging here:
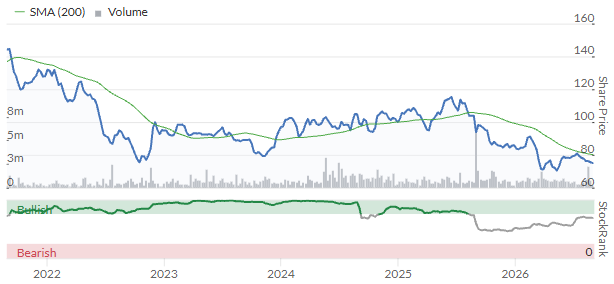
The caveat to my positive view is that the uncertain timing of a recovery means there could be an opportunity cost for investors who buy too soon.
I’m going to stay neutral today to reflect today’s cut to earnings forecasts, uncertain outlook and H2 weighting. But I would be quick to turn positive on any sign of improving momentum.
Ashtead Technology Holdings (LON:AT.).
Down 3.6% at 333p (£270m) - Half-Year Report- Roland - AMBER =
Ashtead Technology Holdings plc (AIM: AT.), a leading provider of subsea technology solutions to the global offshore energy sector, announces its unaudited results for the six months ended 30 June 2026 ("HY26" or "the period").
These results come just 12 days after Ashtead’s last trading update on 20 August, when it warned on profits. Given this short space of time, I wouldn’t expect any change to outlook today and the company confirms that guidance remains unchanged from 20 August. .
In my previous commentary I questioned the explanation for project delays in Europe and the Americas and Ashtead has clarified this today, confirming that these relate solely to scheduling changes:
The project delays witnessed outwith the Middle East are the result of specific project scheduling changes and not an indication of a fundamental shift in market dynamics
The company’s H1 results appear to support this view, with revenue in Europe and the Americas both ahead of the same period last year.
The main area of weakness in H1 was not the Middle East but was instead the Asia Pacific region, where revenue fell by 30% to £8.1m, where the company reported “softer renewables activity”.
H1 results summary
Overall H1 results do not look too bad to me, with flat revenue and only a modest reduction in profits:
Revenue down 1.1% to £100.2m
Operating profit down 5.9% to £21.8m
Pre-tax profit down 1.5% to £17.5m
Adjusted earnings down 5.9% to 20.6p per share
Return on Invested Capital down 3.7% to 20.5%
Net debt leverage reduced to 1.4x EBITDA
Looking at the accounts, my sums give me a trailing 12-month return on capital employed of 16.5%. That’s slightly below the company-adjusted measure, but fairly close to last year’s comparable result:
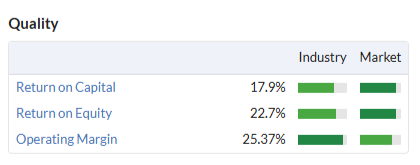
This is a high-margin business that generates attractive returns on capital, perhaps reflecting the specialist nature of its products and buoyant state of many end markets.
While there’s some risk of a cyclical slowdown at some point, today’s results suggest to me that Ashtead’s quality appeal remains largely intact.
Outlook
I don’t have access to broker forecasts from either of the company’s joint brokers (Peel Hunt and Deutsche Bank), so I’m not sure how their EPS estimates may have changed following last month’s profit warning.
Our consensus trend chart on the StockReport shows an average of 43.3p per share for FY26, but updated forecasts from Zeus (which I can see) show a 2026 EPS estimate of 37.7p – quite a big range.
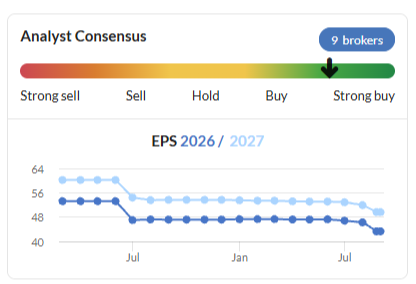
Assuming a figure of around 40p suggests that H2 earnings will be broadly equal-weighted this year and prices the stock on a forward P/E of 8.3x.
That could be cheap if the medium-term growth thesis presented by the company is accurate:
Latest Rystad forecasts point to a 6% CAGR in our total addressable market out to 2029.
On a sector-by-sector basis, Ashtead says Rystad is forecasting a slight reduction to renewable growth, paired with slightly stronger growth for both oil and gas and decommissioning activity.
While this seems fairly positive, I can’t help feeling that the commentary on trading conditions at some of Ashtead’s major customers is slightly more nuanced (my emphasis):
Whilst timing of contract awards has resulted in customer subsea backlogs of the three Tier 1 contractors reducing by 7%, these remain at near record high levels and customers are pointing to an increase in pipeline as they look out over the next two years. These customer backlogs and opportunity pipelines give us confidence of a long runway of opportunities for our services as we look out to the end of the decade and beyond.
Roland’s view
The StockRanks are neutral on Ashtead Technology and our algorithms style the stock as Contrarian:
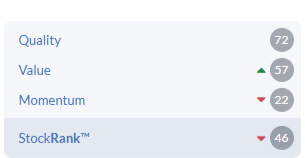
I’m inclined to think this view could be a little harsh, given the group’s strong quality metrics and relatively modest H1 earnings decline.
Using one of my preferred valuation metrics, the EBIT/EV yield, I get a figure of more than 12% – generally a level I’d see as cheap.
However, I’m aware of the negative trend to earnings forecasts and the potential for this to continue. My main concern is the potential for further knock-on disruption from the conflict in the Middle East, or even the start of a wider cyclical slowdown. That’s something we’ve not really seen since Ashtead’s listing in 2021:
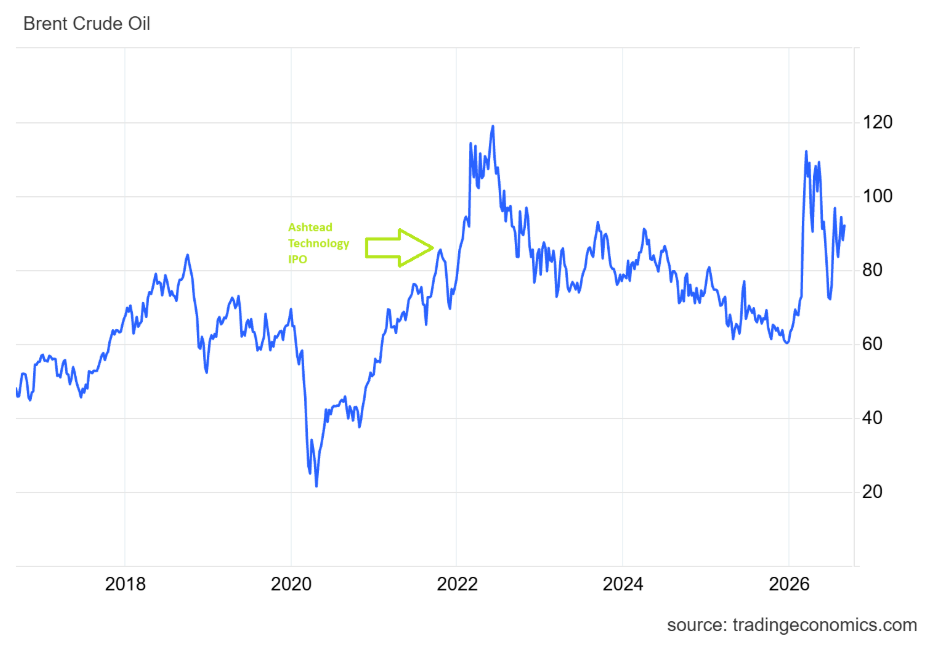
While I think this could be a stock that rewards further research, I’m going to stay neutral today for the reasons outlined above.
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.