
Two major market movements to let you know about this morning.
Firstly, oil marched higher and is now over $95, after rising about $4 since yesterday.
Oil had been making it through the Strait of Hormuz, in modest quantities, as the US focused more on economic aggression against Iran, rather than outright military action.
But the US has now hit Iranian “air defense sites, radar systems, maritime assets and facilities, mine laying capabilities, and communications sites”, along with two tankers, and Iran has made counter-attacks against US bases.
With the oil price rising, the markets are looking at the potential for interest rate hikes - and this leads me to the second major overnight market movement: interest rates.
Bond yields have risen further for both the US and the UK. The US T-Note is yielding 4.8%, while the UK’s 10-Year Gilt is at 5.2%, about 100 basis points higher than its low earlier this year:
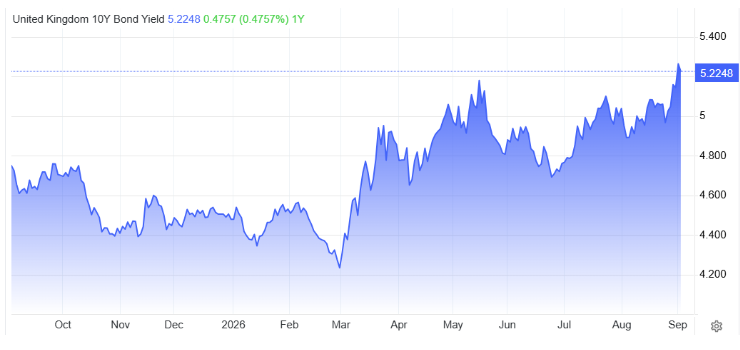
Source: tradingeconomics.com
An article on Bloomberg last night suggested that “together with higher inflation, higher borrowing costs will knock about £12 billion off the government’s £23.6 billion buffer against its fiscal rules”.
Interesting times ahead for the new Chancellor John Healey.
Overnight market movements:
The FTSE is down 0.4% at 10,750
S&P 500 is down 0.1% at 7,625
Brent crude (November) is up 0.9% at $95.50/bbl
Gold is down 0.2% at $4,320/oz
Bitcoin is up 0.3% at $77,700
Leaving it there for today, cheers! Spreadsheet accompanying this report: link.
Companies Reporting
| Name (Mkt Cap) | RNS | Summary | Our view (Author) |
|---|---|---|---|
BP (LON:BP.). (£85bn | SR99) | Tyler was already a NED and has been interim Chair since May 2026. His appointment is confirmed from today. | ||
Halma (LON:HLMA) (£13bn | SR56) | Acquired water quality monitoring and analysis specialist Pyxis for up to $200m (c.£148m), including earn-outs. Pyxis was founded in 2013 and is expected to generate c.$39m of revenue over the year to 31 March 2027. | ||
| Cairn Homes (LON:CRN) (£1.41bn | SR78) | Interim Results | H1 revenue +60% to €455.5m with operating profit +75% to €74.8m and adj EPS +82% to 9.3c. Forward order book +23% to €1.89bn (5,020 units). Outlook: now expect revenue and operating profit at top end of guidance (c.€1.08bn and €185m, respectively) with ROE of c.17.0% (prev. c.16.5%). | GREEN = (Graham)
I don’t see any need to change stance today, especially considering the improved full-year guidance. Cairn is generating sector-leading ROE and its prospects continue to improve, as the order book continues to grow. The danger? This is economically sensitive, of course, so investors should bear that in mind. I do think that Cairn buying back its own shares is a little aggressive at current levels. For housebuilders, I prefer when buybacks take place at a discount to NAV, whereas Cairn trades at a high premium. But overall, I remain a big fan of the story here and as such I remain fully GREEN. |
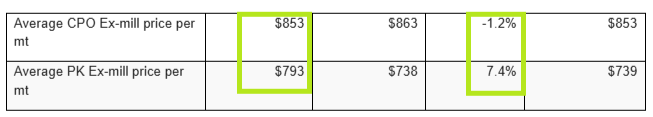
AEP Plantations (LON:AEP) (£771m | SR94) | H1 revenue +8.3% to $249.7m with pre-tax profit +5.1% to $65.8m, including a $9.1m non-recurring gain. Average ex-mill CPO price was -1.2% at $853/mt and palm kernel price was +7.4% at $793/mt. Outlook: confident of achieving market expectations for the full year. | AMBER = (Roland) Today’s half-year results show H1 profits were held back by delayed cropping and higher overheads. However, the company’s guidance for a stronger H2 seems reasonable enough to me and I’m happy to view these results as being in line. While the FY26E P/E of 8 may seem cheap, it’s worth noting this is based on elevated CPO and PK prices. On a more normalised view of pricing, I’d argue the stock has re-rated and that further upside is dependent on commodity pricing. For this reason, I’m maintaining our previous neutral view today. | |
Avon Technologies (LON:AVON) (£545m | SR35) | Team Wendy Ceradyne has received an order worth $20.3m from the US DLA under the Feb 2022 framework. This order fulfils the maximum volume authorised for the current year. | ||
Ecora Royalties (LON:ECOR) (£419m | SR64) | Total portfolio contribution (underlying revenue) +75% to $31.3m, with pre-tax profit of $24.3m (H1 25: loss of $10.9m) and free cash flow of $12.1m. Outlook: expect critical minerals portfolio to continue volume growth in H2, benefiting from commodity price tailwinds. | ||
Custodian Property Income Reit (LON:CREI) (£397m | SR65) | LFL rental values +1% in Q1, driven by +1.6% in the industrial sector. 1.5p dividend approved for the quarter, fully covered by EPRA earnings per share and in line with full-year target of 6p per share. | ||
TT electronics (LON:TTG) (£241m | SR66) | H1 revenue -4.1% to £228.1m with adjusted pre-tax profit +85.9% to £15.8m. Adjusted EPS +200% to 5.7p per share. Outlook: the Board expects 2026 adjusted operating profit to be ahead of current market expectations (previous consensus: £35.0m). | (will cover this by the end of the week) | |
Rentguarantor Holdings (LON:RGG) (£127m | SR39) | Jan-Aug revenue +472% to £8.45m, with adj net profit of £2.87m (H1 25: £(392)k. Number of applications +174% YoY, contracts +311% YoY. Outlook: Board now expects 2026 revenue and adjusted net profit to be “materially ahead” of expectations (previously: revenue £9.1-10m and adj net profit £1.2-2.4m). | GREEN ↑ (Graham) | |
Motorpoint (LON:MOTR) (£109m | SR48) | Trading volumes stronger than expected with “favourable” supply dynamics. Outlook: now expect pre-tax profit for y/e 31 March 2027 to be £9.8m to £10.8m, ahead of market consensus (previously: £9.1m to £10.0m). Shore Capital upgrades FY27E adj EPS to 9.3p (prev. 9.0p) | AMBER ↑ (Roland) A strong update which sounds confident on both demand and supply. One factor that’s not mentioned today is the impact of interest rates, which prompted a profit warning in April. While I’m a fan of this well-run business, I think it’s worth remembering how sensitive its profits are to small changes in pricing, costs or interest rates. I think there could be the potential for further gains here, but I don’t think the business can escape its exposure to macro factors. With the shares already trading on a mid-teens P/E. I’m moving my view up by one notch to be neutral today. | |
Ten Lifestyle (LON:TENG) (£92m | SR74) | The change of the Company's name from Ten Lifestyle Group plc to Ten Technologies Group plc has now been registered at Companies House and is effective. Ticker, ISIN, etc. remain unchanged. | ||
Aminex (LON:AEX) (£70m | SR9) | At a meeting convened by the Tanzanian Ministry of Energy, the Government did not approve a proposal by the operator to extend and delay the project timetable and instead confirmed a revised implementation schedule to which all parties agreed. The Ntorya to Madimba pipeline will be completed in time to receive first gas from the Ntorya field in December 2026. | ||
Calnex Solutions (LON:CLX) (£52m | SR59) | Trading in the year to date is in line with market expectations. “…the Board remains confident in the Group's prospects for FY27 and continues to expect the targeted investment being made this year to support accelerated growth in FY28.” | AMBER = (Roland) | |
Corero Network Security (LON:CNS) (£37m | SR18) | Significant new contract with a leading UK-based fixed and mobile telecommunications and connectivity provider. Alongside one of its strategic alliance partners, Corero has secured a 5-year contract for a total contract value of $3.4 million. Also wins a 3-year contract with a total contract value of $0.5 million. | GN note: is this material news? Annual revenues at CNS are c. $30m. | |
Bezant Resources (LON:BZT) (£34m | SR24) | Hartree, Bezant's financing and offtake partner, will participate alongside Bezant in the financing of the accelerated payment arrangements related to the ownership of the NLZM Processing Plant. | ||
Kendrick Resources (LON:KEN) (£29m | SR17) | “Certified laboratory assays have now been received for three drill holes (TKDD002-4), each returning highly impressive LREO grades over significant widths and further reinforcing the scale, continuity and high-grade potential of the Teufelskuppe mineralised system.” | ||
Rome Resources (LON:RMR) (£22m | SR19) | Updated mineral resource estimate for Kalayi tin deposit at the Bisie North Project in the Democratic Republic of Congo. A 45% increase in contained tin, a 32% increase in resource tonnage and a 10% increase in average grade. | ||
Kazera Global (LON:KZG) (£17m | SR18) | The South African Department of Mineral Resources and Energy has formally approved the application by the Company's wholly owned subsidiary, Whale Head Minerals, for a Mining Right over Sea Concession 2A located in the Northern Cape, South Africa. | ||
Kelso group (LON:KLSO) (£16m | SR43) | 30th June: NAV per share 2.9p, up 23% for the period. Net assets £13.2m. Update 31st August: NAV per share 3.3p. Net assets £15.2m. Gross investments £23m using 33% gearing. Ten investments in established companies in UK small and mid caps. | ||
Orcadian Energy (LON:ORCA) (£14m | SR9) | Has entered into an agreement with an American developer of offshore data centre infrastructure. The Agreement establishes a 90-day process to enable due diligence, commercial validation and negotiation of a definitive Earlham and Orwell energy-to-compute transaction. |
Graham's Section
Rentguarantor Holdings (LON:RGG)
Up 15$ at 90.25p (£146m) - Trading Update - Graham - GREEN ↑
This one has been on a tear, more than trebling in a few months:
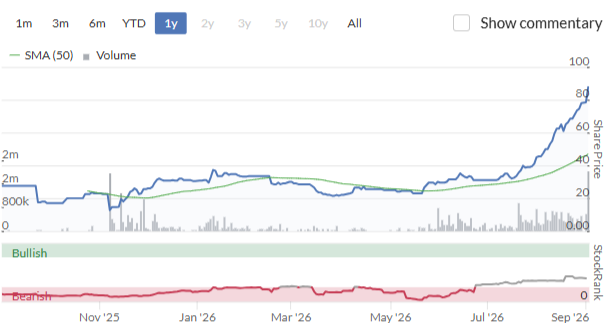
I’ve been moderately positive on it, calling it one of the most exciting growth stories I cover in this report, but also describing the valuation as “bonkers” if you are only looking at the current numbers.
I used that word “bonkers” at a market cap of £83m, only last month.
Today we are at £146m.
But this morning we’ve had an outstanding trading update to justify the ongoing share price gains, covering the eight months year to date.
There’s a nearly 500% increase in revenues, and the company can now report positive adjusted EBITDA and adjusted net profit:
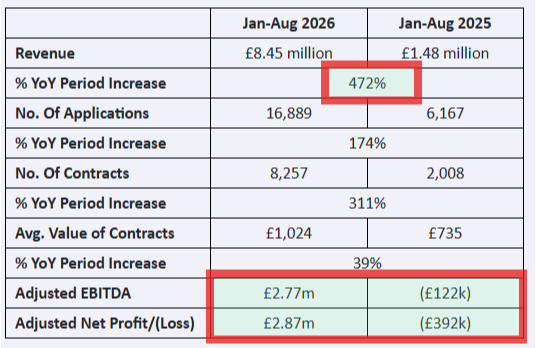
At the interim results to June, RGG reported a year-on-year revenue increase of 250% (to £3.4m).
So in the last two months alone, unless I’m mistaken, there has been revenue of over £5m.
RGG confirms that August monthly revenue was £3.17m.
So the company has already evolved from a startup into what we might call a medium-sized, profitable business.
Note the increase both in the number of contracts and the average value of contracts (up 39%) to £1,024:
Contributing to this growth is the number of higher value tenants now applying to have a professional guarantor in lieu of paying a number of months' rent up front, following the Renters' Rights Act.
As I’ve remarked before, the growth at RGG does have a legitimate explanation in the form of the RRA, which creates greater risk for landlords and therefore a stronger focus on the guarantor.
Cash has improved to £7.5m. The company repeats what it said at the interim results: that it will consider its dividend policy at the full-year results.
Outlook: couldn’t be any stronger.
The Board believes that the combination of accelerating customer demand and expanding commercial partnerships will result in revenue for the financial year ending 31 December 2026 (FY 2026) being materially above market expectations. The Board also considers that the Group's increasing operational scalability and improving profitability will lead to the Group's adjusted EBITDA and adjusted net profit for FY2026 being materially ahead of the market expectations range for the period.
It is now the Board's target for the Group to deliver revenues in excess of £14 million and a net profit in excess of £4 million in 2026. The Board has also increased its target expectations for 2027, and is increasingly confident that its target of 100,000 contracts by 2029 is becoming more of a reality at current growth rates..
Prior market expectations are helpfully provided: 2026 revenues of £9.1m to £10m, adjusted EBITDA of £1.6m to £2.7m, and adjusted net profit of £1.2m to £2.4m.
These expectations have been blown out of the water: revenues are now expected to be about 50% higher than the midpoint of the prior range (£14m+ vs. £9.5m), and net profit guidance is now expected to be double the midpoint of the prior range (£4m+ vs. £1.8m).
Cavendish forecasts: these are some of the best upgrades I’ve ever seen.
Revenue: 2026 £14m (previously £9.5m), 2027 £28.3m (previously £20.7m), 2028 £43.8m (previously £33.1m)
PBT: 2026 £3.7m (previously £1.2m), 2027 £8.2m (previously £4.6m), 2028 £13.2m (previously £8.5m).
If anything, the upgrade for 2026 strikes me as being possibly a little undercooked, as the company itself has said it expects net profit of £4m. If that’s true, then a PBT forecast of £3.7m this year is conservative.
But what’s really exciting is the potential for profits to keep compounding from there.
Graham’s view
I don’t think I have much choice but to turn positive on this today:
It has crossed over into profitability, and is already producing material profits.
Huge upgrades to its financial forecasts for the next few years.
All of this growth is well-explained by the introduction of the Renters’ Rights Act.
On top of all that, the valuation at the current level is not even particularly demanding compared to EPS forecasts. If the 2028 Cavendish EPS forecast of 5.9p turns out to be accurate, for example, the shares are currently trading at just 15x that forecast.
Given the growth that the company’s achieving, the numbers for 2026 alone don’t seem all that relevant, and it seems right to value it on its potential a few years from now. Maybe I was bonkers for not turning GREEN on this sooner?
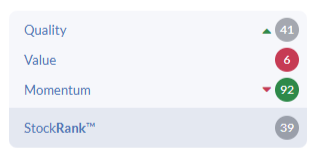
The StockRanks still don’t believe in it, by the way. Their analysis of Value is more backward-looking, so that makes sense:
Cairn Homes (LON:CRN)
Up 6% at 235.6p (£1.49bn) - 2026 Interim Results & €50 Million Share Buyback Programme - Graham - GREEN =
We already looked at the H1 trading update from this Irish housebuilder in July, when I maintained my positive view.
Let’s go straight to today’s full-year guidance, to see how it’s changed from July. We have small but pleasant upgrades, with the company effectively saying that its headed to achieve at the top end of the ranges previously given:
Revenue of c.€1.08 billion (previously €1.05 billion - €1.08 billion);
Operating profit of c.€185 million (previously c.€180 million - €185 million); and
ROE of c.17.0% (previously c.16.5%).
The company says that it expects to deliver 6,000 homes in the next two years (2026-2027), compared to 12,000 homes in its entire first decade. It was founded in 2014.
So clearly, the positive momentum is continuing. But let’s drill into these H1 numbers a little bit:
H1 revenue +60% to €455.5m
Average selling price +1.6% (i.e. volume is the main growth driver, not ASP)
Operating profit +75% to €74.8m
There’s large H2 weighting - operating profit in H1 is only 38% of full-year guidance - but I would expect the company to have excellent visibility over H2 performance. It knows at this stage which developments are finishing and ready for delivery.
Net debt has increased from €171m (Dec 2025) to €194.5m (June 2026), but it is still down considerably year-on-year. It was over €300m a year ago.
Given the strong profitability expected in H2, the company is going to buy back shares:
…the Group is well positioned for strong cash generation and profitable growth throughout the remainder of 2026 and into 2027. Reflecting this confidence, Cairn today announces a new €50 million share buyback programme, increases its interim dividend by 10% to 4.5 cent per share and upgrades FY26 ROE guidance to c.17.0%...
The company is already paying out about half of its annual profits in the form of dividends, but it seems to me that it can afford to make this buyback too. After-tax net profits are expected at c. €144m this year, so it’s possible to pay out half of this in dividends and still have more than €50m left over for buybacks.
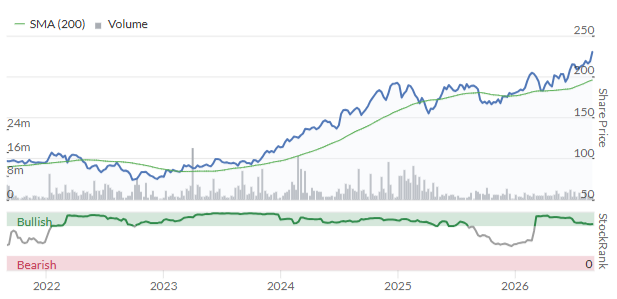
Cairn has form for buying back its shares, having done so from 2022 to 2024, but this buyback will be taking place at much higher levels: the share price is has more than doubled since 2022-2023:
Graham’s view
I don’t see any need to change stance today, especially considering the improved full-year guidance.
Cairn is generating sector-leading ROE and its prospects continue to improve. Here are the latest order book figures:
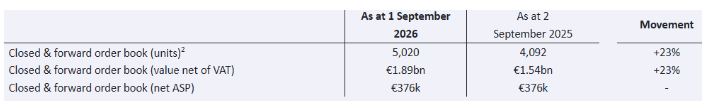
At the H1 trading update, the company said it had 4,800 homes with a value of €1.8 billion in its order book. So that figure has continued to increase in recent months (to 5,020 homes with value €1.89 billion).
The danger? This is economically sensitive, of course, so investors should bear that in mind. For what it’s worth, I don’t see what is going to upset the apple cart for Irish housebuilders: demand continues to exceed supply by a wide margin. So long as the Irish economy remains reasonably strong, there will be far more prospective first-time buyers than there are new homes being built.
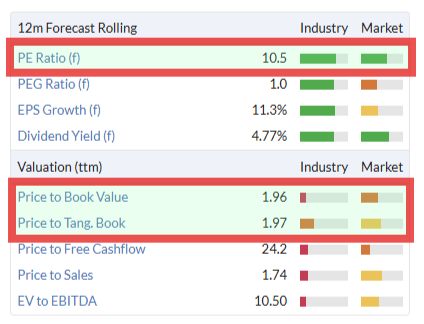
I do think that Cairn buying back its own shares is a little aggressive at current levels. For housebuilders, I prefer when buybacks take place at a discount to NAV, whereas Cairn trades at a high premium. Also, the PE multiple is about 10x, so I wouldn’t say that it’s obviously a bargain:
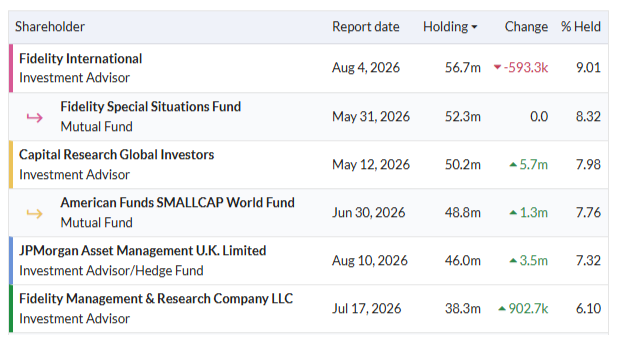
So I’m not a fan of the new buyback. This is a case where I’d prefer to see special dividends, letting shareholding decide what they wish to do with the proceeds. Dividends are probably not too inefficient from a tax point of view for Cairn’s institutional shareholders, who are very much blue-chip in nature:
Overall, I remain a big fan of the story here and as such I remain fully GREEN.
Roland's Section
Motorpoint (LON:MOTR)
Up 8.5% at 141p (£120m) - Trading Update - Roland - AMBER ↑
Today’s trading statement appears to be an unscheduled update issued solely to upgrade the used car supermarket’s financial guidance for the current year.
Management commentary is brief but positive:
Trading volumes have been stronger than anticipated, supported by our strategic initiatives, including accelerated investment in technology, data and AI, with margin improvements yielding higher profitability per unit. Supply dynamics remain favourable and we are pleased to announce a further store has been secured to open in Spring 2027.
Outlook & upgraded guidance: as a result of strong trading and “increased confidence in vehicle supply conditions” and successful technology upgrades, profits for the year ending 31 March 2027 are now expected to be ahead of market consensus:
New guidance: FY27 adjusted pre-tax profit to be £9.8m to £10.8m
Previous consensus estimates were from £9.1 to £10.0m
Taking the mid-point, this represents an 8% increase to pre-tax profit expectations.
Broker estimate: with thanks to house broker Shore Capital this morning, we also have updated earnings forecasts:
FY27E adj EPS: 9.3p (+3.3% vs 9.0p previously)
FY28E adj EPS: 12.1p (unch)
These estimates put Motorpoint on a FY27E P/E of 15, falling to a P/E of 12 in FY28.
Roland’s view
From an operational and customer perspective, I think this is a very well-run business with an attractive share of the UK used car market.
However, as an investment we need to remember that Motorpoint’s profits are extremely sensitive to small variations in used car supply costs, interest rates and pricing. With sales of c.£1.3bn, a 0.1% change to the group’s pre-tax profit margin can add c.10% to pre-tax profits.
This was apparent when I last wrote about the company in April. Despite a bullish-sounding 8% increase in sales volumes, Shore cut FY27 earnings EPS forecasts by around 30% to 7.8p to reflect the impact of higher interest rates.
The same broker is now forecasting FY27 earnings of 9.3p per share – a 19% increase in four months. Zooming out to look at the consensus view over the last 18 months shows that current forecasts are still well below the level seen this time last year:
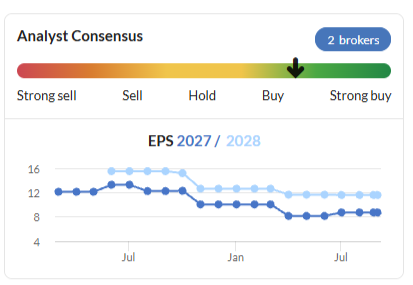
In today’s update, Motorpoint sounds very confident about vehicle supply conditions and positive about consumer demand. Interest rates aren’t mentioned, but could remain a wildcard – like many car dealerships, stock is financed through a specialist debt facility and the company also depends on commission income from the finance deals it sells to customers.
I don’t think it’s a coincidence that Motorpoint’s share price remains a long way below the levels seen during the zero interest rate era:
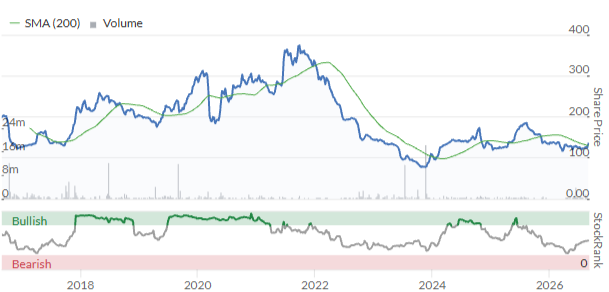
I admire this business and have a lot of confidence in owner-CEO Mark Carpenter (10% shareholder). But I don’t have a crystal ball – and neither does he. I think it’s fair to say Motorpoint will remain exposed to macro factors beyond its control.
It’s also true that this is an ultra-low margin retailer whose profits are dependent on high volumes and rapid stock turnover.
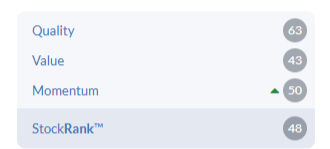
I was AMBER/RED in April, but that’s no longer an appropriate view. However, with the stock already trading on a mid-teens P/E, I’m not sure I’m confident enough to make the leap to AMBER/GREEN. The StockRanks also remain fairly lacklustre:
I’m going to move up one notch to neutral (AMBER) today, with the caveat that investors with insight into the used car sector may well choose to take a higher-conviction view (positive or negative) than me.
AEP Plantations (LON:AEP)
Down 3.2% at 196p (£730m) - Half-Year Results - Roland - AMBER =
This palm oil producer has tripled over the last two years and is well liked by the StockRanks:
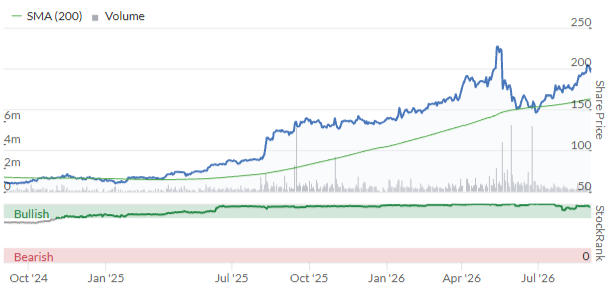
Today’s results leave expectations largely unchanged but suggest an H2 weighting will be needed to meet full-year forecasts. This may explain today’s slight share price dip.
Half-year results summary
These accounts reveal a sharp increase in operating costs and weaker like-for-like production. This combination put pressure on profits margins for the period, despite an increase in overall production and revenue:
Revenue up 8.3% to $249.7m
Pre-tax profit up 5.1% to $65.8m, (including a one-off, non-cash $9m accounting gain relating to the Pinago acquisition)
Pre-tax profit excluding one-off gain down 9.3% to $56.8m
Earnings per share up 3.1% to 12.71 cents
For some reason AEP was able to acquire Pinago for $158m, below the $171m fair value of the assets acquired. This resulted in a so-called bargain purchase gain of $9m:
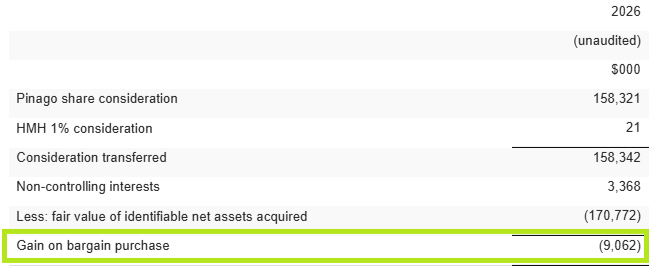
I don’t see much point in including this in my view of profits – it’s a one-time non-cash gain that doesn’t reflect operating performance.
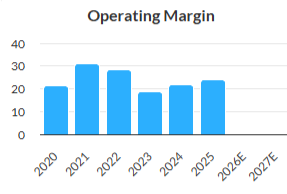
Using my view of underlying operating profit, AEP’s operating margin fell to 21.4% in H1, from 25.7% for the same period last year. This reflects a 123% increase in administrative costs – albeit some of these were acquisition-related:
Administrative expenses increased to $10.5 million from $4.7 million, mainly due to higher corporate expenses, including acquisition-related costs for Pinago and PT Jaya Jadi Utama, and the inclusion of two months of expenses from Pinago.
While 21.4% is still a strong margin, it’s at the lower end of the range we’ve seen over the last five years:
Balance sheet: despite spending $158m on the acquisition of Pinago and $25.9m on dividends and buybacks in H1, AEP ended the half year with net cash of $96m. That’s about 10% of the group’s market cap. This is an impressive display of strength, highlighting the strong cash generation of this business when commodity prices are high, as they are currently.
Commodity prices: AEP’s revenue is entirely driven by the market prices of Crude Palm Oil (CPO) and Palm Kernel Oil (PKO) – both commodities are extracted from the palm fruit grown by the company’s plantations. (Mark provided an excellent primer on this business in his write-up of MP Evans here.)
The commodity price environment has been favourable in recent times and remained so in H1. This is particularly true for PK prices, which have roughly doubled since 2023 and rose further in H1 26:
I don’t know whether the strength in PK will persist. Prices have historically been more volatile than CPO and I note that broker Cavendish is using a lower PK price of $400/t for FY27 and FY28, “assuming the recent strength is a temporary spike”.
Of course, if this strength persists, it could drive some nice upgrades to forecasts in 2027. I estimate that the $393 difference between recent PK prices and Cavendish’s FY27 forecast assumption of $400/t was equivalent to around 9% (c.$22m) of H1 revenue – a material amount.
Production volumes: AEP can’t control pricing but it can aim to maximise production volumes, particularly in strong markets. The company’s H1 performance seems a little mixed in this regard, with timing factors seeming to hold back some production.
Fresh Fruit Bunches (FFB) production rose by 2.7% to 544,700 tonnes - this included 29,000t from Pinago, without which FFB production would presumably have fallen by 2.8% to 515,700t.
The company says production was held back by “a delayed cropping cycle” and the ongoing replanting of some of its plantations.
Production has trended higher since June and is expected to be stronger during the second half of the year.
In addition to its own produce, AEP also buys in FFB from external growers to fill capacity in its mills. External FFB bunches purchased rose by 12.9% to 669,800 tonnes during the half year.
This supported an overall increase in CPO and PK production:
CPO Production +4.3% to 223,600 tonnes
PK Production +5.3% to 55,500 tonnes
Outlook & Broker Estimates
AEP’s house broker Cavendish has tweaked its 2026 EPS forecasts upwards to 32.7 cents per share today (previously 32.2 cents) – slightly above consensus:
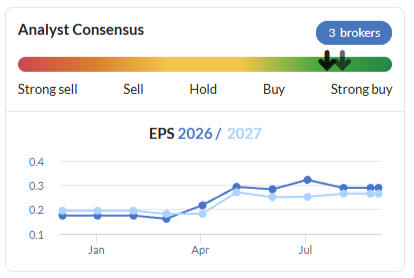
Based on the company’s H1 earnings of 12.71 cents, this means AEP needs to generate more than 60% of its earnings in H2 in order to avoid missing its house broker’s forecasts.
While we are often cautious about H2 weightings, I think this forecast seems credible enough, based on expectations for stronger production in H2 and “elevated” CPO prices over the coming months.
Cavendish’s estimate puts AEP on a 2026 P/E of around 8.1 with a 3%+ dividend yield.
While this may seem like a bargain multiple, it’s worth remembering that commodity stocks often trade on a low P/E when prices are high. This is the market’s way of recognising that commodity prices tend to move in cycles and may fall at some point.
While forecasts for 2027 and beyond remain uncertain, in my view, it’s worth noting that the current consensus view is that profits are likely to be lower next year.
Roland’s view
AEP is expanding and upgrading its estates and appears to be on track to deliver another strong year, assuming today’s guidance remains valid.
Commodity prices aside, another factor to consider is whether changing conditions in the Indonesian palm oil market will affect profits. Starting in 2027, palm oil producers will have to sell their oil to a government export agency which will then negotiate international sales.
Although AEP sells all of its oil to domestic refiners and thus isn’t directly exposed, I can imagine there could be second-order effects from this change that are hard for us to predict.
Mark was neutral on AEP in June, based on his view that the stock has now re-rated and that further upside is dependent on commodity prices. I share this view, so I’m going to stay neutral today.
Calnex Solutions (LON:CLX)
% at p (£m) - AGM Trading Update - Roland - AMBER =
I reckon this network testing equipment specialist is one of the more interesting IPOs of recent years.
Calnex floated in 2020 at the start of a period of peak profits, before suffering a nasty cyclical collapse in earnings. Founder-CEO Tommy Cook (19.7% shareholder) has since been rebuilding the business with a more diversified portfolio that’s expected to provide a more durable platform for medium-term growth.
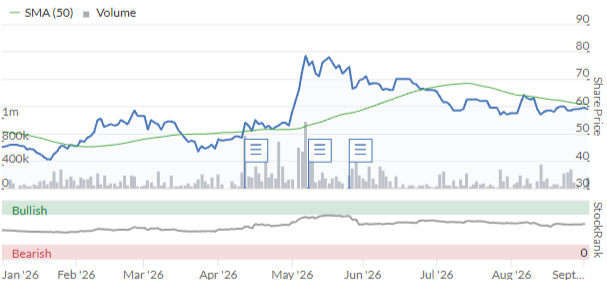
Ed Sheldon covered the company’s full-year results in May, noting diversification into markets such as defence and data centres, together with a 73% increase in pre-tax profit for the year. He stayed neutral on valuation grounds, which proved to be a good call – the share price has drifted lower since then:
That brings us up to date ahead of today’s AGM update:
Trading in the year to date has been in line with market expectations. Supported by a strong balance sheet, differentiated product roadmap and growing customer opportunities, the Board remains confident in the Group's prospects for FY27 and continues to expect the targeted investment being made this year to support accelerated growth in FY28.
Calnex reports continued progress with diversification and new product development:
Diversified product portfolio is continuing to drive growth, including a recent “digital infrastructure win with a major US financial institution”.
The company’s telecoms business “maintains its leadership position, albeit in anticipated lower growth markets”.
Engagement around the “next-generation Sentry data centre assurance offering continues to develop positively”.
Development of a 1.6Tb/s synchronisation testing product is also progressing towards planned launch next year, building on the success of a 800 Gb/s product (half the speed!).
Outlook
Forecasts from broker Cavendish are unchanged today and suggest a strong recovery in earnings over the next 18 months or so (Calnex has a 31 March year end):
FY26 actual adj EPS: 0.80p
FY27E adj EPS: 1.2p (+50% vs FY26)
FY28E adj EPS: 1.9p (+58% vs FY27)
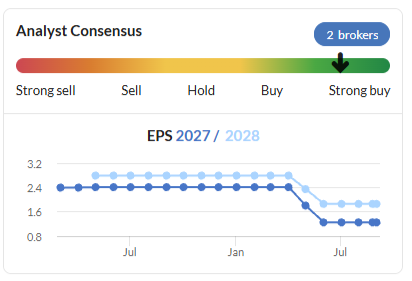
These estimates are in line with the consensus view (from two brokers) on the StockReport:
Roland’s view
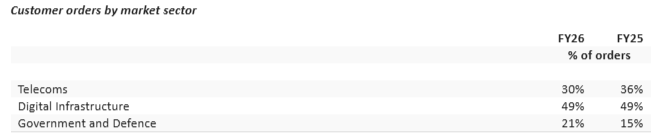
Calnex has significantly reduced its exposure to the telecoms sector, which was previously its core business. This only generated around 30% of revenue last year, with the balance coming from the faster-growing Digital Infrastructure and Government & Defence segments:
Encouragingly, customer tenure remains strong. Last year saw 79% of revenue come from repeat customers, with the company’s top 10 customers boasting an average tenure of 13 years.
Perhaps the only slight negative last year, in terms of diversification, was that customer concentration increased. Calnex’s top ten customers generated 56% of FY26 revenue, up from 46% in FY25.
I think it may be possible that Calnex has rotated its previous overexposure to the (cyclical) Telecoms sector into a heavy exposure to the hyperscaler and data centre market. This too may be vulnerable to a slowdown at some point, if the AI build-out slows.
While I still think this is an interesting business with good medium-term potential, I think the current valuation already prices in plenty of continued growth:
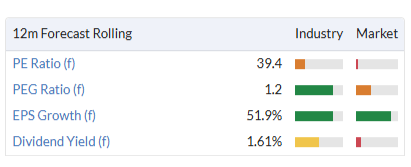
A PEG ratio of 1.2x looks about right to me, in terms of valuation, so I’m going to leave our neutral view unchanged today.
See what our investor community has to say
Enjoying the free article? Unlock access to all subscriber comments and dive deeper into discussions from our experienced community of private investors. Don't miss out on valuable insights. Start your free trial today!
Start your free trialWe require a payment card to verify your account, but you can cancel anytime with a single click and won’t be charged.