A Guide to Investing in Japan

All of us at some point will have played tunes on a Sony Walkman, driven a Toyota, or watched our favourite TV programme on a Panasonic. Japanese companies are responsible for some of the world’s biggest brands and most popular products that we use on a day-to-day basis. Stockopedia is therefore pleased to announce that we will soon be providing investors with the data they need to analyse stocks in the Land of the Rising Sun. We have put together this guide to help you gain a deeper understanding of Japanese stock markets and further explore investment opportunities in the East.
Why?
Economic Powerhouse
Towards the end of the 19th Century Japan became the first Asian economy to industrialise. It has been a global economic powerhouse since the country's 'economic miracle' gathered momentum in the years after the second world war. An important factor supporting this 'miracle' was the emergence of keiretsu - essentially groups of companies with interlocking business relationships, that shielded constituent firms against foreign competition and takeovers. Many familiar companies emerged under and are still part of these keiretsu. For example, the multinational conglomerate Hitachi is part of the DKB Group keiretsu. Toyota Motor and Toyota Industrial (the world's largest manufacturer of forklift trucks) are both, you guessed it, part of theToyota Group keiretsu.
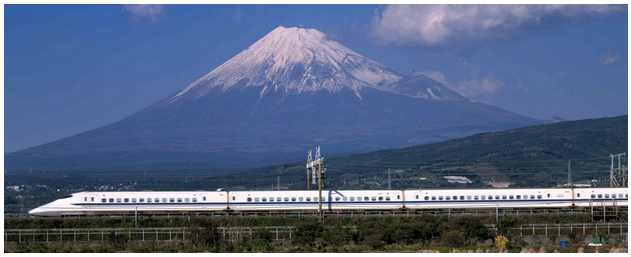
Much of Japan's economic growth in the post-war period was based on the expansion of manufacturing in areas such as automobiles. Today Japan remains the world's largest automobile manufacturing country and is of course home to companies like Toyota, Honda and Nissan. Looking beyond manufacturing, Japan is currently the world's third largest economy in terms of GDP and the fourth largest in terms of Price Purchasing Parity (PPP).
Technology Leader
 Japan has gained a particularly strong reputation as a world leading producer of high-tech goods. Several socio-economic factors are conducive to this technological innovation. The country has a high R&D spending to GDP ratio, and on the demand side Japanese consumers are generally 'early adopters' who embrace new technology before most other people. Historically Japanese companies like Casio and Sony introduced gadgets like the portable calculator and the Walkman. Today Japan remains a technological leader, recently ranking 4th in Bloomberg’s Global Innovation Index, ahead of Germany which ranked 5th and the UK which trailed behind in 16th place.
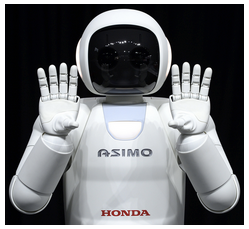
Japanese companies have made some particularly interesting developments in fields such as robotics. Honda has developed a robot, the ASIMO, which has the ability to recognise moving objects, sounds and faces - enabling ASIMO to interact with humans, so C3-PO had better watch out..!
Managing Risk
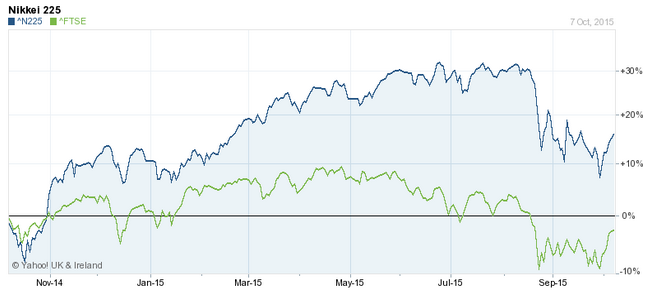
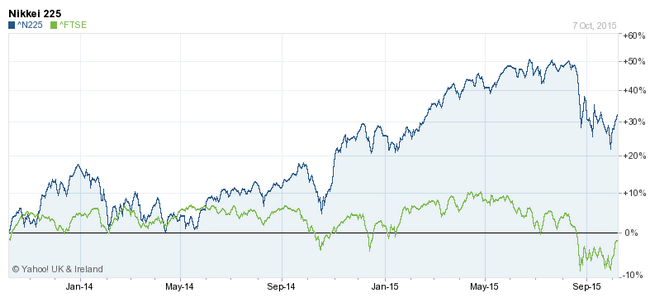
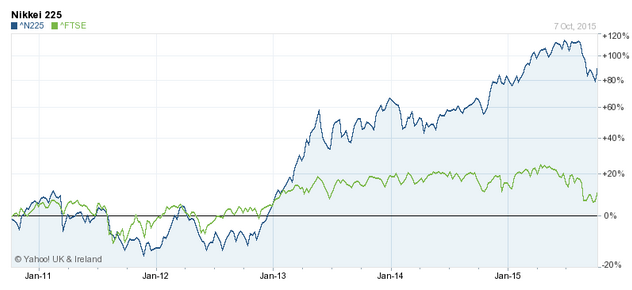
Harry Markowitz, a pioneer of modern portfolio theory, described diversification as the only free lunch in finance. Investors can reduce risk and improve returns by diversifying across different countries and geographies. Many readers may assume that the Nikkei has been flat or has even trended downwards in recent years. However, we can see from the charts below that the Nikkei 225 has outperformed the FTSE 100 over the last one, two and five years. Over the past five years investors would have therefore been able to reduce portfolio risk by gaining exposure to the Nikkei.
What?
What are the major Japanese exchanges?
The main stock exchange in Japan is the Tokyo Stock Exchange - T?sh? or TSE for short.  This is the fourth largest stock exchange in the world in terms of market capitalisation. Over 2000 companies trade on the TSE and they manufacture many of the gadgets and products that we see all around us. If you haven't printed this article off to read, you could well be viewing this page using a laptop made by Toshiba, which listed on the TSE back in 1949! On a more personal note: I spent (my mother would probably say 'wasted') many childhood hours playing computer games like Sonic the Hedgehog, Crash Bandicoot and Super Mario Bros. The TSE is home of the companies that make these games, namely Sega, Sony and Nintendo.
 Investors may also want to check out the sogo shosha. These are massive Japanese conglomerates that operate across a wide range of industries. One of the largest (and more familiar) sogo shosha is Mitsubishi, which started as a shipping company in the 1860s and now operates across several business segments, including finance, energy, machinery, chemicals and food. The seven major sogo shosha (Mitsubishi, Mitsui, Sumitomo, Itochu, Marubeni, Toyota Tsusho and Sojitz) are all publicly listed and trade on the Tokyo Stock Exchange.
TSE firms are assigned to one of three segments; the First Section for large companies, Second Section for mid-sized companies, or Mothers for emerging stocks. The listing requirements for the First and Second Sections (Main Markets) are essentially the same and are stricter than the criteria for listing on the Mothers market. To list on the Main Markets a company must usually have a market cap of at least 2 billion yen (£10.9m) compared to 1 billion yen on Mothers. In addition, to list on the Main Markets companies must have generated 500 million yen in profits during two years preceding the IPO. There are no profitability requirements to list on Mothers.
What are the major Japanese indices?
The Nikkei 225 Index (commonly known as the Nikkei) is widely used as the main benchmark for Japanese stocks and is actually the oldest index in Asia. It is named after Japan's main financial publication, Nihon Keizai Shimbun (or Japan Economic Daily). Unlike other major indices like the FTSE and the S&P 500, the Nikkei is a price-weighted index, meaning that each stock takes up a weighting in proportion to its share price, rather than market capitalisation. As such, the Nikkei is calculated using the same method as the Dow Jones. Indeed, until 1985 the Nikkei was known as the Nikkei Dow Jones Stock Average. The 225 index constituents are reviewed periodically. Sector balance and liquidity are two criteria assessed when selecting constituents. Current constituents include Japanese blue-chips like Toyota and Mitsubishi.
The Nikkei 225 tracks a relatively small number of stocks compared to the Nikkei All Stock Index and the Nikkei 300 Index. The latter two indexes are market value-weighted (ie. stocks take up their respective weightings in proportion to their market cap). The All Stock Index tracks all stocks listed on Japanese stock exchanges, while the Nikkei 300 Index was designed to represent the overall Japanese market, albeit with smaller number of firms (300 companies). The constituents of the Nikkei 300 are reviewed periodically and are selected using similar criteria to the Nikkei 225.
Another important index is the Tokyo Stock Price Index, or TOPIX, which is a cap-weighted index tracking all firms that are considered to be under the 'first section' on the TSE. Many readers also may be interested in Japanese stocks that have exposure to the Chinese economy. They may want to check out firms that are constituents of the Nikkei China Related Stock 50 index. This comprises 50 stocks from major Japanese companies that are selected based on 'how actively companies expand businesses in China'.
There are also FTSE and S&P indices that track Japanese equities. The FTSE Japan All Cap Index is a market-capitalization weighted index representing the performance of Japanese large, mid and small cap stocks. In addition, the S&P Japan 500 is designed to represent the Japanese investable market and constituents represent the large, mid and smallcap components of the Japanese equity markets.
How?
Which brokers provide access to Japanese markets?
One of the first questions readers will ask is which brokers allow their clients to trade Japanese stocks. We've put together this list of brokers who do cover Japan:
- AJ Bell Youinvest;
- DeGiro;
- Redmayne Bentley;
- Daniel Stewart;
- Saxo Bank;
- Killik & Co;
- Interactive Brokers.
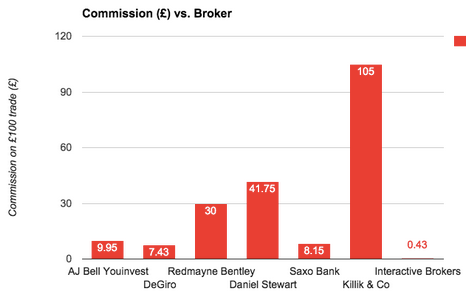
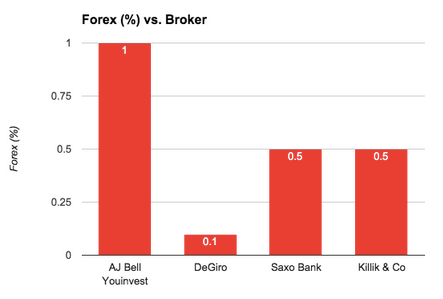
One of the cheapest brokers is DeGiro. They charge €10.00 per trade (in addition to 0.05% of the trade's value) although they do not yet offer tax-wrapper accounts (ISAs and SIPPs). They claim these will be available soon. Interactive Brokers charge a minimum commission of 80 yen (43p!) while Saxo Bank levy minimum commissions of 1500 yen (£8.15). We've put together these charts which compares the respective trading commissions and forex fees levied by each broker.
Do UK investors pay taxes on Japanese stocks?
Under Japanese law, withholding tax is imposed on Japanese dividends paid to foreign shareholders at 20%. Withholding tax is essentially a tax deducted at source by some countries on dividends paid to a person resident outside that country. Fortunately the UK has signed a tax treaty with Japan so the rate of withholding tax for individual investors falls to 10% (see here).
Capital gains derived from the sale of Japanese shares are usually subject to Japanese income, corporation or capital gains tax. Unfortunately there seems to be a paucity of free online resources on the exact rates paid by overseas investors. Readers should DYOR on this front and of course seek appropriate professional advice where necessary. These resources should help readers get started:
Conclusions
We will be producing StockRanks for all of the Japanese stocks discussed in this article as we go forward and will be tracking them in the GuruScreens. Users will also be able to make decisions on Japanese stocks by analysing fundamentals laid out on the StockReports. This article was put together to provide a basic overview why and how investors should approach Japanese stock markets. If investors have any experience of investing in the Far East, do please leave your own opinions below.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
3 comments
Hi Wombat,
Many thanks for this. I agree re Japanese accounting. In Japan, Goodwill is amortised over a twenty year period. Elsewhere, Goodwill does not need to be amortised; instead it must be tested for impairment annually and if there is no impairment Goodwill can remain on the balance sheet indefinitely. So in this sense Japanese accounting is more conservative given that a company is much more likely to incur losses from amortisation.
With regards to R&D, US and Japanese GAAP are perhaps comparable. As you point out, R&D is expensed in Japan. Likewise, under US GAAP R&D is expensed as incurred. IFRS standards are perhaps a little less conservative as the R must be expensed while the D can be capitalised. What are your thoughts here?
Over the next few weeks I'll try to find time write an article comparing Japanese to other accounting standards.
Best,
Alex
My only experience is with funds, I bought 2 about 18 months ago, Schroder Tokyo and Legg Mason IF Japan Equity. Schroders is up about 18% and Legg Mason about 90%, I have now sold both, Schroders some time ago and LM more recently. My concern is China if that goes then Japan will quickly follow. As per individual companies I don't know enough about them, for me its better to invest in funds, easy to trade, no currency or broker or tax issues and can hold in an ISA.
Not a bad introduction but may I be allowed to makea couple of small clarifications?
Japan, as a manufacturing base, is the 3rd largest producer of autos and commercial vehicles after China and the US. Japanese domiciled companies produce easily the largest numerical amount of vehicles but approx. 2/3rds of their production is offshore. This is principally a result of the long-term appreciation of the yen.
It is also worth mentioning that Japanese domestic accounting is quite different to that practised in the UK. It is generally considered much more conservative due principally to the treatment of R&D, which is generally expensed entirely on the P&L, and goodwill which is amortised annually. However, companies with dual listings in the US also produce GAAP accounts and these are the bulk of internationally known Japanese corporations.