AMP: Has the turnaround begun?

AMP (ASX:AMP) listed in 1998 and the price immediately spiked to $29.64 (adjusted for dilution). It immediately dropped back to around $12 and then began its multi-decade descent to today’s level of $1.26. There have been some brief periods of cheer, most notably in the early 2000s, but for the most part it has been pretty miserable.
And then came the Banking and Financial Services Royal Commission in 2018. Sensational revelations of charging fees to deceased people pummeled their reputation and heads rolled, including the CEO and Chairman. Since then the business has endured further travails with subsequent chairman and CEO both compelled to resign.
Two years ago Alexis George was appointed to the top job and commenced a program of trying to simplify the business and focus on their core strengths. These include the bank and the wealth management business. AMP Capital and the Life Insurance business have been sold. They have not yet given up on the financial advice business although it continues to operate at a loss.
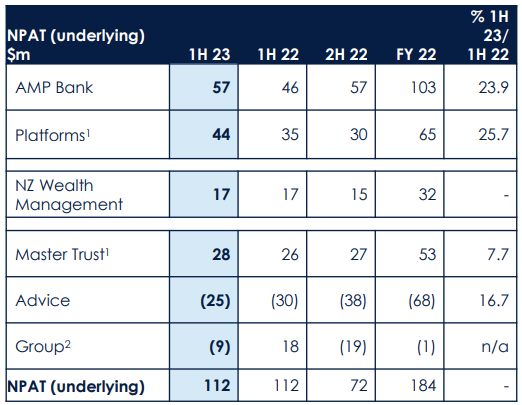
The changes at AMP have been quite extraordinary. Revenue in 2013 was over $19 billion. It is forecasted to be $1.3 billion in 2023. Profit has fallen from $672 million to a forecast of $210 million. Profit over the last 10 years peaked in 2015 at $971 million. The breakdown of net profit from the first half of 2023, as shown in the table below, shows how the composition of the business has changed. The Bank is now the largest contributor and Advice has been operating at a loss.
We have just completed a report detailing the gravity of change of factors for all ASX 200 stocks. AMP was one of the top performers in terms of the magnitude of change in a positive direction. The table below shows the magnitude of change for each factor ranking as well as the overall StockRank. (Note, the change is measured from the 5th of August to the 5th September. AMP reported their half year results on the 10th of August.)
Quality | Value | Momentum | StockRank | |
Pre report | 26 | 77 | 57 | 55 |
Post report | 51 | 76 | 91 | 82 |
Change | 96% | -1% | 60% | 45% |
The recent half year result was the first sign that they may have turned the corner and started to put the past troubles behind them, getting the company moving forward as a much simpler organisation and focusing on their strengths in wealth management and banking.
The Quality Score is still low at 51, but it almost doubled after the report. Importantly the Piotroski F-score went from 4 to 6. This was assisted by the repayment of over $300m in debt as they reduced their long term corporate borrowings.
Their free cash flow per share is also a lot stronger now than it was a few years ago. This has enabled them to return capital to shareholders. They returned $610 million in capital over the last 12 months. They also resumed paying dividends in 2023 after a two and a half year hiatus.
Revenue for the half year declined by 2.5%, but they managed to increase underlying EPS by 12%.
But the woes of recent years are not completely behind them. They have temporarily suspended their buy-back whilst waiting for more certainty on class actions that have been filed against them. In late August they settled a shareholder class action for $110m without making any admission of liability. They have made another provision of $50m for a class action being brought by their financial advisers who are unhappy with the changes to the Buyer of Last Resort (BOLR) provision that formed part of their agreement with AMP.
Market momentum has reflected this turnaround sentiment. The Momentum score has increased by 60% in the last month. This reflects the relative share price strength, especially over six months as well as the uptick in analysts earnings expectations over the last month.


Financial services businesses are built on trust. Trust in AMP was almost destroyed following the Royal Commission. It is not yet certain if that trust has been restored. Assets under management are still experiencing net outflows although the amount was fairly small in the last half. The Banking division is managing to grow its customer base as well as increase its mortgage book at a higher rate than the rest of the market, therefore increasing its market share.
An investment in AMP would reflect a belief that they are now on track to start growing a profitable business that is focused on its key strengths. From a valuation perspective, it is no longer the bargain that it was when it was trading near $1, however it is not expensive either, and some of the risk has been removed. If it can continue its transformation we may look back in a few years time and say that it was a great turnaround opportunity, however without the benefit of hindsight, it is only suitable for those with a healthy appetite for risk.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?