Can you beat the market with Investment Trusts?

A recent MoneyWeek survey found that Investment Trusts are the second most popular investment in the UK after regular stocks and shares. Trusts are even more popular than mutual funds with UK private investors. Many readers will therefore be pleased to learn that we plan to provide more in depth analysis of UK Investment Trusts at Stockopedia.com as we go forward.
A key feature of our coverage will be a ranking system which seeks to identify Investment Trusts that have a higher probability chance of beating the market (ie. a TrustRank). We’ve already started to research the datapoints to include in a TrustRank. We thought we’d share our initial findings with you and throw it open to debate.
What is an Investment Trust?
Before getting into the nitty gritty, let’s take a moment to understand what Investment Trusts are. Investment Trusts (also known as closed-end trusts) are publicly traded companies, but while companies like Apple make money by selling phones, and firms like HP sell printers, Investment Trusts make money by investing in other companies.
Trusts build portfolios of stocks, bonds and other investments (eg. property). In a nutshell, if you take account of liabilities, and divide the value of a Trust’s portfolios by the number of shares the Trust has issued, you get the Net Asset Value, or NAV (see below).
NAV = Trust’s Assets - Liabilities / Number of Shares the Trust has issued
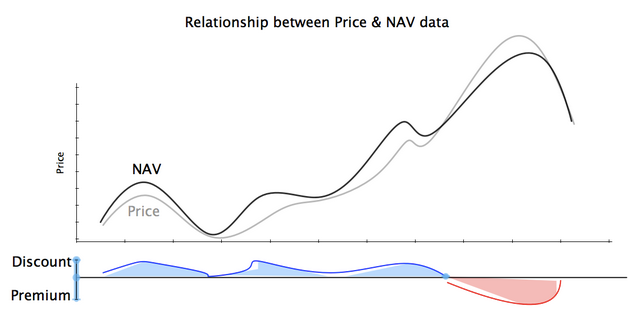
However, because Trusts are publicly traded companies, their share price is determined by investor sentiment and the forces of market supply and demand. This means that share prices can become lower (or higher) than the NAV, creating opportunities for investors to buy Trusts at a discount (or premium) to the NAV (ie. the assets and investments which Trusts own). Is the mismatch between the NAV and the share price a dream come true for value investors…?
Cheap beats expensive
Benjamin Graham, the father of value investing and tutor of Warren Buffett, was amongst the first to notice that the value effect can work for Investment Trusts. He advised that 'if you want to put your money in investment funds, buy a group of closed-end shares at a discount of, say, 10% to 15% from asset value.' Why? Trusts trading at a discount tend to beat Trusts trading at a premium, at least over the longer run.
Graham made this observation in The Intelligent Investor, which was first published in 1949, but academic research since then has further corroborated Graham's findings.
- In 1978, Rex Thompson found that between 1945 and 1975, Trusts trading at a discount to NAV beat the market by around 4% annually, while Trusts trading at a premium underperformed the market.
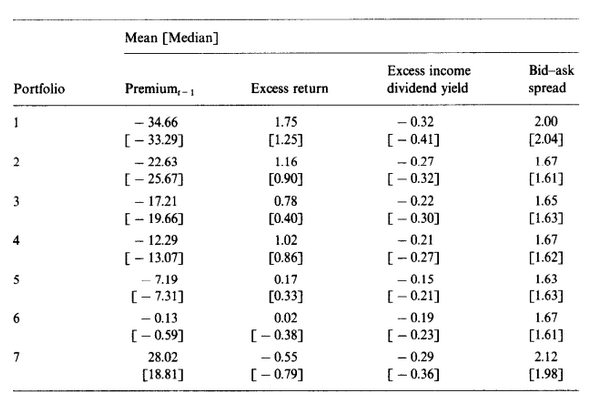
- Similarly, in 1995, Pontiff found that shareholders of funds with large (small) discounts earned large (small) returns (see below).
Blending Value with Quality
Investment Trusts may trade at a discount, but what if there is something wrong with them...? Indeed, investors should be wary of value traps - Investment Trusts which are cheap because they are low quality junk companies. But how can we measure the quality of an Investment Trust?
NAV Returns
Jim Slater pays close attention to the long-term NAV returns (ie. the change in the NAV's value over a given period). If the NAV goes up, it is often the case that an Investment Trust’s portfolio has appreciated in value. A high quality Investment Trust may generate higher NAV returns. Accordingly, Slater advises that 'the factors to consider when choosing an Investment Trust are the long-term performance record [inc. the NAV returns], the level of gearing, and the discount to NAV.' We'll come back to gearing later. But first let's explore why Trusts with higher NAV returns might also generate higher share price returns.
The answer is quite straight forward. Perhaps unsurprisingly, investors are usually prepared to pay higher prices for Trusts with stronger NAV returns. Investment Trusts magazine used to invite financial analysts to make recommendations of their preferred Trusts, with a paragraph of justification. Over the period 1997-2000, there were 83 recommendations of conventional Investment Trusts. According to Bleaney, past performance or the quality of management was cited as a reason for buying the Trusts in 51 cases.
This is of course anecdotal evidence, but the numbers tell a similar story. In The Intelligent Investor, Graham showed that Trusts selling at premiums had often generated stronger long-term NAV returns (see below).
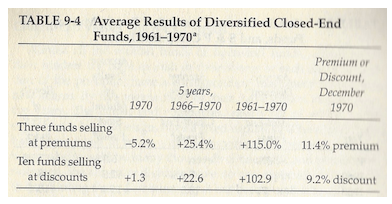
Admittedly, Graham only used a sample of thirteen Trusts. But more recent studies which examine larger samples also suggest that Trusts with stronger NAV returns are more expensive. For example, Dimson and Minio-Kozerski analysed nearly 400 UK Trusts and observed that when 'funds are ranked on past managerial performance, measured over one, two and three years, and allocated to deciles, the worst performing portfolios tend to be characterised by wider discounts.'
Volatility of NAV Returns
A checklist that only uses two datapoints (the discount and NAV returns) might not sound watertight. Can investors use other criteria? Some investors judge the quality of a company by looking at the volatility of earnings and sales growth. Poor quality companies may enjoy rapid sales growth one year, before sales jump off a cliff the next. Conversely, high quality companies may generate more stable, less volatile sales each year.
Similarly, higher quality Trusts may generate more consistent, less volatile NAV returns. Academic research suggests that investors pay higher prices if NAV returns are less volatile. For example, Dimson and Minio-Kozerski defined the ‘residual risk’ as the volatility of NAV returns and observed ‘the higher the residual risk, the higher is the absolute value of the discount.’
Other factors to consider
If Trusts with higher, more stable NAV returns are usually more expensive, it follows that an undervalued Trust could perhaps be one that trades at a discount, but has also generated stronger, more stable NAV returns over time. However, the economist John Maynard Keynes warned investors that ‘markets can remain irrational a lot longer than you and I can remain solvent.’
What does this mean? A Trust may be undervalued, but investors won’t make any money until the rest of market recognises and exploits the investment opportunity, driving the price up. So any investment strategy should take account of the factors which might prevent investors from buying undervalued Trusts. Such factors could include the dividend and the bid-ask spread.
- Bid-Ask Spread: Companies with wider bid-ask spreads are less liquid and are more difficult to trade. Transaction costs are higher, so if a Trust is undervalued, it may take longer for the discount between the price and the NAV to narrow. Indeed, Pontiff (1996) showed that Trusts with larger discounts often had wider spreads.
- Dividend Yields: Pontiff also explained that it was easier to invest in undervalued Trusts that pay dividends. This is because dividend payments can be used to partially offset the costs of borrowing money to invest. This helps to explain why Pontiff found that companies with lower dividend yields traded with wider discounts. However, it could simply be the case that investors are happy to pay higher prices for companies which pay out cash dividends.
Putting the pieces together
In a nutshell, the academic literature suggests that discounted Trusts beat Trusts which trade at a premium. Furthermore, Trusts trade with a narrower discount when: the NAV returns and dividend yields are higher; and the bid-ask spread and volatility of NAV returns are lower. Putting it all together, finding trusts that are both at a discount but have stable NAV returns and tighter spreads ought to lead to further outperformance.
Of course, at Stockopedia we’ve become best known for our equity indicators. The high StockRank stocks have outperformed the market, the low StockRank stocks have underperformed. If past trends persist, then by analysing the top Investment Trust equity holdings we may be able to find those Trusts whose holdings position them best for equity led outperformance.
So to sum up some of the factors we are considering entering into our Investment ‘TrustRank’ include the following:
- trade at large discount to NAV;
- generate strong long-run NAV returns;
- generate stable, less volatile NAV returns;
- have a high dividend yield;
- have a low bid-ask spread;
- and own a portfolio of high StockRank stocks.
We’d be interested to learn about your reaction to these ideas, or even if you have a few of your own. These metrics are under development so please add your comments below...
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
52 comments
This is a good start. I would like the data presentation to show me how the discount has changed over time. For example on existing stock reports I can see a bar graph of turnover each year, which shows whether sales are increasing or decreasing. In the same way, I would like to be able to see at the very least an annual bar chart of the discount.
Given how important the discount is, even better would be being able to see the daily discount history graph at the top, in the same way (and probably overlaid over) the way one sees the share price history graph.
Hi Mohammed, you wrote:
"This is a good start. I would like the data presentation to show me how the discount has changed over time."
I'm afraid that Stockopedia at present doesn't even display the current value of the discount, let alone how it has changed over time.
There was talk, a couple of years ago of setting up an IT or OEIC based around the stockranks. Has that fallen by the wayside?
I think that rating trusts would be helpful. Why have there not been any comments in 2018?
Another downside to OEICs / Unit Trusts is that some major platforms charge extra fees for holding them.
Can you beat the market with Investment Trusts? - a most definite Yes.
Some years ago when I first got interested in investing, ISAs etc. I found the whole range of available investments confusing and overwhelming. Over time things sorted themselves out and I found myself looking more and more at ITs as a nice self-contained area. It provided me with a range of company sizes from FTSE 100 / 250 constituents down to minnows, in turn covering a whole range of sectors, regions and so on. If I set a minimum capitalisation size of £20 million that left me with a workable range of trusts to choose from.
More by chance than planning I found I was / am happiest as a ‘momentum investor’, as in if I see that a trust had been consistently rising over the last two or three months then that's a trust that I'm interested in. I look to hold any given trust for between 6 months to a couple of years, selling it as it falls out of fashion and replacing it with something more interesting that's on the up. Working on this principle I have consistently outperformed the FTSE100 index.
The one thing I have never bothered worrying about is a trust’s NAV. When I buy a trust I don’t pay my stockbroker its NAV price but the market maker’s Offer price, and likewise when I come to sell it is the Bid price that going to end up in my account. So it’s these and how they have changed over the last weeks or months are the principal data points I’m concerned with.
In the end I guess each person must just find what works best for them.
Hi BlackKettle,
If you are a pure momentum investor, I wonder whether nowadays you would be better off buying OEICs rather than investment trusts. This is because nowadays, if one buys an OEIC through a platform such as Alliance Trust Savings, one does not usually pay an initial charge on an OEIC, whereas if one buys an IT one usually has to pay Stamp Duty of 0.5% and suffer a bid-offer spread. So a policy of buying OEICs with high momentum would have lower transaction costs than buying ITs with high momentum.
I have used OEICs / Unit Trusts but they don’t suit my character.
I can take ages to make a decision; if I want to buy a camera I’ll do my research, wait for the right model etc, but once I decide to do something I like to act on it immediately, right now! So this idea with OEICs where when I want to sell I have to submit my sell order, I don’t know the exact price I’m going to get, my order will probably get actioned the next day (or even the day after if the timing works against me), I’m not too sure exactly when I’m going to get my money. Then having to repeat this process for the next buy and finding this sell / buy routine can take many days / a week… just not my personal style.
Compared to a sell / buy routine with ITs (or any standard share) where you know the exact prices you are working with and the where the total time taken for the whole sell then buy routine can be less than the time to boil a kettle… that is something I’m happy with.
Who's to say that in the future I may go back to OEICs (especially where I may be more interested in income rather than capital gain) but at the moment I’ll stick with my shares.
Each person to their own.
As for Alliance Trust Savings. I was with Stocktrade for many trouble-free years but then Brewin Dolphin (the owners) wanted out of that area of the execution-only trading so sold Stocktrade to Alliance Trust Savings. It must be about 1 in every 4 on-line trades I now do I end up having to ring Alliance because their system gives problems. Very disappointed with their level of service.
Dear Stockopedia,
I understand that you have bought data for investment trusts many months ago, but you have not gotten around to making that available to Stockopedia subscribers, because other work has been considered to be a higher priority. In view of that, would it be possible, in the near future, for you just to add 'premium/discount to NAV' to the information that you already provide on investment trusts? I and I suspect many other Stockopedia subscribers would find that very useful, and I would not have thought it would require much programming effort to implement.
"Started my Sipp years ago with just Investment Trusts
Does anyone else combine their selection with momentum?
And how do you do it?"
Recently, I've been selecting investment trusts that have higher than average 1-year share price past performance with higher than average discounts to NAV, i.e. they have both momentum and value. If the good share price perfomance of an IT relative to other IT continues, I will continue to hold it regardless of what happens to the discount. If the share price performance of an IT deteriorates badly relative to other ITs, I will sell that IT regardless of what happens to the discount. But if the share price performance reverts to the average of other ITs, then I will continue to hold it if the discount stays higher than the average of other ITs, but I will sell it if the discount narrows to a value lower than the average of other ITs.
Started my Sipp years ago with just Investment Trusts
Does anyone else combine their selection with momentum?
And how do you do it?
After selection I use simple moving averages for buying and selling indicators
Glen Keedy - Phil Oakley did a good article and has the Z-score
http://www.sharescope.co.uk/philoakley_article142....
Sorry Edward not trying to advertise the opposition
Personally I would be reasonably happy if Stockopedia in the near future just added 'premium/discount to NAV' to the information that they already provide on investment trusts.
Does anyone know of a website that has investment trust data with current z scores? I've tried Morningstar, bestinvest, trustnet, the AIC
Cheers
Glen
Useful introductory piece from Phil Oakley on the basics of assessing ITs. Premium/discount to NAVs, Z-scores, gearing, expense ratios etc.. Leads into a more detailed analysis of how ShareScope can be used to screen the various factors. Hopefully something along the lines of what will become available on Stockopedia in due course.
https://www.sharescope.co.uk/philoakley_article142_f.jsp
Definitely a gap in the coverage at the moment IMO.
Best,
Gus.
Great Minds-
.... Think alike, though fools seldom differ.
Why am I laughing!!
Ed Croft wrote in a reply to me on another thread:
"Regarding Investment Trusts - we've bought the data - and I'm sure it will be launched soon enough ... after everything else in front of it !"
Please vote here - http://ideas.stockopedia.com/forums/18977-stockopedia-suggestions/suggestions/2416805-add-nav-data-for-investment-trusts
Can I just add my support to this - I think ITs are an excellent way to get exposure to areas that are either inaccessible (many foreign shares) or where I clearly don't have the knowledge (Biotech, Mining etc).
Just seen this come up - I would love a 'trust rank' feature as the majority of my portfolio is in ITs. Please Stockopedia - Can you look into this further?
Agree with the recent comments, a Trust Rank feature would be very helpful and would be a worthwhile addition.
Also, as mentioned by tournesol, John Baron is is well worth following. If not a subscriber to his service you can always see his views on the Investors Chronicle web page for free.
I have also expressed support for the TrustRank feature in the past. I hope to see it introduced in the near future - it would help with the different focus portfolios that I run for myself, my wife and our children.
I've been waiting patiently for several years now, an update about its launch would be good.
Have invested in Investment Trusts and their few sub shares available, for years. Stockopedia is superb for shares, but not for Investment Trusts, so would also welcome a trust rank and much fuller information/figures for them too. .
Me too, I would love to see this feature added
Ditto, would really like a Stock rank for Investment Trusts
I'm also a big fan of investment trusts so would be pleased if Ed or Alex could give an indication of when the Trustrank feature is likely to start
Hi almain,
Further to my previou post, I perservered and I did eventually manage to create a fantasy fund. However, it does not display all the different things that are displayed in a private folio. For example, I can't get the fantasy fund to display the dividend yield of each investment trust. So a fantasy fund is no good for my purpose, which is to allow other people to sort popular investment trusts by various criteria, such as yield and bid-offer spread, to help them with deciding which ITs to buy for their own portfolios. I've therefore deleted that fantasy fund.
Hi pka, I did discover "Fantasy Funds" under the "Discuss" menu. You could put your portfolio under there?
Ed, I too am interested about getting IT's into the Ranking system. I run about 75% of my portfolio in IT's.
Hi almain,
Thanks for mentioning the 'Fantasy Funds' option under the 'Discuss' menu. I've just tried to create a new fantasty fund, but I found it incredibly frustrating and abandoned the attempt. This was because every time I entered some information, I got a message saying there was something wrong with what I'd entered and all the information that I had entered correctly was lost, so I had to start again from scratch.
I too am interested in Investment Trusts.
I have found John Baron to be a useful source of information and ideas. He has an interesting CV. Soldier, fund manager at Rothschilds and currently Conservative MP (the only one who voted against Iraq and Afghanistan) He is a recognised expert in the field of IT's and writes for the Investor's Chronicle on the subject. He has his own website - subscription £150 p/a - which runs half a dozen virtual portfolios of IT's with trades being published in real time, a post facto rationalisation of trades and comments on IT's that he considers of interest at the present time.
I happily pay the subscription but you can get a week long trial for free. Other than my subscription I have no connection.
It would be brilliant if Stockopedia could somehow link up with JB to make his ideas available via Stockopedia and vice versa. Could be a real win-win.
Howard, You're welcome.
For what it's worth, I have Capital Gearing Trust, Personal Assets and Ruffer in my portfolio. They're there in the hope that they will reduce the total drawdown of my portfolio during a bear market in equities, but still provide some limited growth during bull markets. All three have discount control mechanisms in place, which means their share prices tend to stay close to their Net Asset Values, with only small discounts or premia. That removes a common concern with investment trusts that they might be on a wider discount when you sell them than when you bought them, which is particularly important during bear markets when IT discounts tend to widen. I'm not sure whether any of the other investment trusts mentioned in the article have discount control mechanisms.
At a time when stock markets have been falling in recent weeks, the following article about investment trusts with 'multi-asset’ strategies may be of interest to people who would like to diversify away from 100% equity portfolios:
http://www.trustintelligence.co.uk/investor/strategy/aic-flexible-investment-sector-strategy
pka, thanks for the link, that's useful to me.
Regards
Howard
I think you have looked into a stock ranks fund. Has anything developed on this?
At the moment I have some small funds that I manage such as junior ISA's where funds are my preferred investment, with less risk than single share which also have very high % trading cost for small value transactions.
Yes please.
Thank you for the excellent article Alex, I found it most enjoyable. I've been using IT's for over thirty years now and overall they have all served me very well indeed. However, I wish I could give you some direction but I have not been very technical in my methods for choosing which ones to buy, it has primarily been based on their prices, long term performance, where they have been investing, what their company objectives are and whether or not I like them! ~ That's it! I have kept things rather simple in that any IT's placed inside ISA's must pay fairly consistent dividends and the others should display consistent long term capital growth. Obviously there has been a great deal of time taken to choose such trusts involving the reading of many, many company reports and placing various figures (divs, NAVS, history, etc, etc) onto a spreadsheet for comparisons. Oh yes, the vital thing has been a non-stop subscription to the "Investment Trusts Magazine", which sadly is-no-longer and I do miss it! Anyway, Alex, your article is very interesting and I look forward to more Investment Trust contemplations from you in the near future. Many thanks.
Hi Alex,
One suggestion (which you may already be considered) is that the QVM ranking of the Trust is just the weighted sum of the stocks that make up the trust portfolio. That is treat the QVM ranking of the trust as purely a sum of its parts, based on its current stock holdings and weightings.
Whilst full info for all trusts holdings may be difficult to find the top ten holdings are published on a monthly time line. Data/rankings for some overseas trust holdings may well be more difficult.
But the overall aim here would be to find if the trust is holding a basket of highly ranked QVM stocks or a lower quality portfolio. Similarly other agregate metrics like PE, EPS growth, PEG, Divi yield, F-score etc. could be provided from the list of holdings and calculated in exactly the same way as in the Stockopedia Folio Analysis tool.
The TrustRank is a great idea, and I look forward to its release. (Definitely good to include IT costs too.)
Thanks all for the great feedback. We've had some amazing submissions through these comments and via email with academic papers and resources on Investment Trust discounts. There's a lot to take in. The TrustRank is under development but will be some time before it's released to the website. I hope we can do this well and fulfil expectations ! Thanks for your support.
Hi Ed,
You wrote back in June 2015 that "the TrustRank is under development but it will be 2016 before it's released to the website". It's now January 2017 and the TrustRank hasn't appeared yet - I guess because other great developments in Stockopedia had higher priority last year.
As I wrote in a comment on another discussion topic:
I found it very frustrating that I was unable to create screens on Stockopedia for Investment Trusts. What I was able to do, though, was to create a dummy portfolio on Stockopedia containing all the Investment Trusts that I might consider buying shares of. I find that useful, because it provides information about, and the ability to sort against, market capitalisations, spreads, dividend yields, Betas, and Share Price Changes over the previous 6 months, 1 year and 5 year, as well as the ability to view graphs of share prices over various previous periods for the Investment Trusts in my dummy portfolio. But it would be even more useful to me if Stockopedia would provide information about the discount of each Investment Trust to its Net Asset Value. As that is just a single item of data for each Investment Trust, Is there any chance of that happening in the near future?
By the way, I would be happy to make my dummy portfolio of Investment Trusts public so that other Stockopedia subscribers can use it if they're interested. However, I don't know how to make a portfolio public - could you kindly explain how to do that?
Hi Alex
I am delighted to hear about Trustrank. This step opens up Stockopedia to a much wider investing community which I'm sure will bring further developments and thus benefits to us all.
The exciting prospect I see however, and I applaud you for it, by you investing in the development of a robustly supported quantitative approach to investing in ITs, I believe you will in fact take an industry lead in helping investors invest in this important and useful asset class. In my view, you are therefore helping to democratise investing which is a particularly important and necessary thing to do for our societies who are living ever longer and must therefore make our investments work effectively. Good for you.
Lastly, many thank to all the previous commentators (above), I have learned a lot from reading your comments. In particular I concur about including in Trustrank measures which assess IT costs as these have a real impact on longer-term returns. By Stockopedia making them visible this might also add another important voice to encourage ITs to make all costs visible and more affordable.
Regards
Howard
Alex, you wrote in your article:
"So to sum up some of the factors we are considering entering into our Investment ‘TrustRank’ include the following:
trade at large discount to NAV;
generate strong long-run NAV returns;
generate stable, less volatile NAV returns;
have a high dividend yield;
have a low bid-ask spread;
and own a portfolio of high StockRank stocks."
I would consider adding the following factors:
have low annual management fees;
have low ongoing charges;
have no perfomance fees for management (but if they do have performance fees, they should be capped at reasonable levels and have high-water marks);
have low or no gearing, and any gearing they do have should not be expensive;
are registered as investment trusts in the UK rather than in an overseas tax haven;
have good long-term records of increasing dividends each year and have revenue reserves;
I would treat split-capital investment trusts as a separate category.
I would also treat any investment trusts that have significant parts of their portfolios invested in unquoted assets (such as private equity, hedge funds, directly-held property, and infrastructure debt) as separate categories.
It might also make sense to treat trusts that invest predominantly in UK stocks as a separate category from those that invest overseas.
The more I think about it, the less straightforward does your task seem!
Hi Alex, You wrote:
Dimson & Minio-Kozerski observe that "winners over the preceding year do not perform better than losers. On the contrary, performance measured over two and three years is characterized by a negative and significant rank correlation ? past winners tend to do worse than past losers...This finding is robust with respect to the length of the performance period: analysis based on six-month intervals (not shown here) yields similar results."
See here: http://citeseerx.ist.psu.edu/viewdoc/download?doi=10.1.1.22.645&rep=rep1&type=pdf
--------------------------------------------------------------------------------------------
The section you quoted in that paper refers to Table 6, which is entitled 'Share Price Performance Persistence', so it summarises share-price performance rather than NAV performance. I think a strong NAV return over the previous year is likely to lead to the discount narrowing in the current year; if one then buys the IT, the discount is likely to eventually widen back towards its long-term average value which will harm future share-price performance more than the momentum effect tends to enhance future NAV performance. But I do think there is a momentum effect on the NAV returns of ITs, although it might be a fairly weak one.
Hi, looks interesting. Do you have any idea on time frame for implementation?
Algy Hall in the Investors Chronicle, 3rd October 2014, outlines his simple IT screening strategy.
It's a value-momentum strategy which he names "Outperforming and Overlooked". (Interestingly, though, he says he's using momentum as a proxy for quality, because his preferred quality metrics for shares can't be applied to ITs.)
Minimum market cap is set at £100m.
Trusts are ranked on valuation by first excluding all trusts trading at a premium to NAV, and by then ranking the remaining trusts using their Z-scores, with the lowest Z-scores being the most highly ranked. (AH omits to specify the period over which the Z-score should be calculated. My guess is 1 year.)
Trusts are ranked by using 3-month momentum (3 month rate of change). (Price momentum, I think, is what he has in mind, rather than NAV momentum, though this is not actually specified.)
The value and momentum ranks for each IT are added together, with a ranking of the sums producing the overall value-momentum ranking.
The portfolio size is set at 10 ITs, with a holding period of 1 year; and there is a limit set on the number of niche trusts as well as an exclusion of trackers and hedge funds.
The screen backtested well over the preceding 10 years when he wrote it up in 2014, and the first few months of running it live, reported on 13th January 2015, were also impressive.
Algy Hall has updated on this and published a new list of ITs meeting his criteria
http://www.investorschronicle.co.uk/2015/09/29/shares/stock-screens/top-overlooked-outperforming-trusts-67IQucjQseuXwUi3reHRbK/article.html
This most recent article confirms that the screen is based on 3-month price rate of change (not NAV rate of change), and that the Z-score he uses is the 1-year Z-score.
Hi guys,
Thanks for the feedback.
Warranstar: We are still researching the momentum effect on Trusts. Our initial findings seem to contradict the existing literature on momentum (which suggests that past winners beat past losers). Stockopedia's MomentumRank gives a higher ranking to companies with stronger performance over the previous 6 months. However, research by Dimson & Minio-Kozerski suggests that winners over the previous 6 months do not outperform.
Dimson & Minio-Kozerski observe that "winners over the preceding year do not perform better than losers. On the contrary, performance measured over two and three years is characterized by a negative and significant rank correlation ? past winners tend to do worse than past losers...This finding is robust with respect to the length of the performance period: analysis based on six-month intervals (not shown here) yields similar results."
See here: http://citeseerx.ist.psu.edu/viewdoc/download?doi=10.1.1.22.645&rep=rep1&type=pdf
This is of course just one paper - insufficient on its own to inform the TrustRank. We will dig deeper and will of course change the TrustRank in light of our findings. It is also worth remembering that momentum will 'internally' be incorporated into the rank. Trusts with higher TrustsRanks may own high QVM stocks. Therefore, Trusts with higher TrustRanks may hold shares with stronger price momentum.
I hope this helps?
Best,
Alex
Providing details of management fees and on going charges would be useful as cheap tends to beat expensive.
In addition on the yield it is also useful to look at the level of revenue reserves in relation to the current level of dividends. If the reserves are higher then you would have greater confidence in the dividend being maintained or steadily increased. Indeed this is how some trusts have been able to increase dividends for 40+ years.
Bleaney published another interesting academic paper in 2004 entitled 'Past returns and investment trust discounts', which can be downloaded from this web page (but unfortunately only if one is prepared to pay some money for it):
http://onlinelibrary.wiley.com/doi/10.1111/j.0306-686X.2004.00582.x/abstract
That paper contains the following paragraph in its Section 4:
"Could an arbitrageur significantly improve on pure discount arbitrage by exploiting regression (17) in Table 9, i.e. by taking recent NAV returns into account? That regression suggests an alternative rule: go long on the trust with the highest sum of the discount and one-year NAV returns, and go short on the trust with the lowest such sum. The rationale behind this rule is that the lagged discount and one-year returns have approximately the same coefficient in regression (17). This discount-return (DR) rule improves on the pure discount rule, increasing mean returns before trading costs by a further 1.1%. The snag is that, because NAV returns are essentially random, the DR rule involves significantly more trading (65 switches out of a possible 96). The extra trading costs reduce average returns by 0.4%, so the DR rule improves on the pure discount rule by only 0.7% after trading costs."
This suggests that ranking investment trusts in a particular category (e.g. ones investing in shares quoted on the UK stock market) by the sum of their discount plus their NAV return over the immediately previous full year, and buying those investment trusts that are ranked highest according to that criterion, might lead to future out-performance of the relevant index. At any rate, it might be worth Stockopedia doing some research on that strategy.
If that strategy does work, the possible reasons why it works might include some sort of momentum effect.
One thing to bear in mind about investment trust discounts is that published figures for both discounts and Net Asset Values can be unreliable for investment trusts that have high proportions of unquoted investments in their portfolios, such as private equity or directly-held property.
I am delighted to hear about the imminent introduction of Trustranks as I hold several IT's in my portfolio as the 'building blocks'. To research them up to now I have had to refer to Morningstar or similar competitors. I find it especially important to look at discount to NAV & also the main holdings of the IT. As I also have a portfolio of individual small cap stocks I don't want to replicate them in an IT.
It's always good to have one's investment decisions grounded on academic research, rather than just opinions or assertions. The above factors look useful. Particularly the analysis of the Stockranks of the shares owned by the investment trusts.
I notice that there is no mention of momentum. What does the research say about the momentum of investment trusts? If momentum for ITs is a useful predictor of future price movements, then could your coverage cover momentum too?