Covid-19 Sector Reviews: Financials

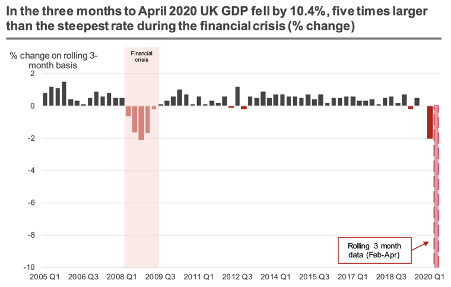
During the credit crisis of 2008-2009, the Financial sector was inevitably one of the worst affected. After the demise of Lehman Brothers and the daunting prospect of a collapse of the entire financial system, new banking and financial institution regulations were put in place to avoid a repeat ever happening again.
More stringent capital adequacy ratios were implemented after the crisis and the continued prudent supervision by industry regulators meant that banks and financial institutions entered the pandemic in the strongest position they have been in for decades. Despite this, the sector remains one of the worst performers since the start of the Covid-19 outbreak. The FTSE All Share Financials sector benchmark has dropped -20.17% since the start of the year, whereas the FTSE All Share has depreciated by -15.89%.
Source: PwC
This article will examine the Financials sector and its industry groups in detail, highlighting the performances of the industries so far. The article will also evaluate the valuation metrics of the industry groups and focus on a few of the top-ranking stocks within the sector to identify how these companies are responding to changes in the financial system as a result of the pandemic.
Performance of the Industry Groups
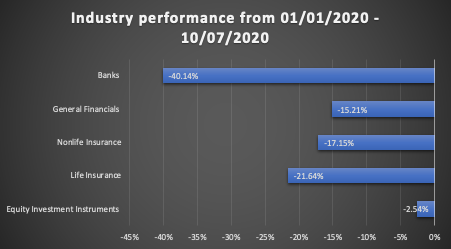
Falling by almost twice as much as any other industry in the Financial sector, the Banking industry has suffered staggering losses so far. Its -40.14% fall puts it amongst the worst performing industries across all economic sectors.
The major banks have had to make significant provisions for potential loan losses and have had to cut their workforces to streamline cost structures. Lloyds, RBS and Virgin Money have all seen their values halve since the start of the year as a result of the ongoing challenges the businesses are facing.
Lloyds, for example, has seen its first quarter profits plummet by 95% and has had to set aside £1.43 billion to account for potential loan defaults. It has also scrapped its dividend. HSBC, which generates the majority of its revenues in Asia, has also seen its profits drop by 48% in its latest quarterly results. It has decided to set aside £2.4 billion in anticipation of greater loan and credit card defaults and has suspended share buy-backs for the next 2 years.
Net interest margins will also be under pressure for the foreseeable future, with interest rates expected to remain low for years to come. This combined with lower fee income generation as a result of reduced economic activity will further impact upon Bank profitability.
The General Financials industry has performed comparatively better thank the sector average due to the weighting of investment banks and investment service providers. There tends to be an inverse relationship between heightened periods of volatility and the performance of investment service providers.
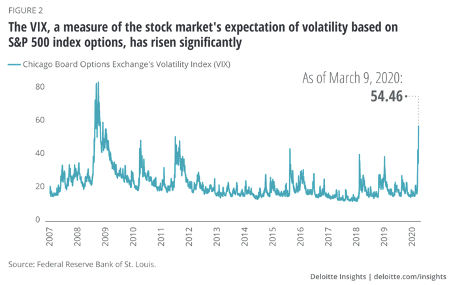
Online trading platforms such as CMC Markets, Plus500 and IG Group have achieved remarkable results since the turn of the year. Their share prices are all up over the past 6 months, with CMC having seen its share price more than double over the period. These spread betting and CFD providers have seen their revenues surge as a result of extremely high trading volumes. With volatility likely to persist, these companies could be on track for more impressive results over the coming months.
Nonlife Insurance companies have also withstood the impacts of the pandemic rather well, with the sector benchmark falling by less than the sector average at -17.15%. The industry benchmark includes the likes of Admiral, Direct Line and RSA Insurance. These companies have been able to benefit from a fall in insurance pay-outs on car, travel and commercial insurance. Indeed, with many people confined to their homes, there has been little risk for insurers.
However, nonlife insurance uptake is now slowing as a result. Car insurers have been particularly affected. According to analysis by GlobalData, new car registrations were 40% lower in March 2020 when compared to the previous year. This equates to roughly £98 million worth of premiums that have been missed.
On the other hand, nonlife insurers specialising in the provision of commercial loans to businesses may fare better. Most small to medium-sized business don’t have ‘pandemic insurance’ included in their commercial insurance plans, therefore the potential losses from these claims will be relatively minor.
The Life Insurance industry sector benchmark has witnessed a -21.64% decline, making it the second worst performer in the Financial sector. As more people become infected with Covid-19 and sadly pass away, life insurance companies will have to pay out greater sums on health & life insurance plans. Faced with a prolonged period of uncertainty over pay-out costs, life insurers have fallen out of favour. Two of the largest life insurers in the UK, Aviva and Legal & General, have seen their shares fall by -28.11% and -27.33% respectively since January.
With the stock markets across the globe currently in bull market territory after having rebounded strongly from the March lows, it is no surprise that the Equity Investment Instruments industry has been the best performer in the Financials sector.
The constituents of the industry group are mainly closed-end investment funds, or more commonly referred to as investment trusts in the UK. Investment trusts with exposure to US tech, emerging markets and biotechnology firms have performed exceptionally well over recent months, whilst those focusing on small-cap stocks have underperformed the market.
Valuation of the Industry Groups
| Industry Group | |||||
| Median Ratio (Forecast) | Banks | General Financials | Life Insurance | Nonlife Insurance | Equity Investment Instruments |
| P/E Ratio | 11.02 | 13.5 | 8.79 | 16.29 | 11.37 |
| EPS Growth | -2.34 | 5.05 | -1.85 | 12.67 | -14.27 |
| Dividend Yield | 4.12 | 4.56 | 7.47 | 6.46 | 4.59 |
At first glance, the Life Insurance industry group looks to offer the best value to investors. A median forecast P/E of 8.79 is appealing, and well below the sector average. However, investors will be faced with earnings contractions for the next year. Furthermore, dividends are under threat, with Life Insurance companies already announcing dividend cuts or dividend suspensions altogether, so a 7.47% median forward dividend yield should be taken with a pinch of salt.
The Banking industry is in a similar position. Although its forward P/E of 11.02 indicates good value, earnings are rapidly falling and dividends & share-buy backs are being cut and/or suspended.
The only industries where earnings are expected to grow are in the Nonlife Insurance and General Financials industry, where median EPS growth is expected to come in at 12.67% and 5.05% respectively. However, as could be expected, investors will have to pay a slightly higher premium for this. The median P/E in the Nonlife Insurance sector is an industry high 16.29.
For income seekers, the Financials sector typically offers a reliable, shareholder friendly capital returns policies. The sector median forward dividend yield stands at an impressive 4.42%, but even the biggest banks and financial institutions aren’t immune to the effects of the pandemic and generous capital returns policies are being slashed across the board. This may continue for the foreseeable future, as firms can’t justify paying out hefty dividends to its shareholders whilst cutting costs and making staff redundancies.
Financials: The Top-Ranking Stocks
In this next section, I will take a look at the top 3 ranking stocks from the Financials FTSE All Share sector benchmark.
CMC Markets (LON:CMCX) – General Financials
Share Price: 329p
Market cap: £954.09m
StockRank: 98
CMC Markets has been on a stellar run over the past 6 months, rising by over 110%. The company has been a great beneficiary of the volatility in financial markets, with traders making the most of these uncertain times.
In the company’s most recent quarterly trading update, it revealed that its 2021 earnings would exceed the upper end of market consensus as a result of strong client trading activity. In fact, it has seen such high trading volumes that ‘net operating income for Q1 2021 (financial year) is in excess of that reported for H1 2020 of £102.3 million’.
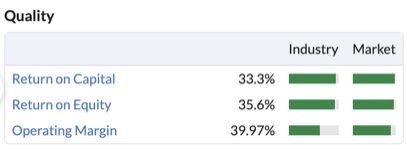
The higher levels of trading activity and client retention has enabled the company to transform its operating model and generate some astonishing returns. The company’s Quality Rank currently stands at 96 and it possesses some very impressive quality metrics. Returns on capital and returns on equity are both currently above 30% and operating margins are close to 40%.
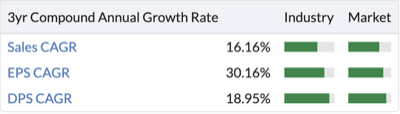
Equally formidable are the company’s growth metrics. On a 3-year Compound Annual Growth Rate basis, sales have grown by 16.16%, earnings per share by 30.16% and dividends per share by 18.95%. These levels of growth are hard to come by in the best of times and with volatility likely to persist over the coming months, the company could well just continue growing at this rate.
Plus500 (LON:PLUS) – General Financials
Share Price: 1,258p
Market cap: £1.35bn
StockRank: 95
Plus500 has had its fair share of controversy over the years. The company reported accounting errors in 2019, which caused the share price to plummet. However, the company has since seen its share price resurge after reporting spectacular half-year results.
First half-year revenues almost quadrupled to $564.2 million and 198,176 new customers were on-boarded in H1 compared to just 47,540 in the prior year. The company seems very optimistic about its future and commented the following in their trading update: ‘The Company's financial position remains robust, driven by the strong EBITDA margin achieved during the period and continued high cash generation, as well as the minimal capital expenditure requirements and the low capital intensity of the business.’
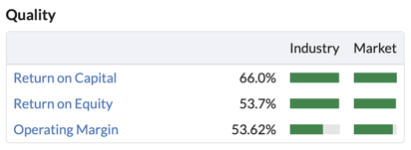
Once again, the quality metrics of this leveraged products provider are remarkable. The company boasts industry-leading returns on capital and returns on equity at 66% and 53.7% respectively. Operating margins are also above 50%. When combined with the strong price momentum, Plus500 has all the characteristics of a high-flyer.
IG Group (LON:IGG) – General Financials
Share Price: 820p
Market cap: £3.07bn
StockRank: 94
One of the more established names in the provision of investment services, IG Group, has also been on a winning streak in recent months. Since the start of the year, the shares have significantly outperformed the market, rising by 23.76% whilst the General Financials industry benchmark fell by -14.45%.
The company’s most recent trading update in June confirmed that trading revenue would be above previously expected levels. Net trading revenue for Q4 FY20 is now estimated to be approximately £259 million, significantly more than Q4 FY19 revenues of £117.9 million. Overall, full-year net trading revenue is expected to come in at £649 million, well above the £476.9 million reported for FY19. Furthermore, the Group has reported that it continues ‘to see high levels of client trading activity.’
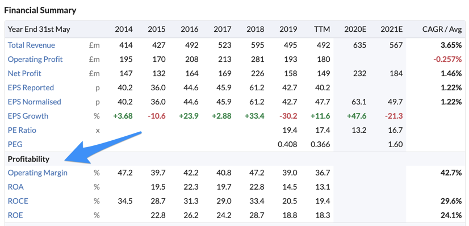
IG Group’s profitability metrics are a testament to the quality of the company, as can be seen by the financial summary below. In addition to this, the company maintains an excellent balance sheet with a strong net cash position and exemplary liquidity ratios.
Conclusion
Whilst indices around the world are surging to new heights, the UK benchmarks are seemingly lagging behind. A large part of this has been down to the weight and poor performance of the Financial sector on major UK indices.
Banks seem to be facing a challenging road ahead. A sustained period of ultra-low interest rates, a reduction in fee income generating activity, and heightened risks of loan defaults all point towards bleak outlook. Though current share prices do seem to reflect this, there could be further downward pressure in the not too distant future. It remains to be seen how the economy will adapt once the furlough schemes are ended, but an increasing number of loan defaults from both private and commercial clients is inevitable.
General Financials, more specifically, investment service providers such as brokers, seem to be in a much better position. These companies perform exceptionally well in periods of prolonged volatility and these are the conditions in which we find ourselves today. The low-cost operating models and sophisticated financial technology that are implemented on these platforms have given these companies an edge in the current climate and are well positioned to continue achieving market outperformance over the medium-term.
Both Nonlife and Life Insurers face uncertain futures. Insurance models may need to be completely revised to accommodate for these unprecedented times. Whilst Nonlife Insurers may benefit in the short-term from lower pay-outs, long-term demand for insurance premiums may fall due to lifestyle changes. For example, with more and more people working from home or avoiding public transport, there may be a permanent reduction in car insurance demand moving forward. For Life Insurers, much will depend on the level of state intervention in tackling the pandemic.
Equity Investment Instruments may be a good option for passive investors. Equities tend to outperform almost all other asset classes over the long-run and investment trusts are a good way to get exposure to a diversified range of stocks. It is worth carrying out some due diligence to see in which area the investment trust specialises though so as to avoid exposure to higher risk or underperforming equities.
Overall, whilst the Financial sector hasn’t crashed in the same way as the 2008-2009 financial crisis, it remains in unchartered territory and could quite easily capitulate once more, should unemployment and bankruptcies accelerate at pace.
Stay safe and safe investing!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
11 comments
I have a few problems with this analysis, as I feel it misses the potential that the market offers here in those large caps that have been forced out of Income portfolios. The great performance in markets pre-Covid was driven by flight to income and US tech. As companies temporarily stopped dividends, many Income funds have had to drop companies to maintain income mandates. This has been hugely damaging for the Financials, particularly Life and Banks. The underlying market relative valuations of these companies has become very attractive, so any return to dividend distribution should be significantly rewarded (indeed L&G has been punished even though it maintained its dividend).
The comment "As more people become infected with Covid-19 and sadly pass away, life insurance companies will have to pay out greater sums on health & life insurance plans" is correct in sentiment, but likely to be relatively immaterial in practice, especially as total deaths now approach normality.
Banks' lending has been much more disciplined since the GFC, and they are benefitting from loan growth under government backed schemes. Whilst the low interest environment is likely to be with us for a while, and we may see more bad loan provisioning, PPI provisioning should abate and further bashing from the regulators should hopefully cease as these institutions are important machinery for Covid recovery.
Whilst these sub-sectors may not be particularly sexy, I believe they offer significant value and then income potential for the long-term investor.
I kind of feel like the reason for these online trading platform companies growth is due to the fact people are being sold an hype for CFD & Forex trading. I think these companies are bit overvalued and hyped for the stock price and may potentially fall down soon to a reasonable value for purchase.
Interesting and helpful overview of this sector, thanks.
Interesting - I wonder what it says about the world that the stockranks think the CFD companies are the most attractive investments in the financial sector?
IE not traditional banks or insurance companies- my takeaway is that is rather a negative assessment for UK plc.
Hi brucepackard,
Thank you for your comment.
It is interesting to see how historically strong, sturdy and largely predictable industries have had their fundamentals completely changed as a result of the pandemic.
I feel that there may be more hard times ahead before things start to get better or return to something that resembles normality. The key is identifying industries that are set to perform well regardless of these challenging times.
Best, Keelan
excellent article and research. Thank you.
Hi Ipreidster,
Thank you for your feedback. Carrying out the research and amalgamating all the data has been thoroughly fascinating so far. Lots more to come!
Best, Keelan
Really usefully I love it. Thump up from me
BSV
Hi BSV,
I'm glad you enjoyed the article! Still a fair few sectors that I will be covering in the coming weeks.
Best, Keelan
Another thought provoking report. Excellent Keelan.
Hi bbeatty,
Thank you for your kinds words. Industrials coming up next week!
Best, Keelan