CSR: Defying rising interest rates

CSR (ASX:CSR) is one of the oldest companies on the ASX having been founded in 1855. Over that time it has grown to about $2.5 billion in revenue and the same in market capitalisation.
CSR is a fairly cyclical business with demand for its products tied to the building cycle. Sales peaked at $2.5 billion in 2017 and then gradually declined to $2.1 billion in 2021 before rebounding in 2022. Sales reached a new high of $2.6 billion in the recently released results for the full year to 31 March 2023.
The share price has rallied strongly this financial year from a low of $3.93 in June last year to the current level of $5.37 a rise of 37%. This is despite headlines of a slowdown in housing construction on account of builders going bankrupt.
The current expectation amongst market analysts is that sales growth has peaked with small declines in revenue forecast for the next two years. This contrasts with a very strong result in FY23 and comments from the CEO Ms Coates that the pipeline is strong and the momentum for orders still solid.
Part of the explanation for the growth over the last two years was the additional support provided by government schemes introduced to alleviate the pandemic. The government’s HomeBuilder incentive scheme fuelled demand for building supplies. Despite the cut off for applications being in April 2021, construction was able to be commenced up to 18 months later. There were approximately 121,000 applications submitted. A lot of CSR’s building products are used in the later stages of the construction process, which further extended the duration of demand for CSR products.
In last October’s Federal Budget, the Government set a goal of developing one million new homes in Australia over 5 years from 2024 with financial incentives provided to help achieve that goal. With governments, both Federal and State focused on boosting housing, the underlying demand for quality CSR products should remain robust should the building industry increase capacity.
CSR’s diversified product mix also works in its favour. Their biggest segment is building products and includes Gyprock plasterboard, PGH bricks and pavers, Monier roofing, Hiebel lightweight building blocks and Bradford insulation. 78% of CSR’s earnings before interest and tax came from the building products business, 20% came from their property business and 2% from the aluminium business. This year was a record high for EBIT at $273 million.
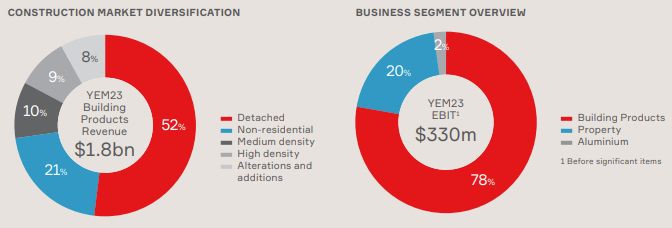
This was largely driven by the Building Products segment with revenue up 14% on the back of strong product availability and prices and costs being well managed for inflation. CSR’s lightweight Hiebel products continue to gain market share as they have quicker build times and a large base of installers. The outlook appears positive with activity in apartments improving and non-residential activity strong. Detached housing projects under construction are also at historically high levels. There is a large backlog of new homes due to a shortage in construction labour with a pipeline of 110,000 detached houses outstanding, 50% higher than average levels.
These factors are helping to offset any softness caused by rising interest rates. Demand for housing is strong with prices no longer falling and starting to rise again in many markets.
The outlook for the property segment is strong, supported by strong demand for housing on account of expected rising migration levels and current housing shortages experienced across most of the nation, particularly on the East Coast. CSR also retains a large land holding in western Sydney including the 200ha site at Badgeries Creek adjacent to the Western Sydney airport which is zoned for industrial use.
One negative for the business from the recent annual result was EBIT for aluminium fell 80% in FY23 to $8 million, largely due to volatility of costs including higher raw material and production costs. This compares with $60 million three years ago. In their outlook statement, management stated that their best estimate for this segment was a loss of $5 to $15 million in FY24.
This impact contributes to the expectation that earnings per share will decline by 8.5% in financial year 2024, driven by a 2.5% forecast decline in revenue. Clearly the aluminium segment is the biggest drag, but management remain confident that it will turn around the following year based on their pricing hedge book and cost assumptions.
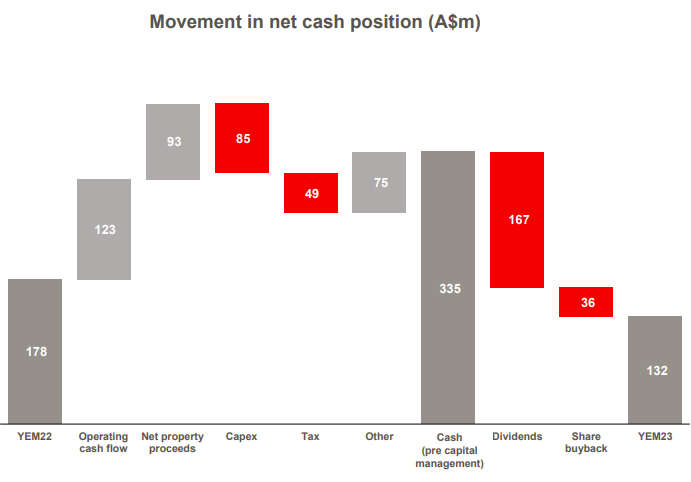
Earnings are translating into strong operating cash flow and the balance sheet is solid with a net debt to equity ratio of only 2.7%. The solid performance of the business has led to a Quality score of 95. This cash strength has enabled the company to be generous with its distributions to shareholders with a high dividend payout ratio and a share buy-back. The historical dividend yield is 6.8% fully franked.
The return on equity and return on capital employed is above 20% which is very strong. This is backed up by double digit operating margins and an F-score of 6 out of 9.
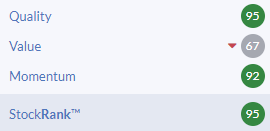
The lowest component in the rankings is the Value score, currently at 67. It is dragged down by a low level of free cash flow in the most recent year, along with moderately high price to equity and tangible equity ratios. The earnings multiples are quite good with 12 month forecast rolling PE ratio of 13.8 and EV/EBITDA of 6.85. The cash flow was impacted by a build up in working capital as well as capital expenditure.
Overall, CSR looks like a solid business. It is a conservative, mid cap stock with a fairly cyclical revenue pattern. Investors should not anticipate eye watering returns, but rather a steady income stream and appreciation of capital over the long term. In the short term there may be some headwinds on demand for their products from the impact of rising interest rates, cost inflation and pressures on builders. However that may be countered by the acute shortage of housing, driving demand for construction and therefore building materials.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?