Dart Group has nearly halved - but is it just too soon for airline stocks?

It was only a couple of weeks ago that we looked at Warren Buffett’s 2019 letter to shareholders - a lot has happened between then and now.
In that piece, point two (“Acquisition discipline is key”) remains particularly relevant. Certain high profile Berkshire shareholders have expressed disappointment at the company’s lack of significant acquisitions over the past four years, but that c$130bn cash pile must look a lot more enticing now.
In recent years, Berkshire has been frustrated in its aim to buy good companies at attractive valuations. Given recent dramatic price moves, however, it is worth noting that Berkshire’s response has been to spend around $45m on Delta Air Lines shares. In upping its stake in Delta, Berkshire is living up to that famous mantra: “Be Fearful When Others Are Greedy and Greedy When Others Are Fearful”.
But is this actually the time to be buying airlines? It looks like there is more short term disruption to come. If any contrarians out there are tempted, I would encourage caution and a keen focus on financial health.
Stock market Darwinism: how bad markets can help good operators
Let’s just get this out of the way: airline stocks are particularly risky investments. Low barriers to entry, brutal competition, high fixed cost bases and a weak negotiating position with suppliers are just some of the dangers. That said, you do get big winners as well.
Airline stocks have been clobbered in recent weeks. People are flying less. It is highly likely that most operators will report reduced business for at least a quarter or two. And while those sales might have evaporated, operating costs will be much stickier. This week’s crashing oil price could provide some welcome relief, but not immediately - most airlines work hard to hedge out oil price exposure.
It doesn’t take a genius to see that a market shakeout and possible sector consolidation is on the cards.
Shakeouts never feel good, but in the long term they are a net positive for quality operators. It’s a harsh, Darwinian truth. Good businesses with strong balance sheets can take advantage of market weakness while the competition suffers. This might be done through buying back stock, acquiring competitors at knockdown rates, or just investing for future growth at a time when others are fighting twice as hard to keep the lights on.
It is in such moments that good businesses can increase the odds of future success. While share prices might decline across the board, intrinsic values can be enhanced.
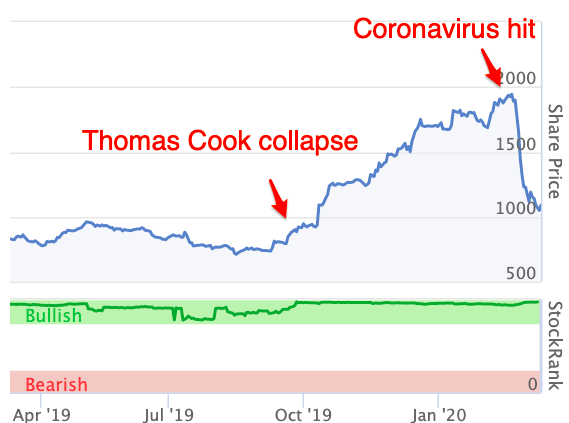
I think we were beginning to see something like this reflected in the rising share price of Dart (LON:DTG) following Thomas Cook’s collapse. Recent fears have reset a lot of that progress, however.
Focusing on financial safety
Net cash position
In such markets, when investors are laser-focused on downside risks and an underlying current of panic hangs in the air, possibly the most important rule is to stick to strong balance sheets. Indebted companies can usually roll over their debts. Every now and then, however, they must refinance in exceptional market conditions that prove disastrous for equity holders…
The risks are multiplied when you find a low-margin company with high fixed costs and debt on its balance sheet. This combination of financial characteristics can be fatal. Comparing Dart to some other airlines (including Berkshire’s Delta) shows that Dart is the only airline to currently have a net cash position.
Net Cash | Market cap | |
Dart (£m) | 455 | 1,620 |
Ryanair (€m) | -745 | 10,640 |
easyJet (£m) | -326 | 3,970 |
IAG (€m) | -7,612 | 8,570 |
Wizz Air (€m) | -385 | 2,950 |
Delta ($m) | -8,278 | 22,510 |
Tui (€m) | -5,087 | 3,130 |
Cash generation and liquidity
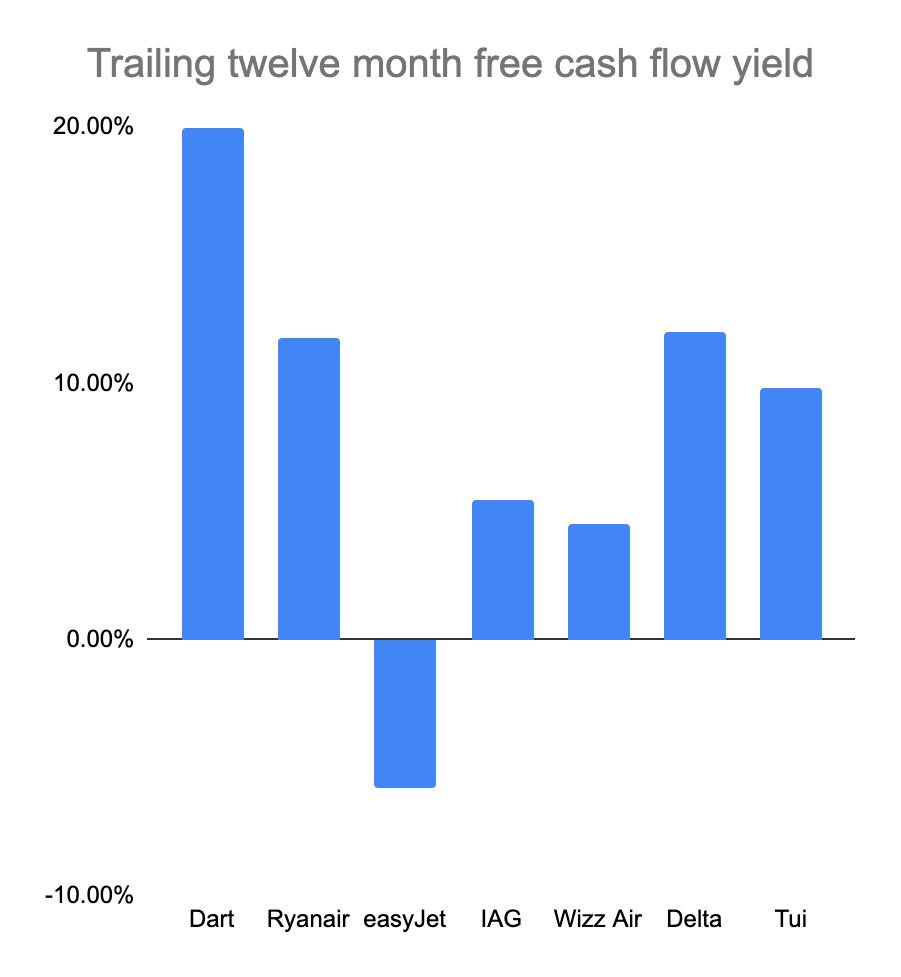
Dart Group stacks up well on a free cash flow basis:
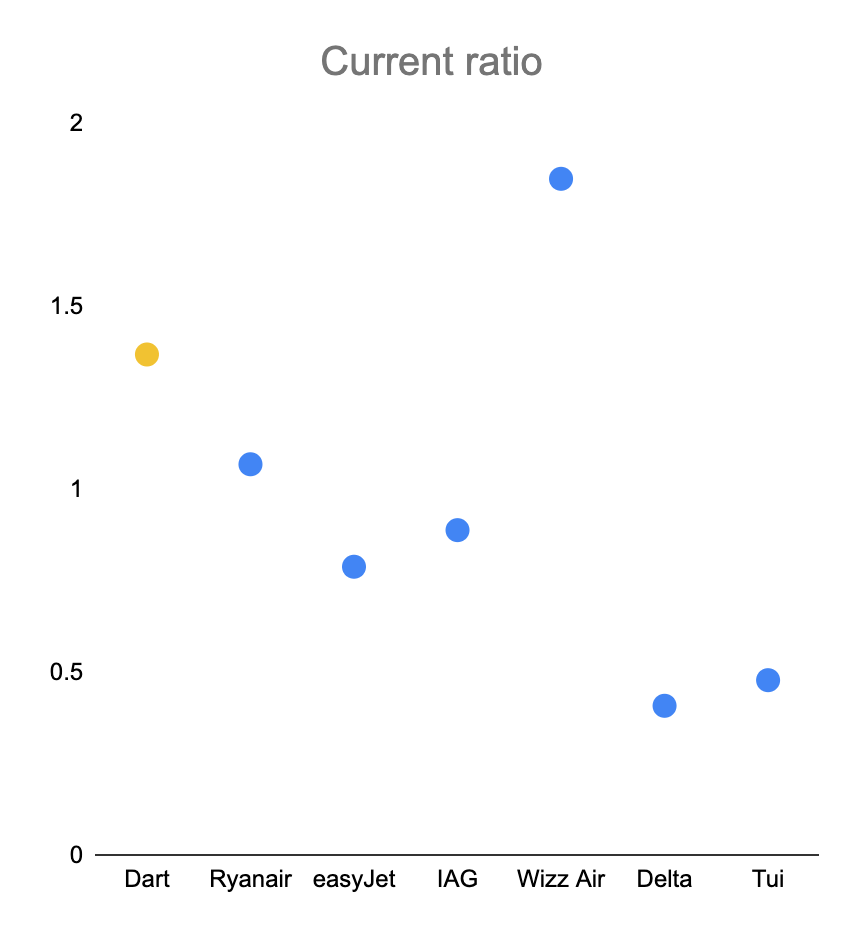
Meanwhile, its liquidity measures are strong versus this peer group:
Relative valuation
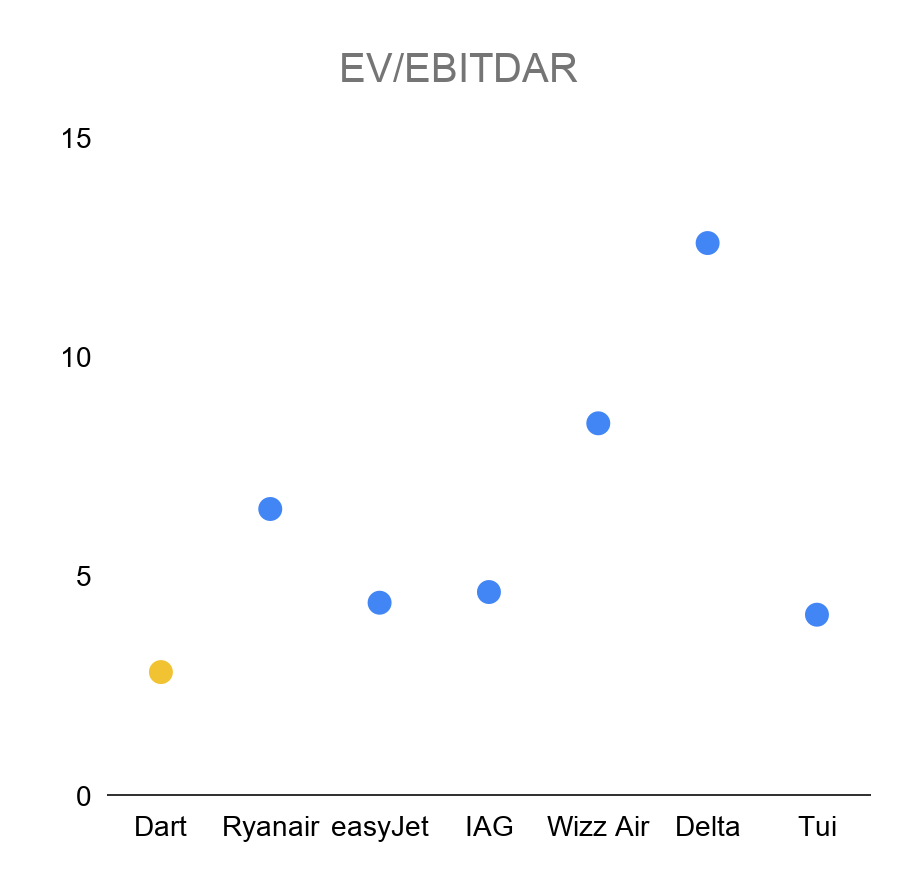
As well as having a net cash position and superior cash generation and liquidity measures, Dart Group is also attractively valued on an EV/EBITDAR basis.
Conclusion - too soon to bet on airlines?
First Coronavirus, then a breakdown in OPEC+ relations… Exogenous shocks to the global economy operate, apparently, like London buses: you wait for a decade and then two come along at once.
Investors will be far more focused on margins of safety and balance sheet health in the months ahead, and rightly so.
With cyclical, operationally geared stocks such as airline companies, leverage that looked manageable can quickly become unsustainable. Flight disruption is more likely to deteriorate than improve over the next few months, in my view. Demand for air travel to and from Europe has already fallen rapidly.
The International Air Transport Association (IATA) has updated its financial analysis of Coronavirus on the global air transport industry, revising estimates of 2020 global revenue losses for passenger business of between $63bn and $113bn, up from $29.3bn.
Given such headwinds, having a cash pile to soak up operating expenses could make all the difference.
Dart Group appears to be financially safe and modestly valued compared to peers. A stronger balance sheet will be vital in the months ahead. The best will be able to take advantage of market conditions. The weak will suffer.
Dart Group looks reasonably well positioned to pick up the pieces in the UK and Europe. However H1 growth was unspectacular and costs have been increasing in tandem with its expansion push. Given prevailing conditions, perhaps those lukewarm H1 figures should be viewed in a more critical light.
Back in November, I wrote that Dart Group “has a significant opportunity to gain market share” but added that “this is one investment that should be monitored closely for developing risks”. Evidently, risks have developed and must now be considered.
I don’t see any great need to rush back into airline stocks right now. The chances are we will get a wave of tough airline trading updates and revised broker EPS estimates over the next couple of months.
I’ll be watching Dart Group from the sidelines to see how it fares in this tricky time. If it wins out as an eventual survivor and consolidator, it could guarantee growth for years to come. It’s worth noting that, while Coronavirus disruption is bad news for airlines, a sharply lower oil price (if sustained) should be a very good thing.
On another note, I think hotels and restaurants are another danger area in terms of fixed operating costs and variable demand. Some will be seeing pretty painful year-on-year like-for-like trading figures right now - I think minus double digit LfLs at least, particularly for those with exposure to travel hubs.
Michael recently flagged Restaurant Group as a stock to avoid and I would second that. Cheap stocks can always get cheaper.
It’s easy to find the risky parts of the market right now. Given the recent, extreme market moves, I’d be interested to know where others do see opportunities.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

20 comments
Dart has collapsed in price since the date of this article (10th March) by about 75-80%. Some were suggesting here and elsewhere In earlier posts that it was worth buying! Crazy with Coronavirus rampaging through Europe and now London. A classic falling knife if ever I saw one. I'll stick with my savings account for now thanks.
I see Dart (LON:DTG) were down to 185p this morning, now back up to around 303p. Another share if you can time it right you can quick profits.
what now for DART if the airlines survive surely DTG will benefit most
The drop on dart is so huge now, if it ever recovers to its previous high you would almost have a 10 bagger. They seem to have enough cash to see them through around 6 months with minimal revenue, thats without any government help which I assume will be forthcoming. This is (was) a high quality company as far as Airlines go and was growing nicely until the coronavirus struck so I am really tempted to pick up a few. However, I'm being held back by the fact that the share price has fallen so dramatically and a lot more that some other Airlines. For example, Dart is currently down around 50% this morning, whilst Ryanair was up this when I last checked. It makes me think I am missing something so would really appreciate if anyone could shed some light. At the moment it feels a bit binary. Either it survives and prospers long term or goes bust or needs a massively diluting fund raise if it cant see out the turmoil.
Same here - am reminding myself of Peter Lynch's quote continually at the moment
"No matter how much a stock has fallen, it can always fall another 100%"
The indices for long term holders are a much better bet at these levels with a drip feed in over time.
Individual stocks in hammered sectors are way too risky.
Hi Harvs19
You mirrored my thoughts. Very tempted to buy a few now, but the absence of any clarity regarding time scale makes me hold off, as the price is likely to come down further. According to my latest ferreting it should have around £700m available, excluding money held for customers. Also Fowler Welch, the logistics business will be busy and make some profit contribution.
Currently it is a finger in the wind job! It could disappear but I don't think it will and hope that I am right. It is a well managed company caught in a disaster not of its making. Equally important there are its employees for whom the future is desperately uncertain.
Completely agree. I am tempted to take a tiny slither now (punt money) and then wait for some further clarity. If the government provide some liquidity in the form of long term low/no interest loans they should recover but am concerned of what strings the government may attach to any aid. It seems there are lots of conversations going on between the airline industry and the government so hopefully we will have some clarity soon for investors and of course the employees who must be going through a very stressful time.
Great company and thanks for the article. Dart is definitely on the watchlist, but I wouldn't be surprised to see it 15-30% lower first. Let's see.
Agreed with your comments hp01
Would just add - a sound balance sheet and a decent moat with the brand?
wow, that 30% drop happened faster than expected!
Not really considering a lot their routes have been cancelled. With other countries closing their doors or going into lockdowns this not surprising, now they are talking about lockdowns in the UK, so no one will be flying anywhere for a holiday soon.
Well Jet2 has just puled out of all Spain and Balearics - not looking good for Dart
https://www.manchestereveningnews.co.uk/news/greater-manchester-news/jet2-flights-spain-turned-round-17924343
Thanks Jack, this is all very helpful and clearly show what a quality company Dart is!
Dart was one of my biggest holdings and I was lucky enough to escape just before the virus when I sold out at 1900p. Definitely keen to get back in and I think there are many investors who have their eyes on Dart at the moment. It's still too early as there are too many risks. There could be a lot of further disruption, but once the dust has settled it will go back up.
Thanks Jack, it's interesting to see how well Dart (LON:DTG) scores relative to other UK airlines.
Impressively, Dart has announced this morning that results for the year ending 31 March will be "significantly ahead of current market expectations". Although the company does say it expects to give back some of these profits over the coming year.
https://www.stockopedia.com/sh...
I do think Dart is a class act. Perhaps this is another example of the benefits of owner-management - executive chairman Philip Meeson owns 36%.
Cheers,
Roland
Good comment Roland
Haven’t £DART also said they are up on their 2020 (snatch T Cooks) trade expansion plans but expect to drop back to last years levels, I’m simplifying here
Hey Roland!
Thanks for linking... On first reading, the update sounds about as good as it can be given the circumstances. It will be interesting to see future updates from competitors.
I agree Dart (LON:DTG) is a class act in a tough sector and I'll continue to keep an eye on its progress.
Thanks Jack, very interesting. With Dart having a holiday business in Jet2 Holidays, to what extent is the net cash actually customer prepayments for holidays which may not now be taken? The same would apply to Tui at least but it's balance sheet is much weaker. Cheers
With airlines also one should ask which airlines would govt's bail out if demand stays low ?
Where I see opportunity:
Started with excluding travel and leisure for a while until the panic/rational response is over.
While falls are occuring downside protection is paramount. So that would suggest strong balance sheets, high sustainable yields and lowish price to earnings. It suggests to me a PYAD like hunting ground. People familiar with this strategy from TMF days will know that in addition to the financial screen Stephen Bland also looked for an outer, potentially negative press, positive management speak (I think). He also avoided/avoids involvement in less developed countries and had unusual views on position sizing. He would suggest holding until the share normalised, leaving something for the next guy. Given the initial 'discounts' this would generally be 30-50%. I'm sure he'll correct me if he sees this and I'm wrong. The screen is completely mis-classified under income.
An alternative strategy is quality at a reasonable price (QARP). What is important here is a good business engine that can recover quickly, combined with not overpaying. The less debt the better. Net cash is preferable. I'd start with a screen like this and tweak it. If quality really is sustainable then time will out. Ensuring you get a good price increases your odds so make sure that you buy at a discount. Overlaid on this I'd look for positive relative strength since about mid-February.
I think we are likely to see highly geared companies challenged by Coronavirus. Cash-flow will be king. Banks will probably be encouraged to shake the magic money tree in order to support stretched balance sheets. Eventually consolidations may start to occur. Acquisition of 'safe value' by 'strong quality' may be the net result. Once the recovery is underway the banks will of course have more companies in thrall and they'll benefit.
Yes, in a nutshell. Let's try to avoid falling knives, shall we?