Dart Group's package holiday potential

Dart Group runs the UK’s third largest ATOL licensed package holiday tour operator Jet2holidays. The group believes that Jet2holidays has “tremendous potential” with customers up a fifth in the year to March 2015. A profits upgrade and a large new aircraft order both highlight the business momentum.
It has been a strong summer for the airline and travel industry with easyJet and Ryanair both seeing record trading in August. A period of wet weather and the weak euro have both made a break in the sun more attractive.
Dart Group has also seen an uplift with strong package holiday and flight-only sales. The group is therefore: “optimistic that… performance for the financial year ending 31st March 2016 will materially exceed current market expectations.”
Dart Group runs Jet2.com and Jet2holidays

Source: Dart Group Annual Report
The company has also announced a US$2.6bn list price aircraft order for 27 new Boeing 737-800NG aircraft. The actual cost is at a “significant” discount to this figure but cannot be revealed for commercial reasons.
Airline and holiday businesses are volatile given changing consumer demand and low profit margins. However, the strengthening UK consumer environment and weak oil prices both support profit margin expansion.
While the share price of Dart Group has continued to strengthen the forward P/E ratio is modest at 13X. The group’s first half trading update will be in mid-October with interim financial results set to be announced in November.

Leisure Travel: Jet2.com & Jet2holidays support each other
Dart Group’s Leisure Travel division runs the ATOL licensed Jet2holidays business and the budget airline Jet2.com. The airline travels to high volume European city break destinations, summer holiday spots and winter ski areas.
Dart Group offers the North of the UK “fun in the sun”

Source: Dart Group Annual Report
The two businesses work well together with Jet2holiday customers travelling on Jet2.com flights. In the year to March 2015 package holiday customers made up 33% of Jet2.com seats sold versus 30% the year before.
The September trading update has seen this figure increase further due growth in the package holiday business. This helps to underpin demand for Jet2.com seats and helps offset price competition from Ryanair and easyJet.
The symbiotic relationship also works the other way around with the consumer presence of Jet2.com increasing the profile of Jet2holidays. Only 31% of Jet2holidays were sold through the high street or online travel agents last year.
Online sales made up 52% of the total with the remaining 17% conducted through a call centre. Direct sales, without a costly high street presence, allow Jet2holidays to offer stiff competition to the likes of Thomas Cook.
Dart Group is very optimistic on the package holiday business stating that: “Whilst our flight-only product remains very important, we believe our growing package holiday business has tremendous future potential.”
Leisure Travel growth: driven by package holidays
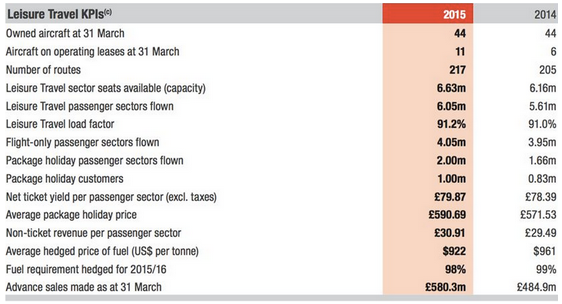
In the year to June 2015 the group ran 6.05m customer flights with 4.05m of these flight-only sales and 2m package holiday flights. Each package holiday customer has two flights and so the group carried 1m holiday customers.
This was an impressive 20% increase on the 0.83m package holiday customers seen the year before. The number of flight-only passengers increased by only 3% in the year to March 2015.
Dart Group’s Leisure Travel business: Year to March
Source: Dart Group website
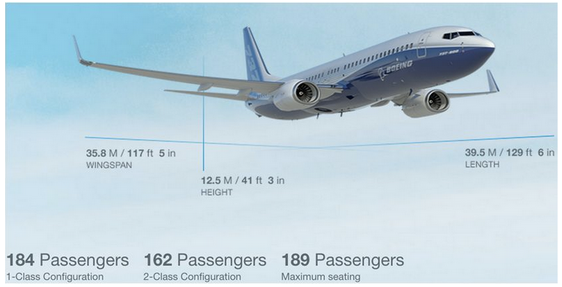
Aircraft purchase: 27 next generation jets
Dart Group’s purchase of 27 new Boeing 737-800NG aircraft is expected to be funded from internal resources and debt. At March 2015 the group had only marginal debt and owned 44 of the 55 planes it deploys.
The company has purchased second-hand planes second hand plans in the past, which are older and so less efficient. Dart Group should therefore be a significant beneficiary of the current low oil price environment.
Newer and more efficient planes will help offset the risk of a return to high fuel prices and will be more reliable. However, the debt taken on to fund the purchase will increase Dart Group’s balance sheet risk profile.
Boeing 737-800 Next Generation (NG)
Source: Boeing website
The planes will be delivered between September 2016 and April 2018 and highlight, in our view, the long-term focus of the company. The group also opened a training facility for pilots and airline staff in May 2014.
Activist interest
Dart Group’ Leisure Travel business – Jet2.com and Jet2holidays – generated over £100m of EBITDA last year. The group also runs a distribution business, called Fowler Welch, which generated only £6m EBITDA.
Fowler Welch therefore looks out of place and an activist investor, Crystal Amber, has stated as much. Whether Crystal Amber can instigate change remains to be seen given that it only owns 1.2% of Dart Group.
By contrast the executive chairman of Dart Group, Phillip Meeson, owns 38% of the business. In any event Crystal Amber is positive on the fundamental investment case stating in its annual report, when the shares were 490p, that:
“In our view, Dart’s earnings momentum remains under-appreciated by the market. Given the low risk nature of the balance sheet, the growth delivered by Dart deserves a premium to its current 13 times rating.”
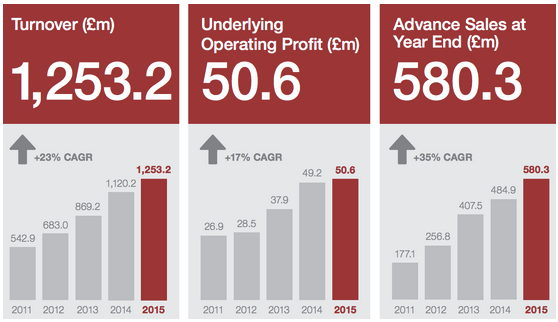
Dart Group 5-year financial performance
Source: Dart Group annual report
Summary and valuation
Airlines and holiday companies are volatile businesses due to unpredictable consumer demand and variable profit margins. Dart Group’s operating margin was only 4% in the year to March 2015, which doesn’t leave much room for error.
However, the key drivers are currently positive with lower fuel prices and increasing demand. Even in a tough consumer environment the package holiday product should hold up well given the value for money it offers.
The current financial year to March 2016 is set to see further revenue and profits growth. A conservative hedging programme meant that fuel prices fell by only 4% last year and so there is considerable scope for fuel costs to fall.
Underlying basic earnings per share in the year to March 2015 rose by 29% to 31.72p. This puts the shares on an historic P/E rating of 15.4X and the market P/E forecast for the year ahead is around 13X.
In our view, the investment case continues to stack up given the undemanding valuation. Growing package holiday sales serves to improve customer loyalty and enables Dart Group to stand out from the other budget airline operators.
This report was produced by Fat Prophets Senior Research Analyst, Andrew Latto CFA
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?