Dig for Value in Caledonia Mining (CMCL)

What am I thinking, looking at:
- A Mining company (hated sector)
- A Gold mining company (loathed commodity)
- A company with operations in Zambia and Zimbabwe (talk about geopolitical risk)??
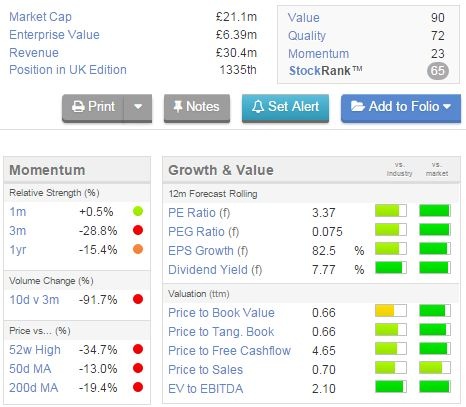
I have looked at Caledonia Mining (LON:CMCL) before, as it ranks well on Stockopedia's StockRanks with a 90 Value rank and a 72 Quality rank (Figure 1), which is very high for a mining stock.
1. Caledonia Mining: StockRanks
Well, my interest was re-ignited in Caledonia on the back of this detailed Seekingalpha article on the stock.
Obvious Value
And yes, the valuations do look rather compelling at 3.4x P/E, 2.1x EV/EBITDA and 7.8% dividend yield...
Looking at deep value, the market cap. of £21m is only £3.6m more than the stated working capital of C$31.1m (at a £/C$ FX rate of 1.78), which itself is mostly cash. Put another way, you are paying no more than 10% of the book value of the net fixed assets after subtracting this working capital...
A Low-Cost Gold Producer
It has to be pointed out that with their 49%-owned Zimbabwean Blanket mine, Caledonia is a low-cost gold producer, with a claimed 267% internal rate of return (IRR) - see the CFO's Video discussing this here.
According to the Q3 results, for 9m 2014 production of 31,354 oz of gold was sold at a price of $1,266 per oz, versus an all-in cash cost of $938/oz. While both production and the average selling price were both down in Q3 2013, resulting in a lower profit, bear in mind that the company also managed to lower the all-in cost from $972/oz over the first 9m of 2013.
Moreover, according to the company,
Blanket remains on course to achieve its target production of approximately 40,000 ounces of gold in 2014
and
On-mine costs at Blanket remain low and are better than was expected
But Quality Too
Let's start with the balance sheet and cash flows, since these are primordial for high-cost industrials like miners. The good news is that Caledonia has net cash of C$27m (with an increase of C$1.1m over Q3 2014), representing around 70% of the market cap. Very strong balance sheet then.
The dividend cover is a prospective 1.7x for this year, rising to 4x for next year. Pretty solid.
Despite the crash in gold prices, both operating margins and return on capital measures have remained positive, more than can be said for many other small gold producers.
Gold Price May Be Stabilising/Rallying
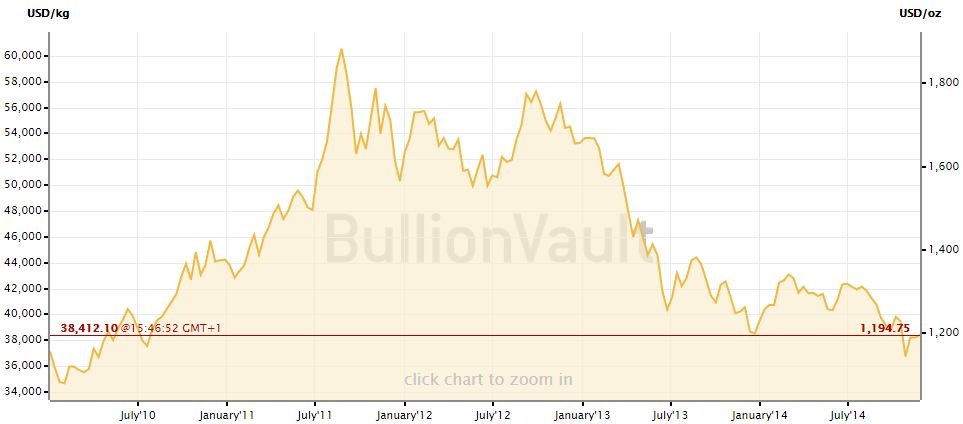
The gold price seems finally to have found some support around $1200/oz (Figure 2), despite the continued US dollar rally (often the US dollar and gold price have an inverse correlation).
2. Gold Price Stabilising around $1200/oz?
Caledonia Dropped 33% as the Gold Price Fell 2-3%
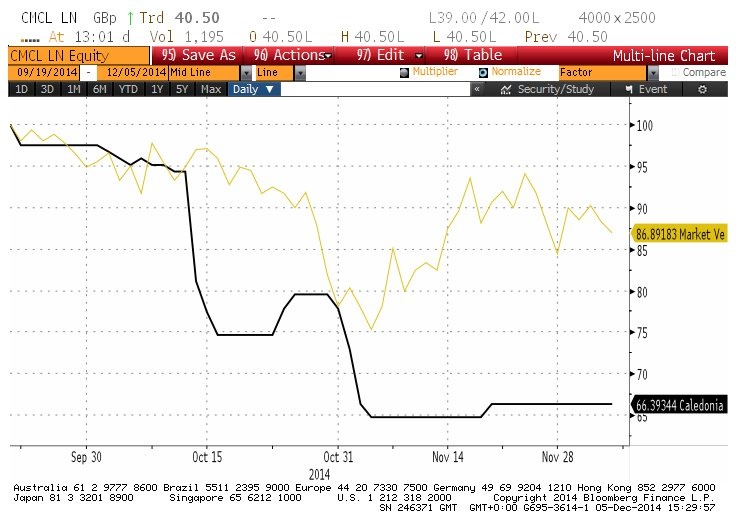
Since September 19, Caledonia's share price dropped from C$1.11 (60p) to C$0.74 (40.5p), almost a third. At the same time, the gold price in US$ fell by only 2% from $1220 to $1193/oz! So it is not about the gold price, but more about sentiment in general towards energy and resource stocks.
What is more, the US Gold Mining stock ETF (US code: GDX) fell only 13% over the period, so Caledonia is clearly a massive laggard versus other gold mining peers (Figure 3).
3. Caledonia Mining v US Gold Miners ETF
So yes, geopolitical risk for sure, and exposure to a volatile gold price too, but with such compelling value and quality metrics and what seems to be a solid operating platform, all in all, it seems worth closer inspection, particularly given its growth perspectives from expanding production at the Blanket mine...
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
3 comments
Edmund,
I keep on hearing from the gold bugs that the Chinese, Indian and Russian are buyers of gold for the last two years. I know the Indian government has put restrictions on its citizens to stopping buying gold because it depreciates the Indian Rupee. But if the chinese have been buying gold so aggressively, why hasn't the gold price gone through the roof?
Will the fall in oil price be too 'deflationary' for the gold price to rise?
A tricky question to be sure, but there are fundamental arguments for gold... For example:
http://seekingalpha.com/article/2707725-chinese-and-russian-demand-provides-reasons-to-be-bullish-on-gold
Longer-term, I think the first real bout of prolonged bond market volatility could give investors a good reason to retreat to alternative "hedging" asset classes like gold.
But I certainly wouldn't base any investment on CMCL on just this premise... Otherwise, better just to buy the Gold Miners ETF... What I find more compelling is the underlying fundamental story and value/quality metrics...
Edmund
Caledonia Mining (LON:CMCL) is a share I have invested in previously and always thought it is good value. However, I have sold out because of the gold price. Gold miners are a great opportunity provided the gold price starts to increase as the profit per ounce is very small at the moment (taking into account all in costs).
I cannot see any reason at the moment for the gold price to suddenly start increasing but would welcome a contrasting view?
Thanks
Ric