Fever-Tree: Creating an iconic brand

For many years consumers were quite happy with their G&Ts. A shot of Beefeater gin with a hefty splash of Schweppes tonic and that was enough. Then thesmall-scale premium gins emerged to shake up the market and suddenly they were in every bar. However, the tonic market lagged this evolution until 2005 when Charles Rolls and Tim Warrillow launched their natural mixer range. Now Fever-Tree is well known, in certain circles, as the brand which kicked off the premium mixer market and converted a generation of discerning gin aficionados.
Riding on the back of this trend Fever-Tree, as a stock, has exploded upwards from its cautious IPO price of 134p back in November 2014. In just 2½ years the price has multiplied by over 12x, as profits have roughly quintupled, with investors ascribing an ever-increasing earnings multiple to the business - now at an eye-watering 60x or more. That said every trading statement since flotation has revised trading expectations upwards, often materially, and so the business is living up to the hype.
With such a fast-growing business there are real question marks over the sustainability of this growth, both qualitative and quantitative, and whether such a trajectory can be maintained. My plan is to take a look at both sides of the business to see where the weak points reside and to consider whether Fever-Tree is a flash-in-the-pan or an FMCG brand icon in the making.
Analysis
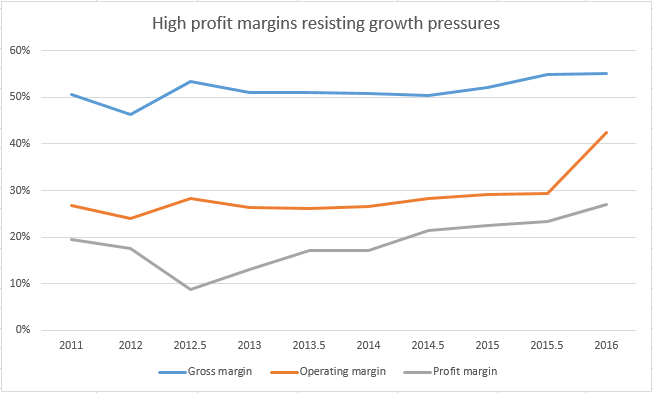
A notable feature of Fever-Tree is that it makes excellent profit margins and has managed to do so for the last five years despite sales multiplying almost 10 times. Specifically the gross margin has remained above 50% while the net margin has been improving for the last three years and is currently heading to the 30% level. I put these excellent characteristics down to the premium nature of the brand combined with excellent cost control as the business has scaled up:
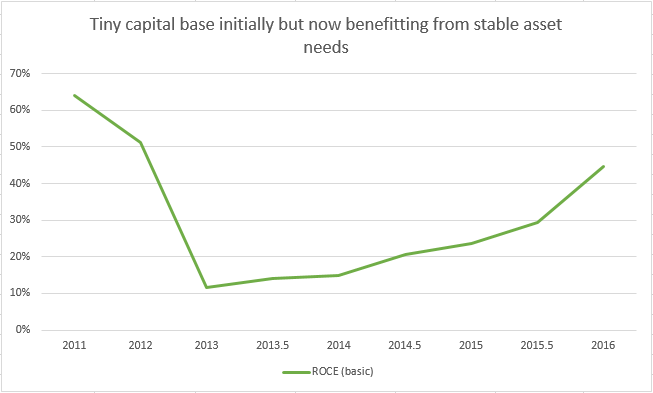
At the same time as profits have grown the return-on-capital of the business has improved and now stands at a remarkable 45% (compared to 12% in 2013). This is a recent high-water mark though and back in 2011 the ROCE hit 64% - although the capital base at the time was extremely small and this, in fact, acted as a brake on performance. In 2013 much-needed capital was injected into the fledgling business and it is this which enabled Fever-Tree to expand. That said the company intentionally outsources almost all operations and thus no longer requires additional capital to fuel expansion; so I expect the ROCE to remain unusually high:
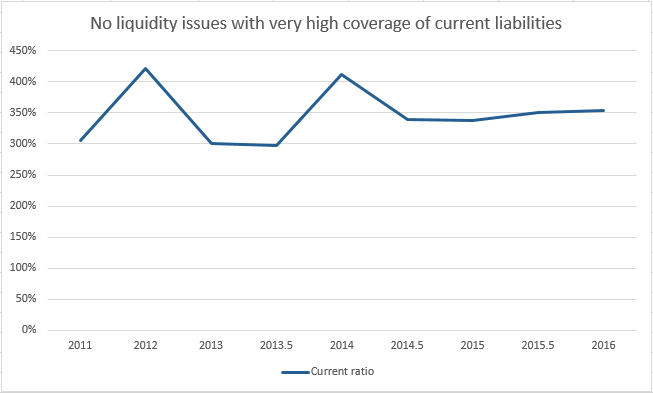
As you might expect, for such a cash-generative business, with little in the way of liabilities, there are absolutely no liquidity issues to concern investors. All monies owed by the group, both current and non-current, are covered by cash put aside and the current liquidity position has been excellent for at least the last five years:
Of course not everything is perfect with Fever-Tree, thankfully, and one metric that gives me some concern is the debtor days figure and its upwards trend. Simply put this is a measure of how much of the company turnover is owed by customers at the reporting date; so if a quarter of the annual turnover is owed then the company is getting paid after roughly 90 days. For Fever-Tree this figure used to hover around 80-90 days but recently breached the 100-day level:
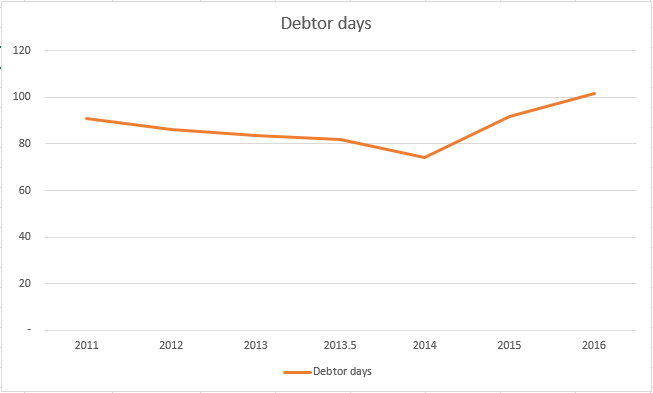
This isn't necessarily a concern and may simply be explained away by very strong UK trading at Christmas and resulting debts being outstanding at the end of the year (with all of these converting into cash by now). Nevertheless I'd like to keep an eye on this although it's a little tricky as trade receivables aren't reported separately in the interim results; so I'll have to use total receivables as a proxy in order to figure out whether these are continuing to rise more quickly than sales.
The final, financial, aspect of Fever-Tree which made me look twice concerns staff salaries. Remarkably this £1.8bn outfit gets by with just 40 employees, including directors, and as a result the director remuneration tends to bias any average salary calculations - even though they aren't paid extortionate amounts (Tim Warrillow takes home £725K inc. bonus). With director pay removed the average salary of the other 37 employees is now almost £100K with a CAGR of 21.6% over the last five years:
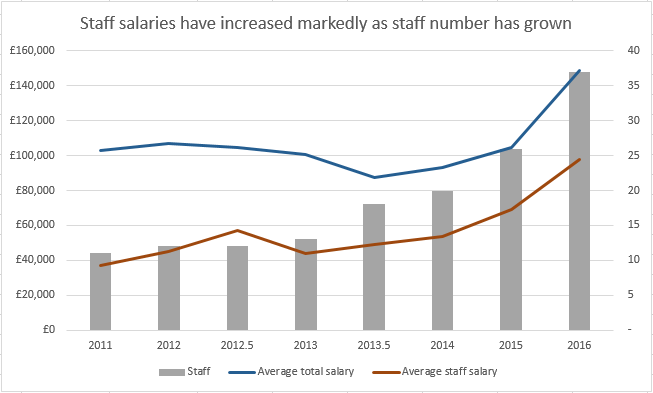
I don't particularly begrudge staff members taking home such a salary - they've chosen a good employer and must all be contributing to the firm's success - but I do wonder how much key man risk there is here and whether the company are having trouble recruiting? As with the debtor days increase I don't feel that this is a significant issue but I wouldn't like to see it get out of hand either.
Business risks
On the corporate side of things Fever-Tree has a very simple business model which requires minimal capital expenditure as so much of the supply, bottling and distribution is outsourced. The USP here is their brand-name, reputation, market position and (perhaps most importantly) ability to execute. In the latter area I take some solace from the fact that the directors were farsighted enough to see an opportunity, lend the company significant sums when necessary, partner with LDC for both funds and advice at the right time and then IPO the company to throw off the yoke of private equity. There's nothing inevitable about this progression and yet Charles Rolls and Tim Warrillow have steered the company well so far.
Still it's quite amazing that all of the manufacturing and distribution is outsourced, with Fever-Tree providing just the raw materials for assembly, and it's here that the key risk resides in my opinion. The company uses specialist suppliers, and works with commercial flavour houses to develop new flavours, and the number of these is limited; continuity planning, redundancy and insurance help to mitigate supplier risk but without ingredients there is no company. In addition the business is fully dependent on partner companies for bottling, storage, distribution and sales; these firms could probably survive without Fever-Tree but the reverse is up for debate.
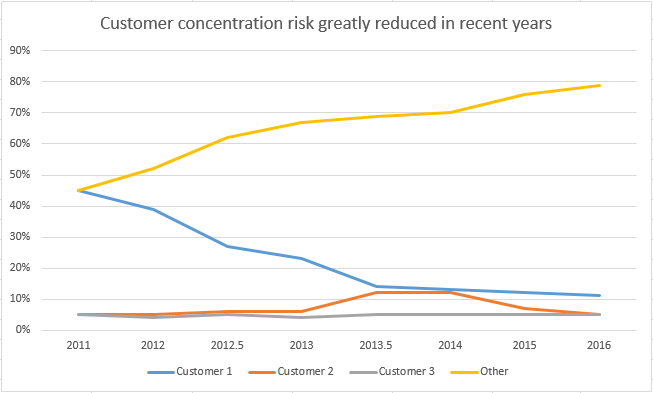
On the client side Fever-Tree started, as so many small companies do, with one or two key customers. This is fine when you're starting out but the directors have worked very hard to reduce customer concentration risk and this has certainly paid dividends - with the largest customer now providing no more than 11% of total sales:
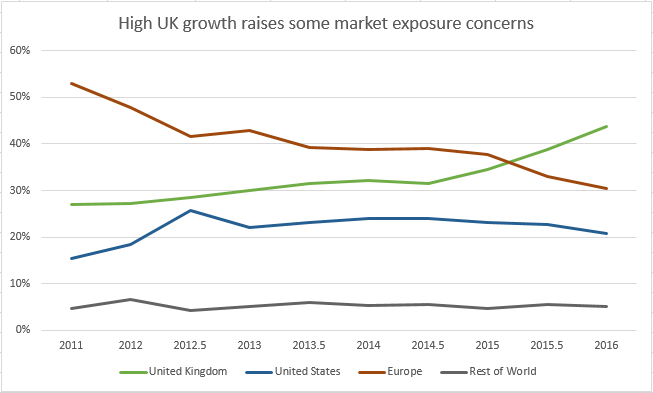
At the same time the markets which Fever-Tree serve have changed somewhat and when you compare these it's clear how dominant the UK market has become with over 40% of sales (at the expense of European sales). In comparison the US and Rest of World sales look to have stagnated with their unchanged fractions of total sales:
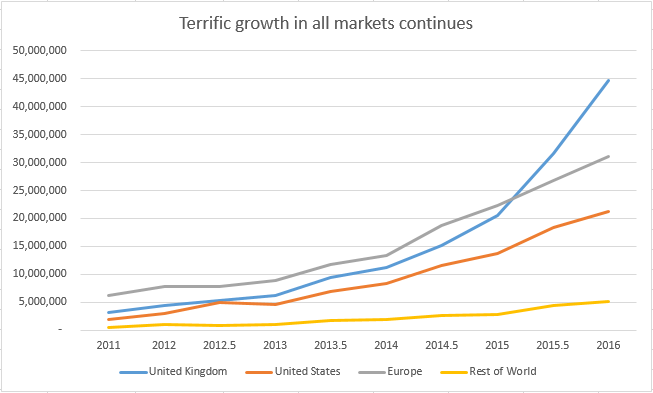
However this graph is a little deceiving as the astonishing acceleration in UK sales, more than doubling over the last year, thoroughly overshadows that of other markets - and yet these other markets are all growing at a rate that would make any other company proud. So it's worth remembering that the board are delivering on their strategy to expand on all fronts with seemingly minimal competition from fragmented brands such as Schweppes:
Interestingly this is not sufficient for Fever-Tree and they've identified a whole new market: dark spirits. Right now gin accounts for only 6% of premium spirit sales while dark spirits take up a whopping 60% - which explains why the company wants to move into this sector now that they have established themselves as a brand. There's clearly an opportunity here for co-promotion activities and new product lines leading to a step-change in growth; I don't think that the founders are ready to sell out just yet if this is their plan!
Conclusion
Ordinarily I'm quite wary of companies with a short public history as there's no proof of either the company or management being able to navigate stormy waters - and Fever-Tree is just 2½ years into its quoted life. However the brand has been around since 2005, with accounts available from Companies House, and managed to move into profit during the depths of the financial crisis. Since then, as we've seen, the business has performed staggeringly well with a serious level of cash generation.
So operationally the business has nailed its market but, perhaps more importantly, the strategy so far has been spot on. Whether taking capital and advice from LDC at the right time, choosing which partner companies to stick with or getting onto the Hairy Bikers TV show (the video is well worth watching - it's a fine advert) the directors have made many smart business decisions. Looking forwards the opportunity in the dark spirit market could make everything up till now look like small beer and Fever-Tree already know how to work with the big distillers; so there really is everything to play for and any resulting product diversification is very welcome.
Now while the directors did sell 10% of their respective holdings last year I can hardly blame them in taking some money off of the table and they still own more than 20% of the company (Charles has 15.1% while Tim gets by with 6.7%). So I believe them when they say that they're in for the long haul and, apart from LDC, this appears to be the prevailing attitude of the founder shareholders:
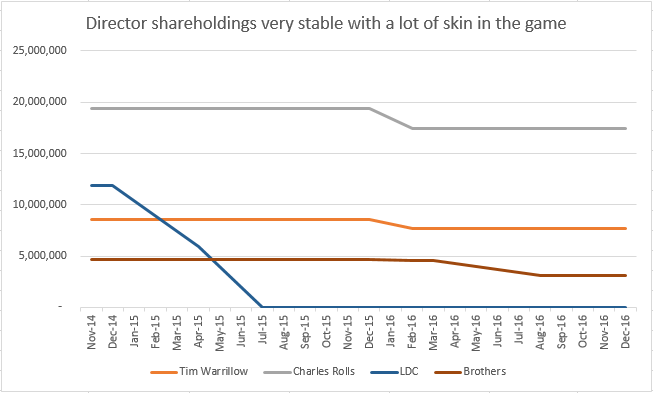
Also the directors aren't choosing to abuse their position by awarding themselves huge option packages or obscene salaries - right now the outstanding options stand at <1% of the total share count and the award scheme is quite straightforward. So I see very little to dislike about Fever-Tree apart from the fact that it's, essentially, a single-product company and thus vulnerable to interruptions in ingredients, bottling and distribution or some quality-related disaster that damages its luxury reputation. Risks which shouldn't be idly dismissed but I have no doubt that the board are fully aware of them too.
Finally, from a Stockopedia perspective, Fever-Tree is outstandingly a Quality-Momentum play: strength in earnings and price momentum combined with high margins and returns have been present from flotation. However the overall stock rank is second-quartile because the value rank is abominably low and likely to stay that way:
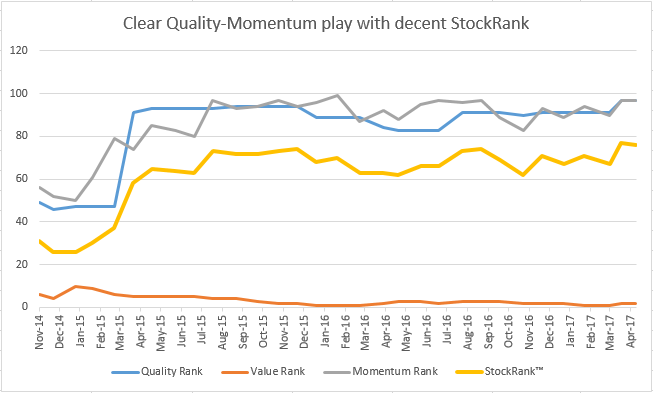
I don't particularly mind stocks having this QM bias but there's no doubt that Fever-Tree is an extreme example. Still, if the company continues to upgrade analyst estimates and grow in all targeted markets then it'll surely grow into its valuation.
Disclosure: the author holds shares in this company.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
40 comments
Is Fevertree a good buy at £26.20? The valuation by Discounted Cash Flow is £6.53 and by the Ben Graham Rule of Thumb is £13,92. The PE (f) is 44.5 and the Price to Book Value is 20.4. In my opinion - and I'm no financial analyst - the price of Fevertree is currently determined by the emotions of Mr Market rather than the principles of Warren Buffett. In twelve months time, the price could be £60 or £5. I might have a flutter at £20 but I certainly wouldn't invest serious money in Fevertree.
Using PBV to value a high growth company is a bit silly IMO, particularly where the company is by design capital light with very few assets, which in turn leads to very high returns on capital which make it such an attractive investment. Even so, there are only £42m of intangibles on the balance sheet and if you think the Fever Tree brand is not worth several times that to a Unilever, Coca Cola, Pepsico et al. then that only goes to show how silly using PBV as a measure of value is.
Also PER is a bit meaningless. I know lots of people use it but the fact is using a high PER as an excuse would've stopped you investing when you could buy for £5 and then missed a serious multi-bagger. Very high quality companies always look expensive, its just a fact of life. I realise it's a big IF but if they do break the US market the current share price is going to look cheap, and failing that it's not difficult to see one of the huge multinational consumer defensive companies taking it out.
All the best, Si
Fevertree has been one of my favourite stocks over the last 3 years.
I have held for long periods and benefited from the its success in beating earnings (in spite of its high PER).
It's really been an investment that you just can't rationalise on any value metrics.
More recently (since Dec) I have been trading in and out FEVR, which has been quite lucrative in Jan, especially as it is a particularly cheap share to buy and sell.
As for the future, I can honestly say I have not got a scooby what it will do. Their model is particularly suited to growing overseas, with the upstream and downstream processes being out-of-house, and they will neen to grow well overseas to keep this snowball rolling. So its about can they fully establish the brand in the US and Europe I guess. In the UK, they stole a march on the premium sector while the big incumbents were sleeping, will the US and Europeans allow the same (also there is no moat particularly, so a new rival could emulate this in other countries).
So, I'm going to continue to trade it on the volativity. If it keeps rising, all well and good, but if I get stopped out, like this morning, I'll bide my time for a new appropriate entry point and probaly repeat this until something new happens.
I've put together a follow-up article here: http://www.damiancannon.com/bl...
In a nutshell £FEVR is still a great company but there are lots of questions that remain to be answered around its growth potential outside of the UK.
Many thanks Damian for that thorough analysis. There was a similar article in this week's Investors Chronicle which draws very much the same conclusion.
I agree with your summary:
It seems clear to me that Fever-Tree is a very profitable business but it's priced as if historic growth levels will be maintained (with high returns on capital) and I don't think that the accounts support this optimism.
The share price of Fevertree (currently £26.20) has fluctuated from a high of £39.80 on 7th September 2018 to a low of £20.93 on 27th December 2018.
Is Fevertree a good buy at £26.20? The valuation by Discounted Cash Flow is £6.53 and by the Ben Graham Rule of Thumb is £13,92. The PE (f) is 44.5 and the Price to Book Value is 20.4. In my opinion - and I'm no financial analyst - the price of Fevertree is currently determined by the emotions of Mr Market rather than the principles of Warren Buffett. In twelve months time, the price could be £60 or £5. I might have a flutter at £20 but I certainly wouldn't invest serious money in Fevertree.
No problem. I didn't know about the IC article but it's nice to know that I've been thinking along similar lines. The price really could go anywhere from here - it all depends on sales in the US taking off in a meaningful way.
Thanks - I didn't know about the IC article but it's nice to know that I've been thinking along similar lines. You're right that the price really could go anywhere from here. It all depends on the US and growth there providing a material change in total sales.
Market only expects 43% so I think most investors expected it to be beaten, I don’t the shares will recover enough to reverse recent fall until the results. I happy to wait until then. Once again this shows that forecasts are often way out. It’s the same with Burford Capital (LON:BUR).
Today's trading statement. Materially ahead enough to reverse the recent pull back?
--------------
Fevertree Drinks plc ("Fever-Tree")
Trading Update
Fever-Tree, the world's leading supplier of premium carbonated mixers, today announces a trading update ahead of the year ending 31 December 2017.
The Board is pleased to announce that the strong growth seen in the first six months of 2017 has continued during the second half. Fever-Tree's pioneering focus on taste and ingredients continues to transform the global mixer category driving growth across all the Group's regions. The exceptional performance in the UK, the Group's largest market, has been particularly impressive with the rate of sales growth and momentum strong across both the on and off trade. The mixer category is now the fastest growing category across the UK soft drinks sector with Fever-Tree responsible for 97% of the value growth in retail over the last 12 months.
Given the strong performance in the period to date, the Board anticipates that the results for the full year ending 31 December 2017 will be materially ahead of current market expectations.
Having looked at the growth figures again, Europe and USA do have benefit from currencies so yes the figures are lower, US is 29% and Europe is 53%, on a constant currency basis. Seems premium mixers are a new thing in the US market. I think they were in the right place at the right time in the UK, just when the interest in gin was taking off, other markets are different. I think the USA may take more marketing to crack. Interesting that the dark spirits market is larger than for white spirits, I know Fevertree Drinks (LON:FEVR) are trying to get into that, maybe more difficult.
After a first quick glance, it looks to me like FEVR is using the Coke model. They focus on flavors and syrups, and they leave the capital intensive processes like bottling to other companies. Those are the drink brands that give the best financial metrics.
That said, the stock is too expensive. I did a reverse DCF on it, and to get to the current price they need 31% compound growth for 10 years. Your own charts show growth in Europe and the US stabilizing, and the important US market is already at a "mere" 20% growth. I think they are challenged to justify the current price by growing everywhere at 30%, and even if they could do that buying at that level would only earn you the discount rate (I used 12%).
With a possible brexit consumer recession at hand in the UK, I would like to be a bit greedy here and wait for a disappointing quarter.
But in the latest update the EPS was up over 100%. I don't think a UK recession will that much effect on them, the growth now is more overseas, UK is only about 30% of revenue. Also it's the sort of product that may not affect by recession. Drinks companies tend to do alright in recessions.
@herbie47 The stock market is a forward-looking value calculator. The only people who obsess about historical results are consumer investors like us. Analysts and funds focus on the future. If you look at the 2017 and 2018 estimates, 2018 estimate has earnings growing 12%, not 100%. So the stock ran up in a huge way to that 100% growth, and now - *maybe* - the pressure you see on price is the market worrying about those forward estimates and the possible slowdown.
I don't believe 12%, but just for the sake of argument, if you take the 2017 estimated earnings of 0.34 per share and feed that to a DCF calculator, using 12% growth for 10 years at a 12% discount rate, the fair value is 578. The stock is trading at 1962!!! To justify that nosebleed valuation, you need to sustain 30% compound growth for 10 years.
30% compound growth is the stuff of legend. I am not saying they cannot do that. (I really have no opinion because I have not studied the business well.) I am simply pointing out that the post made here shows US growth slowing, and it is already down to 20%. The post made here shows European growth slowing and in a downtrend, and it looks like it will head below 30%. The one stalwart is the UK, and if the UK has a few bad results due to a recession, that will affect the perception of forward growth.
You made a good point that during a recession there may be no effect on the consumption of this product.
All of the above is intended to promote healthy conversations about valuation. Whatever else you say, the stock is not "cheap" at its current price. Below 1000 I start to get very tempted, but please understand that even a price of 979 implies a *compound* growth rate of 20% for 10 years, which is a phenomenal company.
If you look back over the last 2 years at the estimates on eps, you will they have been smashed by the actual results. I sold out a while ago at around 1750p but bought back in after the last figures which were amazing. I see it going this way, still growing quickly but then growth will start to level off probably in the next year, so it’s not a share I’m looking to hold long term. The 12% growth for eps in 2018 may well be correct but I doubt the 45% for 2017 will be. The post here was done in May before the interims were published in July. Europe was up 64%, is that slowing down? The USA is up 43%, it’s not slowing and it’s a much larger market than the U.K. which is a very small country. So actually there is a vast market out there but drinking trends change so gin and vodka could be out of fashion in a few years time.
Personally the valuation is a bit rich for me. The growth rates exhibited by Fevertree do not justify this sort of multiple IMO. Apparently great company and products but this share may possibly nose dive in a 'risk off' investing market. Too risky for me hence I recently sold my shareholding.
Hi Carcosa
I can understand you thinking the valuation is rich if you are basing it on future estimates of performance rather than actual past performance.
Fevertree have a history or hammering broker estimates, therefore you may find looking at the last 2 years performance a better guide to their future performance than broker estimates.
In the last 2 years they have achieved eps growth of 416% & 106%, do you really believe in the next 2 years their eps is going to grow by 10% & 11% as per current broker estimates ?
A companies history of beating broker estimates needs to be taken into account when relying on them for valuations.
Yes but are the others growing at anything like the rate of Fevertree Drinks (LON:FEVR).? Forecasts are often wrong, last year forecast was EPS +28% in fact actual was +106%, already this year the latest update is comfortably ahead, mind you forecast of +10% I think is very conservative. Yes I think they need to produce around about 40% growth to sustain the share price. Of course their are many high flyers that look expensive but still the share price goes up, of course if something does go wrong then they will plummet.
Carcosa - re. Fevertree Drinks (LON:FEVR)
This company's relative valuation over recent years has always been very rich compared to its peers.
If you look at similar metrics to your exhibit above say in December last (you can do so by clicking on the Print button in the StockReport screen and look at past pdf screens) , you will see the PE 2016 = 48 and PE 2017 = 47.
Winding the clock back, the reaction would have been the same; far too rich compared to its peers.
So selling at that time would have meant leaving 60% share price growth on the table.
The real question is how do you value a share like FEVR because it sure ain't by just looking at the traditional valuation metrics. The same question applies to pure play internet businesses and platform businesses. I do not know the answer, but wish I did.
No position, long or short.
The real question is how do you value a share like FEVR because it sure ain't by just looking at the traditional valuation metrics. The same question applies to pure play internet businesses and platform businesses. I do not know the answer, but wish I did.
For me it's a simple four step process:
1. How big is the market they are addressing?
2. What market share will they have in 5 years time?
3. What margin will they make?
4. What p/e is appropriate in 5 years time?
Tonic water is estimated to be a $2bn market in 2022. https://www.prnewswire.com/new...
If Fevertree Drinks (LON:FEVR) can achieve a 25% market share & maintain 35% EBIT margins, then their Net income in five years time will be:
$2bn * 25% * 35% less 30% tax = $122.5m = £93m (GBPUSD 1.31)
Clearly at this point their growth rate will be similar to the market growth of 5-6% (unless they can win more market share) so a p/e of 20x seems more appropriate than the current p/e.
So 20 x £93m = Market cap of £1.86bn in five years time
That the company trades today at £2.2bn today suggests:
.
Fevertree Drinks (LON:FEVR) already have numerous other drinks in their portfolio. Lemonade, ginger beer and cola are a few, better to look at this: http://www.fever-tree.com/our-...
@Howard, very nice out of the box thinking. It confirms from a different viewpoint that the current valuation absorbs huge success and leaves little additional upside unless truly miraculous things happen.
Do you have the numbers on Fevertree's current market share for tonic water in each region where it participates?
I find your assumption about 25% penetration within five years to be pretty optimistic, particularly considering that they have not penetrated well into Asia yet. It would be interesting to calculate how much market share do they need to steal per-year to get to your 25% target.
Good trading statement put out at the AGM today: http://www.investegate.co.uk/fevertree-drinks-plc/fevr/agm-statement/201705150700080577F/
Hard to see why the price is down when forecasts are, yet again, set to be upgraded: "Given the strong sales in the period to date, the Board anticipates that the results for the full year ending 31 December 2017 will be comfortably ahead of current market expectations."
So the expectation of the market is that Fever-Tree will be ahead of market expectations. Tricky. I am still long, but am "taking profits".
Yes I'd agree that the market is pricing in continued 'ahead of expectations' performance hence the lack of reaction to the update. However Fevertree Drinks (LON:FEVR) is continuing to meet this meta-expectation and I think that there'll remain upwards pressure on the share price while this is the case.
One note on competition. C&C Group had a huge success with Magners/Bulmers Irish cider in the UK & Ireland by selling it at a premium. However, the competition came in and undercut them. You can see the impact on C&C's share price. The brand Innocent used to sell its drinks at a higher price than it does now but has had to react to increased competition.
I haven't given a huge amount of thought to this area. Probably people are loyal to their tonic waters. However, a number of other companies are trying to compete with Fevertree.
I don't think it's quite the same as the cider market. Magners spent a vast amount of money making cider a trendy drink in the UK market. HP Bulmers (nothing to do with C&C, owned by S&N) just rebranded their Bulmers cider with similar label and undercut Magners on price, I know I used to buy it for a bar, we stocked Bulmers. Cider predominately UK market but spirit mixers is worldwide, there is still plenty of expansion room for Fevertree. Yes Schwepps could rebrand their tonic water etc (think they have already?) and relaunch it, but just by undercutting it on price will not be enough, remember this is for premium spirits market. Fevertree is number 1 brand and is in the sweet spot at the moment, I can see DPS or someone buying them out.
I bought in only a short while ago having not done so earlier because of the valuation. I changed my mind when I realised that the international expansion means this has a long way to go before it starts to slow and so the valuation is not so difficult.
I saw just a short while ago that it is being sold in Venice. Looks like this is a strong global brand in the making.
harvs19 - thanks for the feedback. It is amazing in investing that we can focus on financial stuff so much and sometimes forget to ask: is the product/service any good? At Master Investor they did a blind test for Fevertree versus Schweppes and Fevertree won by a long shot. I haven't assessed Fevertree recently but clearly they are with the consumer shift towards premium and natural products. The difficulty in making an assessment is the competitive environment and how this will evolve.
Ratio investor - completely agree with your comments regarding not forgetting the quality and appeal of the product. Valuation is very high now but clearly this is for a reason. They are by far the market leading premium brand in this space. You mention that Fevertree 'would' have been a much better bet, are you implying that you think the opportunity here is gone? I am late to the party here but after researching I believe there could be much more to come on this. The move into dark spirits is very exciting and if they execute well and the products see the same traction as their gin mixers then surely this momentum is going to continue, and possibly accelerate. The question I am asking myself is if everything pans out well where will the valuation be in around 5 years time? My feeling is considerably higher.
Damian, Great writeup. In my view, Fevertree highlights that we should also focus on the product and its prospects rather than just financial data. Is the Fevertree product any good and what is its growth potential? Will it be able to see off competitors. Lots of financial analysis is interesting but it is the fact that Fevertree has a great product that has driven top line sales. Margins have been preserved with competitors finding it hard to launch a rival.
Obviously financial data from companies like Stockopedia helps but what makes a company successful long-term is its product/service. It is easy to forget this when assessing valuation metrics, margin trends etc.
At the end of the day the only thing that has made this company do well is the popularity of its product and the resultant rapid sales growth. To forecast a qualitative assessment is necessary.
It is easy to take the accountant's approach of knowing the price of everything but the value of nothing. What I got wrong on Fevertree is that I didn't quickly search for online reviews of its products versus the competition. I also didn't assess the market segment and the scope for disruption.
In the end I opted for Britvic which has seen very little growth and significant competition in stills (Robinsons) from the discount supermarkets. Fevertree would of been a much better bet.
Hi ratioinvestor - thanks very much for your comments. I very much agree that numbers aren't everything and that a qualitative assessment is important too. Anecdotally I prefer Fever-tree tonic and have been seeing it pop up all over the place (the local pub, on BA flights etc). However I figured that my report was long enough without adding any more discussion!
What I hadn't fully appreciated before is how much emphasis the board put on obtaining quality ingredients and ensuring that they maintain this level of quality. This is a real differentiating factor and I can see why competitors are finding it hard to catch up.
Curiously though I'd previously discounted Fevertree Drinks (LON:FEVR) precisely because of the numbers! It always looked super-expensive and I failed to appreciate the growth rates being achieved and the desire of management to build a bigger and better company.
Damian
Damian
An excellent write up (as Ed writes, above) and nice extra bits with the links such as the Hairy Bikers short clip. Many thanks.
Regards
Howard
Indeed. Further cut down by picking two least risky characteristic settings and Stock Rank of >=80 takes it down to a more manageable to research 26 ....
http://www.stockopedia.com/screens/high-flyers-210736/
Gus.
gus - many thanks. Wow, that many?
Ed - I am sure it is there somewhere, but how can I screen for all shares that have the attribute High Flyer?
Ram -
Quick and dirty High Flyer Stock Screen ....
http://www.stockopedia.com/screens/high-flyers-210736/
About 200 or so to choose from.
Gus.
Superb piece Damian as always.
I just thought I'd mention that we've just released the StockRank Styles in StockReport headers.
If you know the hierarchy - Fevertree is one of the top "High Flyers" in the categorisation.
Yes just been looking at those on some of mine, surprised that Beximco Pharmaceuticals (LON:BXP) is style neutral considering the share price rise this year of 250%. I thought it would be a high flyer?
Herbie - it's right at the margin and slipped into the Neutral bucket. The Value Rank is too high to be a High Flyer, but too low to be classified as a Super Stock. So it sits in the middle for now until something shifts.
Ed, thanks, yes I just find some of them a bit surprising, Beximco Pharmaceuticals (LON:BXP) is neutral but Patisserie Holdings (LON:CAKE) is a high flyer.
Is there a way of seeing a list or screen with say the Super Stocks UK?
But Card Factory (LON:CARD) is a high flyer and it's has a higher VR than £BXP?
Thanks Ed. That style makes sense to me and I'm looking forward to the webinar in a few minutes.
Well done for adding yet another dimension to this great site!