FTSE 100 forecast and valuation – June 2015

It’s time for another one of my semi-regular FTSE 100 valuation and forecast updates, using the latest data for both the index’s price and its earnings.
Valuing the FTSE 100 using CAPE
My tool of choice in the valuation game is Robert Shiller’s CAPE (Cyclically Adjusted PE). CAPE is basically the same as the PE ratio that most investors are familiar with, except that is uses 10-year inflation adjusted earnings as the “E” part of the ratio.
It does that because the 10-year earnings average is a much more stable number from one year to the next than just a single year’s earnings. That’s important because we want something nice and stable to compare the FTSE 100’s price to.
In other words:
CAPE is like measuring the distance between two points on the ceiling while stood on a solid table, whereas the standard PE is like doing the same measurement stood at the top of a wobbly step-ladder.
You’ll get an accurate measurement with one and a dangerously inaccurate one with the other (dangerous if you fall off the ladder anyway).
Calculating “fair value” for the FTSE 100
Today, the FTSE 100’s 10-year inflation adjusted earnings stand at 530 index points. I’ve put the value into index points because that’s how the index is measured.
So with a current price of 6,700 index points, the FTSE 100’s CAPE is 12.6.
That’s actually pretty low. The long-term average, across multiple international markets, is somewhere in the mid-teens, around 15 or 16.
If the market were at “fair value” today, i.e. with a CAPE ratio of 16, it would be at 8,500. At that level it would have a dividend yield of 2.8%.
That sounds a little high (i.e. low yield) to me, but not significantly so as the market’s long-run average dividend yield is about 3% (we’re at 3.5% at the moment).
I could just stop there and say that the FTSE 100 is slightly below the typical long-run average of 16, and therefore it’s “slightly cheap”.
But that’s a bit dull, so here are a couple of visual tools to illustrate what the market’s valuation means for future returns.
CAPE is “mean reverting”, and that’s a good thing
First though I’ll take a little detour into the world of “mean reversion”, as that underpins everything else (skip this bit if you already know all this).
The FTSE 100’s CAPE is a mean reverting statistic, which simply means that the further it is from its long-term average, the more likely it is to move back towards that average.
This is a common feature of many financial statistics, such as the house price to earnings ratio.
Despite what some property pundits think, house prices are indelibly linked to the earnings of the people who either buy or rent those houses.
If a four bedroom flat in London is put on sale for £1, there will be a mad rush of buyers who will bid up the price to something more sensible.
If that same flat is put on sale for £100 billion there will probably be silence from potential buyers (or perhaps even a little astonished laughter). In that case the seller will have to lower the price (a long way) before any buyers become interested.
That’s why the UK house price to earnings ratio tends to hover around 4. Sometimes its falls to 3 or lower, as it did in the mid-1990s and sometimes it climbs above 5, as it did in 2008 and seems to be doing again today.
In the long-run, assuming that a mean-reverting ratio will be at its long-term average in 10 years or so is probably as good a way to estimate future returns as any. And that applies to any supply and demand-driven asset class, including the stock market and property market.
FTSE 100 CAPE probability “fan chart”
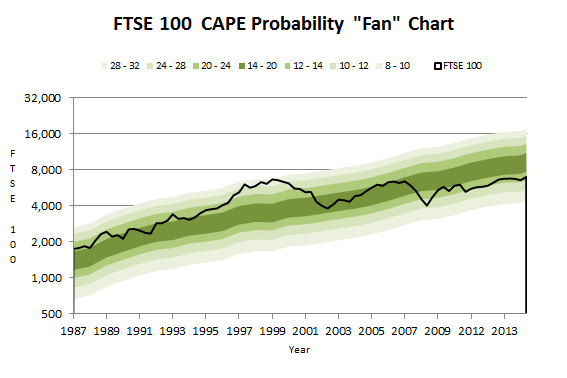
So, having gotten that introduction out of the way, here’s my first visual too, the FTSE 100 CAPE probability “fan chart”:
A few notes:
- The black line – is the FTSE 100 from 1987 to today
- The left axis – is logarithmic, which just means that each step up is double the previous step, which you can pretty much ignore if you want to
- The green bands – represent various CAPE valuation levels from a CAPE of 8 up to a CAPE of 32 (the average, in the middle, is 16)
- Darker greens – are the valuation range where the FTSE 100 has historically spent most of its time. This is where it is more likely to found be in future.
- Lighter greens – are valuation levels that the market rarely reaches. This is where it is less likely to be found in future.
So for example, the central dark green band is where the FTSE 100 would be if it had a CAPE ratio between 14 and 20, which is what I call “normal”. It is also the valuation range where the market is most commonly found.
As the chart shows, in the dot-com boom in the late 1990s, the FTSE 100 was way above “normal”. Since the market is most likely to be found in the dark green “normal” band in, say, 5 years’ time, the most likely move for the market from 1999 onwards was downwards towards that “normal” range.
And that’s exactly what happened, somewhat abruptly, in the 2000-2003 crash.
Another example is 2009, where the market dropped to 3,500 and was way below the normal (dark green) valuation range. The implication was that the FTSE 100 would rise in value back towards that normal valuation range in the next few years.
Once again that’s exactly what happened, as the market leaped upwards in value during the latter part of 2009 and 2010.
So today we effectively have a small (probable) tailwind thanks to a low valuation and CAPE’s mean reverting characteristics.
The market is likely to mean revert back into that dark green band at some point over the next decade, and since the FTSE 100 is below that level at the moment that means a valuation expansion rather than contraction.
That valuation expansion would of course be in addition to any earnings growth (typically about 4% a year) and dividends (3.5% a year with the FTSE 100’s current dividend yield).
That is, I think, the most likely outcome, but that’s very different from saying it’s the only possible outcome. The future’s not set and the FTSE 100 can do whatever it likes, within reason (as can the property market).
FTSE 100 CAPE-based future returns “heat map”
Because CAPE is mean reverting, it influences the future course of the market:
- When CAPE is high – future returns are likely to be low
- When CAPE is low – future returns are likely to be high
- When CAPE is normal – future returns are likely to be normal
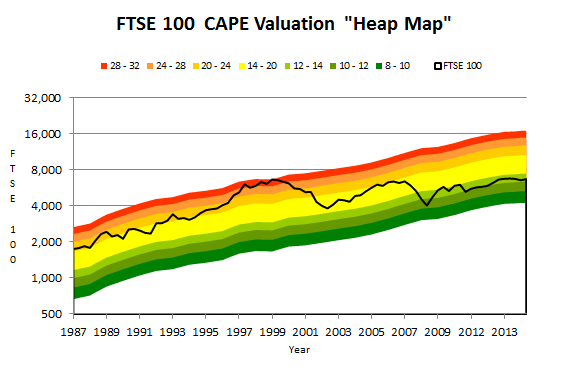
With this insight it’s possible to re-draw the probability fan chart as a future returns heat map in order to highlight the relative “goodness” of low valuations and “badness” of high valuations.
A few more notes for the heat map:
- Red – implies low future returns
- Yellow – implies normal future returns
- Green – implies high future returns
Hopefully this more clearly illustrates the implications of various CAPE valuations, and the probability fan chart should remind you that these are “likely” outcomes and not guaranteed in any way, shape or form.
We all know how badly the market performed after 1999, and this heat map shows why. Valuations were sky high, and obviously so.
Then again, in 2009 valuations were low and future returns likely to be outstanding (as they have been, as long as you could stomach the fear).
In summary:
The FTSE 100’s CAPE valuation is “slightly cheap” at 12.6 compared to a long-term average across many different markets of 16.
The implication is that in the medium-term (5-10 years) total returns are likely to be slightly above normal, where normal is around 5% total return after inflation (so about 7% if we assume inflation at the Bank of England’s 2% target).
“Fair value” for the FTSE 100 is currently 8,500 (i.e. the value that would give the index a “normal” CAPE valuation of 16), and I think it is more likely than not that the index will reach that level in the next 5 years.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
17 comments
I have an interest in the use of CAPE as a reference to the value of a particular market. There was an article in the Telegraph earlier this month (the follow up to an article 12 months previously) which gave the CAPE value of many global markets - http://www.telegraph.co.uk/finance/personalfinance/investing/11654508/Revealed-The-worlds-cheapest-stock-markets-2015.html It may help to put the UK market value in perspective on a global measure.
After reading it I considered a punt on Turkey using an ETF, but then looked a bit more, got scared and changed my mind! I'm still looking into something, perhaps Baring Emerging Europe Closed Fund (LON:BEE) or Blackrock Emerging Europe (LON:BEEP). The value of the US market does look very high (but it has for some time) and if this were to fall would have far reaching consequences with many UK 'global' Investment Trusts which have big stakes there.
Hi Patxi,
I think the best way to implement that sort of strategy is to hold all of the market indices in question, or at least, say, 30 of them, and weight them according to CAPE.
So rather than buying the cheapest market, you "tilt" a portfolio towards it, which is a much less risky approach.
There are various ways to calculate weightings based on CAPE, and I think there are some ETFs becoming available which do all of this for you. So you just buy the ETF and it holds dozens of international market indices, weighted by CAPE, or dividend yield or whatever.
John
Is the FTSE100 a good investment anymore? Yes it had good years up to 1999 but since then it has not gone anywhere, if there is another fall even after 15 years you would be worse off. Yes you can add in dividends which are about 50% over 15 years but then inflation is 55% over that time.
https://uk.finance.yahoo.com/echarts?s=%5EFTSE
Herbie47 wrote: "Is the FTSE100 a good investment anymore? Yes it had good years up to 1999 but since then it has not gone anywhere, if there is another fall even after 15 years you would be worse off. Yes you can add in dividends which are about 50% over 15 years but then inflation is 55% over that time."
Perhaps the fact that the FTSE 100 has had poor performance over the latest 15 years means that it is now relatively good value (which is also indicated by its current CAPE as pointed out by this article), so its performance over the coming 15 years is likely to be a lot better than over the latest 15 years.
Yes good point but looking at the charts looks like a fall is due? Who knows. My concern is more the other markets and economies such as China and USA, not to mention Greece and the Europe.
I would second what pka said. The 15-year period since 2000 in which the FTSE 100 has largely been flat was made possible by its extremely high starting valuation. As my charts hopefully show, the market's "normal" valuation has been steadily increasing, the the point where it is now above the "market" value. However, that process took 15-years or so (with obvious ups and downs in the market) precisely because of the high starting level of the FTSE 100.
It is possible that the FTSE 100 could face another 15 years of zero capital gains, but it would be very unlikely. If that's what happened then we would probably have a FTSE 100 in 2025 with a dividend yield of 5% or more, which would make the market very attractive to investors (i.e. buyers who are likely to increase demand and push the price up).
Thanks for a very interesting and useful article.
Does the CAPE approach take into account very long-term trends? For example, in the 20th century, there was a long-term trend for institutions like pension funds and insurance companies to have a gradually increasing percentage in equities in their portfolios, which presumably caused a gradual increase in typical price-earnings ratios of equities.
Hi pka, I would say only to a small extent.
If PE ratios are going to be at permanently higher levels than in the past then that will push up CAPE's long-term average. This will effectively increase the "fair value" level of the market, although any increase would be very gradual.
This is one reason why I prefer to measure CAPE's "long-term" average over a fixed 100 year period (where the data is available, e.g. S&P 500) rather than from the earliest possible point, which is the 1870s I think, going by Shiller's data.
Calculating the average over 100 years rather than "forever" will make the average a bit more volatile (although hardly) but it will also follow recent trends more closely (although not that closely as it's still an average over 100 years).
Thats interesting. I would like to see one for the FTSE250 I suspect that will be higher. I did find one for the FTSE All Share and that was similar to the FSTE 100. Apparently the USA Cape is very high.
Hi herbie47, I have looked at doing the same thing for the FTSE 250 but the data is even harder (i.e. impossible) to get hold of for that index.
If someone can find the data I can do the analysis.
The S&P 500 CAPE is about 27, which is pretty high and way above the average of 16. I think it's only been higher on two occasions (without double checking the data) - in the boom of the late 1920s and the boom of the late 1990s, neither of which ended well!
That is worrying, even if our market is good value I'm sure if the USA bubble bursts we will be affected by the fallout.
Perhaps, although the US market could just have weak returns for a decade rather than go through a boom and bust period.
However, even if the US market did fall by 50% and the UK market by, say, 30%, why should that be worrying?
If you're investment horizon is more than a decade, what does it matter if the stock market falls this year? All it means is that you'll be able to pick up good companies cheaper than you could before.
And if you investment horizon is very close (perhaps you're about to become financially independent?) then you shouldn't have a large allocation to equities if you're worried by capital volatility.
Either way, a falling market should not, in and of itself, be a reason to worry. Although that's not to say you shouldn't worry about the economic factors underlying a market collapse, such as a recession, but that's an entirely different matter.
I understand what you are saying but if your investments fall 30% and it takes 5 or more years to recover that is quite a large loss. The problem is if you sell shares you may have to pay capital gains tax. Yes I have moved more into cash and Im considering other investments such as gold.
The logic of the benefits only applies if you have fresh supplies of investable capital. If you have a single relatively fully invested portfolio into which you aren't feeding new money then whatever your time frame falling prices are unarguably a bad thing or at best a neutral thing, certainly never a good thing.
Hi Richard, you're right, but only if dividends are being drawn down too. If an investor is in drawdown mode with no intention to invest new funds then falling markets are undoubtedly a bad thing, or at least they're bad for whoever will receive the capital value when the portfolio it is finally sold.
However, if dividends are being reinvested then lower valuations are likely to produce higher returns on those reinvested dividends, which of course is a good thing in the long-run.
I liked the presentation very clear,how do we apply the cape to individual stocks ?
Hi brinrich, generally people use PE10 rather than CAPE for individual stocks, which is basically the same but not adjusted for inflation.
You can use PE10 anyway you like, just as you can the standard PE.
You could use it in isolation, comparing it to the PE10 of similar companies, or any other company, or against the market's PE10, or against pre-defined maximum or minimum values.
Or you could combine it with other ratios that take growth or gearing into account. The options are endless (which may or may not be a good thing).
I don't want to promote my own stuff here on Stockopedia too much, but you can find some ideas on how to use PE10 on my website, as well as some related spreadsheets.
At the end of the day it's just another ratio, but one that is well suited to blue chip stocks and similar companies with long histories of profit.