Gervais Williams interview: Big ambitions for smaller companies

Gervais Williams agreed to meet me for lunch at a brasserie around the corner from his offices in the shadow of St Paul’s Cathedral. From here it’s a stone’s throw to the London Stock Exchange on Paternoster Square. In his 30 year career in the City (he was an engineer before that) Gervais has been a huge advocate for investing in one of the exchange’s most exciting and occasionally controversial offshoots - the Alternative Investment Market - and it’s our main topic of conversation.
It’s not uncommon to come across fund managers with strong views about investing methodologies. But this is a man with utter conviction in the value of investing in smaller companies. They’ve been a regular source of outperformance for him: first during a long spell at Gartmore and now during five years as Managing Director of Miton Group plc. But more than that, in the aftermath of a protracted credit bubble, he predicts a certain resurgence for small-caps. He also believes that fund managers could and should be allocating more capital to the very best home-grown firms, not just for clients but for the sake of everyone.
Gervais, what’s does a regular day for you and your team at Miton look like?
Well, I take an hour’s walk to the office. The whole team meets to review results on the screen at 7.00am and there tends to be a lot of discussion about upgrades and downgrades. By around 9.00am we’re usually doing face-to-face meetings with corporates. Last month [March 2016], Miton, which includes my team as well as Europe and the US, did over 140 meetings with corporates.
The best part of the process is meeting companies and making decisions. We can use sophisticated models and pick up new trends coming through, but there is nothing better than talking to the companies themselves. I probably see more companies than anyone else, in between reviewing portfolios, meeting clients and looking at new challenges that are coming up.
You literally wrote the book - The Future is Small - on why smaller companies hold such strong investment appeal. Can you tell me about your thoughts on why that is?
As we all know, the long-term purpose of investing is to allocate our collective savings to the best and most productive companies. One of the problems is that when you’re making a lot of money for your clients, as many people have since 2008, that doesn’t necessarily mean that the money is getting down to the best companies. People have made money in indices, in various types of options and sophisticated structured products. I think I’m more cautious about the future and I think we’ll have to get better at allocating and better at improving productivity and better at explaining what we’re doing in terms of being socially useful.
That sounds a bit mushy, but as well as looking after our clients, which is tremendously important, it’s also about looking after the wider electorate who worry about jobs and paying their mortgages and getting pay rises to meet rising costs. This is a factor that I think is going to become much more politically mainstream.
Take index funds, which are very popular at the moment. They’re low cost, which is brilliant, I love low cost. But if it’s just allocating to the biggest companies, which aren’t all that UK orientated in the first place, then effectively we’re putting our savings overseas. Now there are good reasons for diversifying overseas but the truth is that we should be investing more at home. It’s good for job creation and domestic growth and takes advantage of the ability of some of these smaller companies to grow even when the world’s not growing.
For some years I’ve been talking about the credit boom coming to an end in 2008, and how we’ve had a mini-credit boom since in China. What’s happened is that credit boom trends have been with us for so long, that there’s nearly an entire generation in the City that think that credit boom trends are normal. My view is that they’re not normal, that abnormal is coming to an end and we’re getting back to normal.
We’re in a period where there is little world growth, a lot of big companies are really struggling to get top line growth and hold margin in certain cases. Not only that, but our productivity is really dreadful. Allocating money to the largest companies will continue to be the majority of most people’s assets when they are investing in equities, but it means that you are actually starving ‘smallness’. In the last five or 10 years we just haven’t been allocating capital to add to productivity, and that needs to be a higher priority going forwards.
It’s no secret that you’re a big supporter of the Alternative Investment Market and the companies quoted on it. Where do you see the main attraction?
I think we’re very lucky to have the AIM market. If you look around the world, the leading micro-cap market used to be Nasdaq up until the mid-1980s, but smallness has fallen down the agenda. There is no Neuer Markt or Nouveau Marche, they’ve all closed down. With AIM, we have on our doorstep possibly the leading micro-cap market in the world. There are lots of companies in there, some have done well and some haven’t, some are in fashion and some are out of fashion.
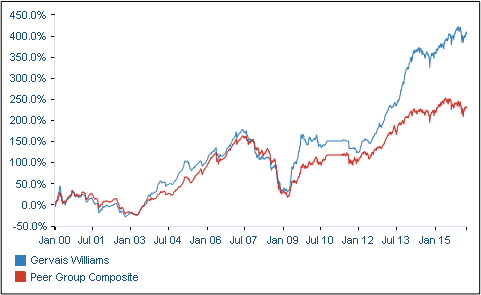
Data: Trustnet
The wonderful thing is that it’s such a wide investment universe. The point is that there are loads of pebbles on the beach. I can pick up a pebble and I just don’t know if they’re telling the truth or not and I don’t know if their proposition is going to work or not. But there are 1,600 other ones, so I can put it down.
But if you’re a big-cap fund manager looking at Shell or BP and you put it down, the oil price may half or it may double, and your clients will ask you why you have missed out on a big rise. You have to be very sure footed when you’re dealing with many of the largest companies because if you miss certain companies’ outperformance that can spoil things even if you are doing everything else right.
There have been calls for AIM to introduce more regulation and change certain rules. Do you think that the rules need tightening?
I would be careful not to get too regulated. It’s easy to keep shutting doors after horses have bolted and then you gradually get a longer and longer rulebook. So I think we have to be cautious about adding more layers of rules, although sometimes things have to be changed. We have to be focused that we don’t inadvertently make it more difficult for liquidity.
It’s easy to say sometimes that short sellers or market makers are wicked people. Some of those that came out with bear raids on stocks aren’t motivated by being helpful, they’re there to put one side of the story and move the share price for a profit, which is abusing the system.
Generally, I think we should find ways of having investors who invest on a day trading basis along with investors who invest on a three years basis, along with people who are buying on financials and those that might have a short position. All of that means you’ve got different investors buying for different reasons and selling for different reasons. That gives you a vibrant market with liquidity and prices that are continuously being set at the appropriate level. That’s largely what we have. I’m sure we can improve on AIM but I do think that it’s a winning formula already.
Illiquidity on AIM is a key issue for some stocks, which must mean that you face challenges when it comes to dealing in size?
It’s a percentage game I suppose. Sometimes we want to buy what might be a fantastic stock and we can’t get any shares. We’ve done all the work, it ticks every box in the book and it’s all looking great but we miss out. But more often than not I would say, just drip, drip, drip, we’ll buy little bits now and maybe later and build up a holding gradually. It takes a long time. I was looking at one of the largest holdings in the Miton UK MicroCap Trust, James Cropper. The fund has only been in existence for a year and we got lucky with a line of stock soon after we set it up. But off and on we have been buying that company for pretty much four years. It didn’t matter that we didn’t get a lot to start with.
Now it can be the same on the way out. The company has done well, or may not have done well, and we need to reduce. Again, it maybe drip, drip, drip to get the money out, and it does take time. But we’ve got a really long list of holdings - the Miton UK Multi Cap Income fund has around 150 holdings. We might get lucky selling some and not so lucky selling others. Usually if companies are successful they are quite easy to sell. If they are unsuccessful or their share prices have gone down, so they are a smaller part of our portfolio anyway, the liquidation doesn’t have the same impact on the portfolio. The combination of both those factors means that actually the liquidity issue, in our view, is probably slightly overstated as a worry.
That hasn’t stopped a general trend for small-cap managers to gravitate towards mid-caps, though. I guess you think it’s likely that trend will reverse?
Certainly over the past 25 years the industry has had redemptions at the smaller end. Most small-cap funds have got smaller and most small-cap fund managers have moved into mid-caps. Pretty much for 25 years of my 30 years career we’ve had a period where it’s like lobster pots - you can get in but you can’t get out, and that’s something I had to get used to.
But that was then, and my view going forward is that the lobster pots will turn around and you’ll be able to get out any time you like. We haven’t got there yet but that’s where we’re going and that’s why I think the future is small. It will be very exciting because illiquidity can suddenly mean a whole lot of different things.
There have been some high profile company disasters on AIM, which has irritated some investors. Is this just a natural hazard when it comes to navigating the market?
Well, I often say isn’t it awful what’s happened to Glencore. The amount of money that people have lost in Glencore pales into insignificance against the whole value of the AIM market. So let’s put this in context, you can lose money in fully listed companies as well as AIM companies. For all the negatives like Quindell, it did go up like a rocket, and it came down like a rocket. But broadly, certainly when it was well known, you could buy or sell a million pounds worth of stock every day. You might not have liked the price, but the market was open.
Generally, the AIM market isn’t perfect and it has lots of negatives about it, but it’s better than almost anything else out there at the moment. If we’re lucky enough to continue to get the vibrancy of smallness and capital allocations to smallness it could become a dominant market in the world. It’s not just about UK quoted companies, we’re seeing US companies listing on AIM, European stocks and there are a number of Israeli stocks of course. So it’s gradually becoming a more international market. That again, is good because we’ve got some fantastic tiny ones under the bonnet but we also have some international companies where valuations are wonderful. That means we can diversify and participate in their success as well.
What are the key features of your investing process - what are you looking for in a company?
As a fund manager, you can’t always rely on share prices moving your way, so you have got to find a way of delivering an attractive return for your clients. If the world isn’t going to help you much, you have to find companies that can help themselves, so it’s about fundamentals. It’s not just about those that are generating cash now or paying dividends now, but certainly over a three or five year period we’ve got to find companies which are going to be in a strong position to generate cash and pay dividends. Some companies are doing that straight away. But we are also investing in companies where it’s a bit uncertain for sure when they’re going to do it. A lot can happen in three years so you can’t really look that far ahead. But if you can invest in companies that have a good chance of being in a very cash generative position with productivity improvements coming through, which then drive up cash generation in the business, then that is really what we’re about.
A lot of those are companies are profitable, out of fashion, too small or they’ve upset people in the past by making a mistaken acquisition. But they are also companies which are ambitious or moving into new areas or doubling their sales force or bringing in a new product.
There are some companies which just go up vertically and people get awfully excited about them. But there are a lot more companies that go up a lot more steadily, where the chances of losing your shirt are pretty light and the upside can be very substantial.
Can you give me an example of a stock where that investing approach has worked well for you?
There have been plenty of them. The truth is that often they go up, the valuation moves up and we take some profits, and they carry on going up for much longer than we think. Some that I’ve made good money on, others have made good money on too, because they’ve bought them from me.
There have been companies like Finsbury Food, which we were buying at 23p-25p. It had upset people in the past by becoming too geared and because of the debt its service levels came off a bit. They were having to run the business for cash rather than customers. Plus, cakes and things sounds like a bit of a dull sector. When we first got involved the debt was coming down but most particularly, they could make productivity improvements with a cash payback of between nine and 18 months. But they were constrained on making those capital investments because of the balance sheet, so we suggested that they do a Rights Issue. The share price was on the floor and the valuation was low in absolute terms. But the point was that they could put the cash in for productivity improvements that on average had an 18 month cash payback. So you put in £5-10 million and within a year and a half you have £5-10 million on the balance sheet. Now that is seriously good.
It’s a terrific company, the top line is growing nicely, they are still getting cash paybacks and they’re still investing hard. They’ve started paying dividends and the share price has moved on, but it’s still cheap. The underlying growth rate isn’t that high but the risk/reward ratio for shareholders is beautiful. Those are the really successful ones.
Presumably there have been a few disappointments, too?
Well, I’ve lost my money 100% in certain places - not many times, but a few times. I suppose the biggest one in recent years was Independent Insurance. To be fair it was a complex balance sheet and we didn’t anticipate all the risks correctly so we lost money on that. More recently there was Silverdell, and we lost money on that too. It happens occasionally and there’s always a story.
Where do you think individual investors get things wrong, and are you wary of falling into the same traps?
I think we all love stories and sometimes it’s such a good story that people get a bit over-anchored to it and they lose sight of the valuation. I think that happens quite a bit. There is a lot of fuss about Quindell or whatever, and it’s all very exciting and the more the share price goes up the more you think it must be right. But it may be that the risks are going up without the fundamentals. So you have got to separate the share price from the underlying fundamentals.
We’ve got such a broad spread of portfolios and the opportunity set is so wide that if a share price rises strongly we don’t need to stay for the finishing post. We can take our profits and allocate elsewhere. So it’s not that we’re cleverer than anyone else it’s just that we’ve got a wider number of new ideas coming through all the time - so we can rotate our capital around a bit.
During your time at Miton you’ve established a stable of funds and trusts. What has been your approach to doing that?
What we’ve done at Miton over the past three-to-five years is put together strategies which aren’t just better than the competition but to position the portfolios so they are very differentiated. It’s not there to outperform the competition just a little bit, although we love to do that. More particularly we will zig and zag at different times. It’s that differential, and the fact that we can make decent money on a wider opportunity, and not always when the markets happen to soar or collapse.
We’ve set up single strategy funds over the last five years which are very different. Take the Miton UK Multi Cap Income fund, which was the first fund out there which said that you can get income from large-caps, you can get it from mid-caps, you can actually get it from small-caps and even AIM stocks. Around 35% of the fund is invested in AIM stocks. People don’t think of AIM as an income area but there are some decent income stocks there. They’re not being well covered and the shares are often not quite so accurately priced so there’s a bit more added value from stock selection. That’s been so exciting for us. It’s a crowded market, but as a house we’ve got a slightly differentiated position, and we’ve got the opportunity of growing larger in spite of a market that isn’t growing much.
From a broader market perspective, you’ve been holding a FTSE 100 Put Option for the past few years, which effectively insures a proportion of your funds if the market falls heavily. What has been your thinking behind that?
The problem with Put Options is that it’s not quite like your house insurance in that you can only claim once. The Put Option is at 6,000 points and the market wobbled and went down to 5,600 or thereabouts, so we could have claimed, we could have made 2% clear for our clients. But it’s not really about that, it’s a longer duration thing. We don’t know how bad it’s going to get, we don’t know when it’s going to get bad. We know that the Middle East could turn sour or China might go into recession, there are lots of things out there. So it’s not that we know that things are awful and that there’s going to be a terrible calamity in the stock market but we do know that we can buy insurance at half price.
It’s a bit noisy out there, and you saw that particularly in January and February when the market was down over 11% at one stage. We could have claimed but we didn’t. It only covers a third of the portfolio and it costs our clients 0.06% per month, so if we don’t add any value at all, it’ll add up to perhaps 0.8-0.9% per year of underperformance. So it’s not free. But if things do go wrong, at least we can do something about it. We’ll be able to cash it in to buy more stocks. We’ll be able to take advantage of the extremes, which come occasionally, to add more value.
Finally, you’re probably one of the best informed investors in smaller UK-quoted companies. Are you still confident that the future for these firms, and those that invest in them, is very exciting?
It’s going to happen, which is why I wrote The Future is Small. It’s partly to help people to start looking ahead and preparing themselves. It’s to help clients like wealth managers, IFAs and pension schemes get conviction about what’s going on. This absolutely helps us and the companies themselves. It reduces the cost of capital for them because the valuations go up, which means they can issue fewer shares for the same acquisition. The cost of investing goes down and the productivity improvements are better still as a result of that. Net, net, net it’s a virtuous spiral.
As a sector, the more small companies outperform, the more people will come in, and the more people want to come in, the more illiquidity will drive outperformance. My view is that it all got a bit too skewed to globalisation and bigness, and the pendulum is now swinging back to the middle. It’s nothing like convention, but the trend is beginning to go our way. It will be transformational for growth and share prices and productivity, and that’s going to be great news for all of us.
Gervais, thank you very much for your time.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
13 comments
Sorry Ben, I got a bit over excited and gave you a thumbs down by mistake. Really good article, thanks.
Chris
Hi
Gervais replied to my email this morning which is impressive. His compliance team has not yet approved him posting on forums like this so I said I would not post his reply but if anybody is interested they can reach me on
m at purpleski.com
Michael
Sunday morning reply. Very impressive indeed.
I'd worry about his home life though.
Hi
To hedge, I've bumped up my cash to 30%ish of my portfolio. If I have the nerve, I'll try to re-invest this around the week of the EU vote with companies who trade mostly within the UK or the Rest of the World (excl. EU)....on the other hand I might bottle it, forgo some possible profit, and see what the market says and the aftermath :0)
When we have visibility of the result however I think there may be a bull run, what-ever happens, just because the uncertainty has gone.
Good luck...
Like Acounsell I am interested in protecting the down side of my portfolio with the put option that Gervais mentions. This seems eminently sensible in the current market and very cheap. Can anybody shed any light on how a PI might do this?
Thank you.
Michael
If open an account with IG Group you can put a short on different indexes like the FT100 or FT250, you put on £x for each point, so if you put on £10 a point, if the FT100 falls 80 points you get £800, you can put on a stop loss as well, think you can only keep it for max of 3 months? Or you can buy a short like db X-trackers FTSE 100 Short Daily UCITS ETF (XUKS), you buy it under shares in HL account, can be in ISA, there are a few others as well.
I think the IG option is better. Best to open an account soon if you want to do it, in first few weeks they restrict how much you can put on, but £ 500 in your account you can place £10 on the FTSE 100, less on the FTSE 250 because its higher points, so probably £4. The FTSE 250 is probably better than the FTSE 100. Think they do the FTSE All Share as well, spread maybe wider though. Also overseas ones to. China might be a good one.
@herbie47. Thank you for this. I had heard of some of these. From you say though it sounds as though if the FTSE say moves the wrong way then you are open to lose more than just your initial purchase.
Gervais Williams seems to talk more in terms of something akin to house insurance. I pay £1 a £1,000 for my fire insurance and at the end of the year my £100,000 house has not burnt down and I have lost £100. I then insure again and so on.
I have writen to him and asked! He seems like the sort of guy who might reply.
I think he is referring to a spread option which is the IG one. You put on say £10 a point, if FT100 falls say 1,000 points which is about 16% you close it you will get £10,000. If it goes up say 500 points then yes you can lose £5,000 but as I said you can put on stop loss, I think the most on mine I could have lost was £500. But then if the market goes up then presume your portfolio goes up as well? Robbie Burns does the this type of spread.
The db bank is like a fund if the market falls it goes up but to cover your portfolio you are going to have to put in a lot of money in although there are leveraged products.
I suspect he's using regular options, probably these:
https://www.theice.com/products/38716770/FTSE-100-INDEX-OPTION
Daily prices are in the "end of day report" (product "ESX").
A 1% premium to the end of the year would buy you a strike price of about 4500 it seems (if the index is lower on the expiration date, it pays the difference between 4500 and the price, if it is lower, you lose your premium).
Thanks cig. Interesting and seems simple. Hope I can find time to investigate.
A FTSE 100 put option was mentioned as insurance by Gervais. I am concerned about impact of potential Brexit on my UK portfolio in short term so is it possible for individual investor to buy put option on UK all share index or does it have to be more specific (I.e FTSE 100) . Also what are the mechanics of doing it - there doesn't seem to be any information in public domain. Traded option prices used to be published in the financial press but this does not seem to happen any more.
Interesting and worthwhile article. In respect to Howard's question I think we can safely say that Brexit would have less impact on Gervais William's universe of companies because they tend to be smaller and more domestically focused, although there are exceptions. Most fund managers, such as Neil Woodford, seem to think that UK companies will continue to prosper regardless of which way the vote goes. With respect to the interview, my only slight concern was Mr. Williams' implying that what he was doing was socially useful. While this may be true I hope social usefulness does not start influencing the way he invests otherwise he might end up like Neil Woodford with crazy investments in blue sky biotech companies which are impossible to analyse! One interesting point was the explanation of how difficult it can be for a fund to make or sell investments in small copanies because of liquidity issues. This puts small investors such as us at a significant advantage. Nevertheless I have quite a bit invested in Mr. Williams' Diverse Income Trust which has done well so I hope his success continues.
Ben
Interesting interview, thanks.
Given Gervais Williams's conviction with AIM and small caps generally, I was surprised you did not ask his views about what affects pre-Brexit and the two post-Brexit options might have in this universe. Did you by chance cover this topic at all?
Regards
Howard