HCA Healthcare (HCA): Strong fundamentals and cheap stock price signal an uptrend.
Summary:
- Do the company fundamentals support steady growth?
- Does a highly levered financial structure make the HCA Healthcare stock risky?
- Will HCA Healthcare’s strategic investments and innovations outplay the competition?
The Company:
HCA Healthcare, Inc. (HCA) is one of the leading health care services companies in the United States. It operates hospitals in both USA and UK.
The company has been on the forefront of expansion in the hospital sector. The company CEO Sam Hazen said. “The environment is presenting opportunities for us to make sizable acquisitions. I think some of these are once-in-a-lifetime type opportunities and it’s important for the company to consider them, I think very carefully.” (Reference www.bizjournals.com).
The company fundamentals are very strong and expansion into new markets adds to the stock’s bullish sentiment.
Reason for Growth
The three core factors that will propel HCA Healthcare’s growth are:
- Strong cash inflows and sound fundamentals
- Huge market share compared to its competitors
- Investments in care delivery points such as urgent care centers, emergency rooms and outpatient centers.
We will deep dive into these three factors to see how they will impact the company and its stock.
Strong Cash Flows and Sound Fundamentals
HCA Healthcare’s primary sources of cash are cash flow from operating activities, issuance of debt and equity securities and dispositions of hospitals and other centers. The important thing to note here is that the cash flow from operations is a huge $6.76 billion, which is an increase of $1.335 billion or 25% over the previous year. This cash flow lets HCA Healthcare:
- Re-pay the principal and interest on its debt, thus making HCA Healthcare a less levered company.
- Be cash sufficient during tough economic conditions.
- Make strategic acquisitions and expand into new geographies.
- Pay dividends.
Due to the strong cash flow, HCA Healthcare is able to grow at a tremendous pace. Its 2018 revenue were up 7% on a consolidated basis due to volume growth in same facility admissions, inpatient/outpatient surgical centers and emergency room visits. The increase in volume will continue to grow since the company has been expanding into new geographies with increasing number of people needing medical services.
HCA Healthcare raised its 2019 revenue guidance from $50.5 to $51.5 billion (Chart 1) and raised the EPS guidance from $9.80 to $10.40 per diluted share, which are positive factors contributing to the stock’s rise.
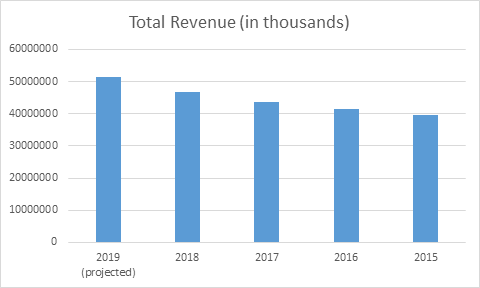
Chart 1: Revenue growth over the years (Data Source: Yahoo Finance)
Talking about valuation, HCA Healthcare trades at a P/E ratio of 11.83, which is significantly less than the healthcare sector average of 20.6, making the HCA stock a smart pick for value investors.

Chart 2: PE Ratio (Data Source: https://ycharts.com/companies/...)
Competitive Analysis
Competitors: For the purposes of competitive analysis, the following three companies are considered HCA Healthcare’s competitors.
- Community Health Systems, Inc. (CYH)
- DaVita Inc. (DVA)
- Select Medical Holdings Corporation (SEM)
Revenue and Net Income: HCA Healthcare’s strong dominance in the healthcare hospital market is visible from their yearly Revenue and Net Income, which are significantly higher than that of the competitors. Both the revenue and Net income are showing steady growth over the years.
While revenue and net income puts HCA Healthcare in a strong position, one may argue that HCA Healthcare is a highly levered company compared to its competitors. High debt may impact HCA Healthcare’s ability to adjust to changing market conditions and place them at a competitively disadvantage compared to competitors who are less highly levered. Agreed, that HCA Healthcare is a highly levered company but HCA Healthcare wouldn’t have been a leading hospital chain had it not have pursued the strategic acquisitions that are adding to its revenue growth and cash flow.
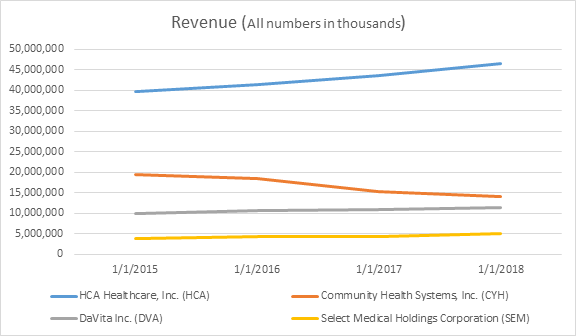
Chart 3: Revenue (Data Source: Yahoo Finance)
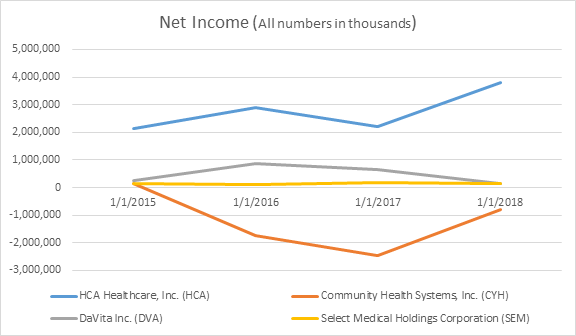
Chart 4: Net Income (Data Source: Yahoo Finance)
Operating Environment:
- In recent years, the number of freestanding specialty hospitals, emergency centers, urgent care and surgery centers have increased significantly making the hospital’s operating environment highly competitive. In some cases, the competing hospitals may gain advantage over HCA Healthcare hospitals if they are owned by tax supported government agencies, non-profit entities or are exempt from sales, property and income taxes. This scenario applies to all for profit hospitals and is not specific to HCA Healthcare, making this issue healthcare sector specific and not HCA Healthcare stock specific. Moreover, HCA Healthcare has always been operating in such an environment and has delivered impressive earnings and cash flows.
- Another major competitive factor is a hospital’s ability to negotiate service contracts with group purchasers of health care services. The consolidations in payer industry has increased the payer’s bargaining power over fee structures. While payers may have an upper hand in dealing with small to mid-size hospital networks, which are HCA’s competitors, HCA’s huge size provides it an upper hand in contract negotiations.
Investments and Innovations
HCA Healthcare (HCA) has put in a great effort to reduce the cost of expensive in-patient admissions and hospital stays. The company has in excess of $3.5 billion of capital projects in the pipeline. As mentioned in HCA Healthcare’s annual report, this capital projects pipeline will strengthen the company’s existing healthcare services and create additional inpatient and outpatient capacity within their local healthcare systems. The centers are technologically inter-connected which helps the physicians, nurses, lab specialists etc. across its numerous centers make data driven decisions.
Due to the interconnected network of in-patient, out-patient, urgent care centers etc. HCA Healthcare (HCA) can efficiently shift a patient from expensive in-patient centers to low cost out-patient centers or long term care facilities. HCA Healthcare (HCA)’s commitment to provide quality healthcare at the out-patient center reduces the hospital’s re-admission rate. Center of Medicare and Medicaid Services (CMS) uses excess readmission ratios (ERR) to measure hospital’s performance and penalize hospitals for excess re-admissions under the 21st Century Cures Act.
HCA Healthcare has shown a strong commitment to innovations. In a latest news, HCA Healthcare’s clinical experts, data scientists and programmers developed an Algorithm Driven Technology to Detect Sepsis Early and save lives. With innovations in the Electronic Health Record (EHR) segment, combined with HCA Healthcare’s vast network of healthcare centers, a data exchange network has started to form which results in an in-patient’s health record instantly available to outpatient centers and long term care facilities. The company’s strong position against its competitors, robust information technology infrastructure and investment in innovations are what will move the needle on its stock price.
Challenges with Downside Risk:
Book value to equity: HCA Healthcare’s book value to equity is $-12.43 as of March 2019. A negative book value to equity indicates that the company’s total liabilities are much more than the total assets. Negative book value to equity will impact HCA Healthcare’s credit rating and make its debts more expensive. HCA Healthcare’s highly levered balance sheet increases the company’s vulnerability to changing market conditions and downturns. While debt makes HCA Healthcare highly levered, the strategic expansions increase the HCA Healthcare’s growth opportunities. The company is expecting its patient volume to increase with its expansion to new geographies with growing population; expansion and growth wouldn’t be possible without debt. The important factor to note hear is that HCA Healthcare’s expansion supports it with a very strong earnings and cash flow.
Some of the 2020 presidential nominees are proposing ‘Medicare for All’. The HCA Healthcare stock might be under pressure if legislation pass the ‘Medicare for All’ after the 2020 election. Reason being the amount that HCA Healthcare receives from the government for the Medicare plan is significantly discounted. ‘Medicare for All’ will put an enormous pressure on HCA Healthcare’s margins. However, the 2020 elections, changing the legislation etc. are not happening anytime soon. Healthcare sector policy shift usually takes a lot of deliberations and time to react and is not an immediate threat to the company stock.
Technical Analysis
Double Bottom Behavior
The HCA Healthcare (HCA) stock exhibits a ‘Double Bottom’ behavior. At present, the stock is signaling an upward trend.
- Referencing the chart shown below, the first bottom takes the stock price to $116.13.
- The second bottom, which is 3.55% lower than the first bottom, drops the stock price to $112.01. Having second bottom a little lower than the first bottom removes the weak investors from the mix, helping the stock advance.
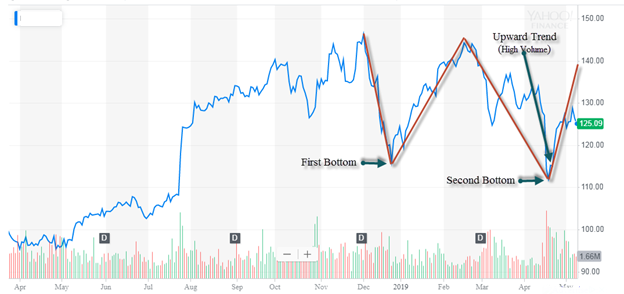
Chart 5: Double Bottom Behavior (Analysis: Author; Chart Data Source: Yahoo Finance)
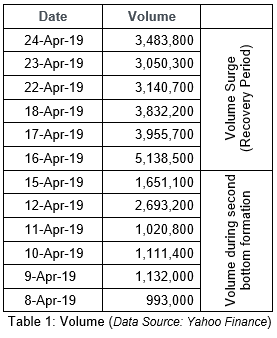
- The second bottom is a major support level: The falling prices have created a volume surge (Table 1: 04/16/2019 volume is 5,138,500) the day before the stock hits the second bottom indicating a trend shift and formation of an upward trajectory. The recovery period is further accompanied by more than double increase in volume.
- The strong uptrend in the last phase of the double bottom behavior signals a strong ‘BUY’ at current levels.
Conclusion: Evidenced from the analyses above, the HCA Healthcare stock is set to grow in the short and long term. The company has strong fundamentals, revenue and cash flows. Its P/E ratio of 11.83 is less than the healthcare sector average of 20.6. Moreover, looking forward, the company increased its 2019 guidance and its stock is showing a strong uptrend emerging from a double bottom pattern.
HCA Healthcare stock is a strong BUY at current levels.
Disclosure:
- I have no positions in the stocks mentioned in this article with no plans to initiate any positions within the next 72 hours. This article expresses my opinion and I am not receiving any compensation for it.
- This material has been prepared for informational purposes only. You must consult your financial advisor before making any investments or securities transaction.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?