How to use sector diversification to manage risk

I’ve interviewed some well known investors and fund managers this year, and they’ve all divulged interesting investment approaches. Each has had strong personal views on investment styles, ranging from small-cap growth to large cap value. But one area where the waters are muddy is on the issue of diversification.
Portfolio diversification is a subject that divides opinion, and it’s one that most investors approach by thinking in terms of numbers. It ends up being a balancing act between offsetting the risk of single failures against the costs and effort of managing dozens of positions. On this point, even the pros have differing views. Small-cap fund manager Giles Hargreave is content with over 200 hundred holdings, while the likes of Schroders’ Nick Kirrage is more than happy with 40, and even less.
But there’s more to diversification than looking for safety in numbers. Being aware of how resilient a company is to the broader economy is important in managing exposure and smoothing returns over time.
Understanding sector sensitivity
All stock market data services - like Thomson Reuters, which is used by Stockopedia - categorise companies based on the sector they fall into. At the top level, there are three super-sectors: Cyclicals, Defensives and Sensitives, and then 10 sectors that are divided between them.
| Cyclicals | Defensives | Sensitives |
| Basic Materials | Healthcare | Industrials |
| Consumer Cyclicals | Consumer Defensives | Energy |
| Financials | Utilities | Telecoms |
| Technology |
Broadly speaking, Cyclical sectors are those most sensitive to macro trends and the general health of the economy and consumer sentiment. Among them are mining stocks, high street retailers and banks. Defensives, on the other hand, are seen to be less reliant on the economy because they sell goods that we buy in good times and bad. They include pharma companies and tobacco and utility groups. In between are the Sensitives, which move with the economy but to a lesser extent than Cyclicals.
One distinction between Cyclicals and Defensives can be seen in something called Beta. Beta is a measure of the sensitivity of a company’s share price to the movement of the market (usually over the past five years). If a stock’s price tends to rise more than the market on up-days and fall more than the market on down days, it will have a Beta greater than 1. But if it isn’t as sensitive to market movements, rising less and falling less than the market, then it will have a Beta of less than 1. Very generally, Defensive stocks have lower Betas than Cyclicals because they are less sensitive to market volatility.
Overlooking sector diversification could have been costly over the past six years. Since the financial crisis, Defensives have generally outperformed Cyclicals because investors plumped for the perceived safe havens of companies that were resilient to unsettled economic conditions. It’s quite easy to see this in action when you look at the staggering price gains in Defensives like British American Tobacco, Unilever (in the chart below) and Severn Trent.
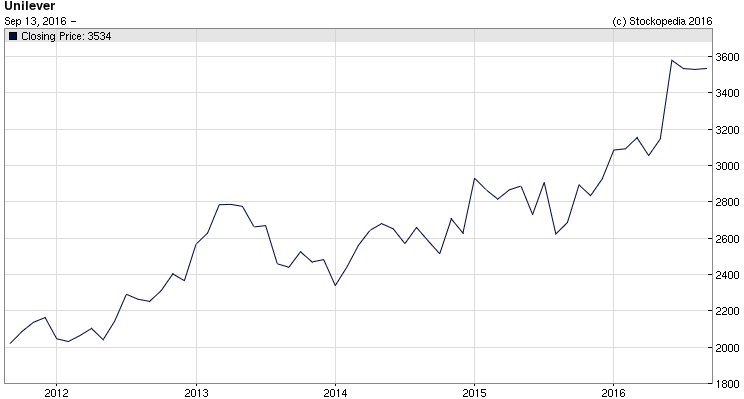
More recently, the uncertainty caused by the EU referendum was a classic example of how Cyclicals and Defensives perform differently when the mood of the market changes. Stocks with strong ties to the UK economy, particularly housebuilders and retailers were marked down, while more defensive plays in pharmaceuticals and consumer goods shot up.
Opinions on these trends vary enormously. Terry Smith, the high profile fund manager at Fundsmith, insists that these defensive, high quality firms remain attractive regardless of price. He says that the high rates of return on capital generated by what have become known as “bond proxies” can compensate for seemingly high valuations.
By contrast, Andrew Lapthorne, an analyst at Societe Generale, strikes a more bearish tone. In his research, he points out that global corporate profits actually peaked in mid-2014 and that markets should be declining as a result. However, he says economic stimulus by central banks is stopping that from happening and, as a result, defensive stocks may not be quite as defensive as some investors might think - they could even crash.
Taking action on diversification
Without knowing the future, these differing views reinforce the importance of diversifying between sectors. That way, an “all weather” portfolio should always have some exposure to sectors that are on the up. This is exactly what Ed did when it came to constructing his ‘Naps’ portfolio - and the approach paid off very well.
Stockopedia members wanting an instant fix on their sector diversification can use the Allocation tab in Folios to see where the highest exposures are.
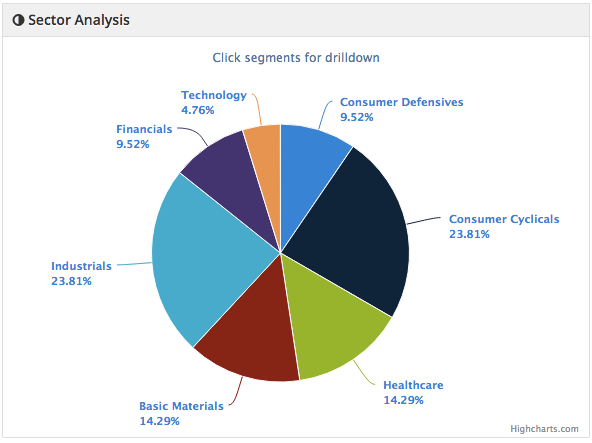
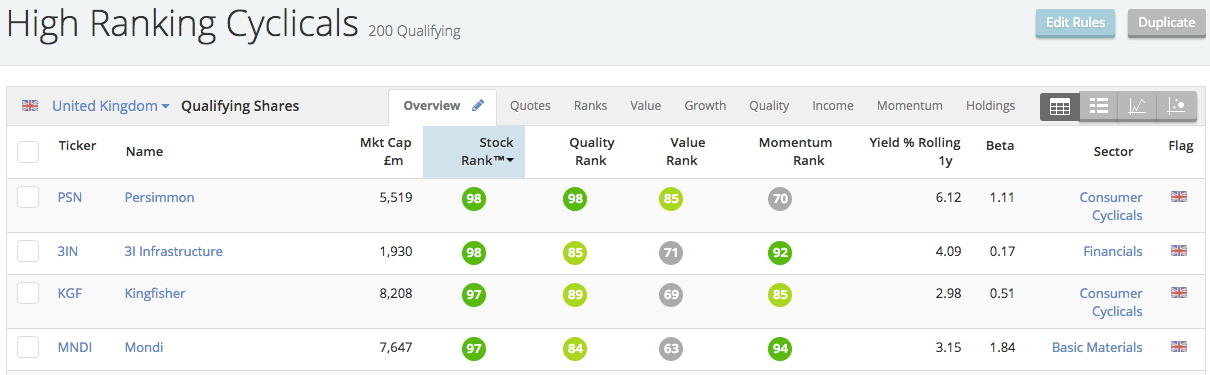
To help explore the options for getting broader sector diversification, I’ve set two basic screens using the StockRanks as a guide to finding where the most appealing Quality, Value and Momentum can currently be found in both Cyclicals and Defensives. (Click here for the Cyclicals screen and here for the Defensives screen). Don’t forget, you can also get an overview of the 10 main economic sectors using the Directory.
It’s easy to think of portfolio diversification as an exercise in owning a certain number of stocks. But as market trends over the last six years have shown, spreading positions across different sectors can be equally important. An ‘all weather” portfolio may well stand a better chance of withstanding swings in market sentiment and help balance exposure to sectors that fly in boom times and those that are protected during uncertainty.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Ben, why are Charles Taylor (LON:CTR) in the Cyclicals?
Ben, thanks for this highly informative article.
Would it be too much of an oversimplification to say that the above "Sensitives" are of medium cyclicity?
And how about a follow up piece which:
1) Helps us to know which stage of the cycle we are in.
2) Identifies which sectors may be viewed as Buy / Hold / Sell for each of the different stages of the economic cycle.
Paul.