International Stock in Focus: I add designer trainers, oil and pills to the folio

After last month’s round of sales, I’m on the hunt for new international stocks this month.
My international SIF portfolio has been a pretty poor performer so far and has not matched the success of my UK SIF. But I haven’t given up hope just yet.
Just 30 stocks in Stockopedia’s international universe qualified for my international SIF screen this week. Luckily, an unusually high proportion of these seem to fit in the folio without duplicating existing holdings.
As a result, I have five new stocks to report this month, which may be a record.
Portfolio performance
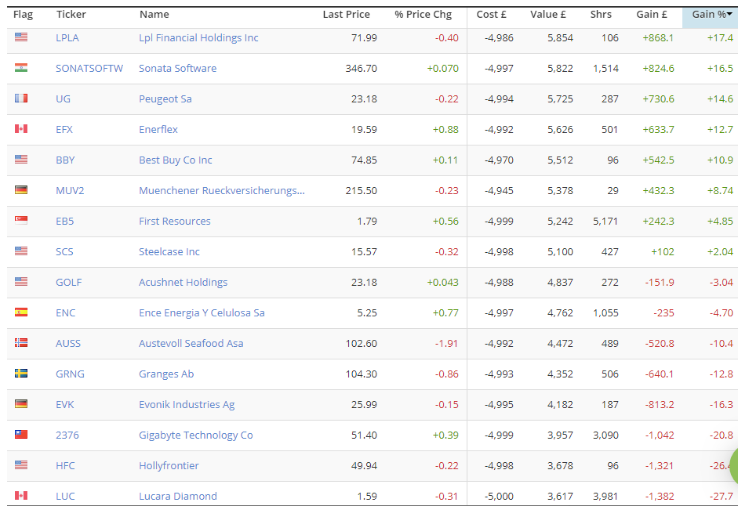
I run this virtual portfolio using Stockopedia’s Folio service. Unfortunately it’s not currently possible to share private folios, so here’s a snapshot showing how the current stocks are performing:
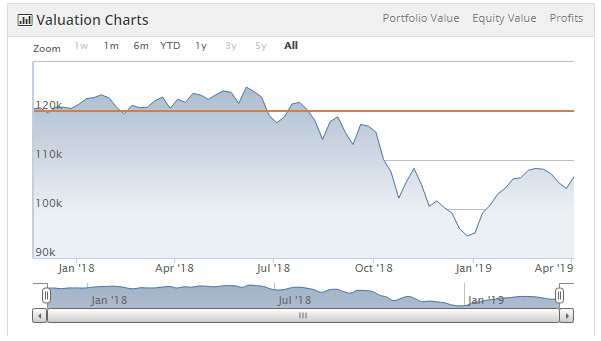
As you can see, the portfolio has regained some of the ground it lost last year, but is still running at an overall loss after 17 months:
New selections
I’m hoping that the improving performance trend will continue. I would like to break even by the time the folio reaches its second birthday in November. We will see.
In the meantime, this month’s additions should see the portfolio (almost) reach its full complement of 24 stocks.
Foot Locker Inc (NYQ:FL)
This £5.5bn sports and leisure wear retailer appears to cater for the same sort of athleisure market as JD Sports and perhaps Sports Direct.
Around 70% of sales come from the USA, with the remainder coming from international markets. Although the company does have a UK website, Canada, Italy, France and Germany were listed as the only significant international markets in the firm’s 2018 results.
All the main measures of quality and profitability look good for the shares:
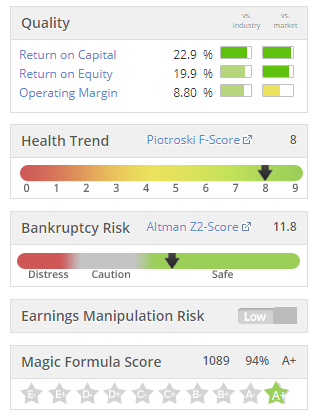
I’m especially pleased to see such a high Magic Formula Score, as this is a system I rate highly.
With a StockRank of 99, net cash and a forecast P/E of 12, I’m happy to add these shares to the international SIF.
Domtar (NYQ:UFS)
This is a US pulp and paper group that operates in the pulp, paper and personal hygiene sectors. Example products include paper for office and specialty use, nappies and adult incontinence products, and pulp for customers such as tissue manufacturers.
Domtar is not quite as profitable as Foot Locker, but otherwise sports a very impressive set of quality and fundamental health scores:
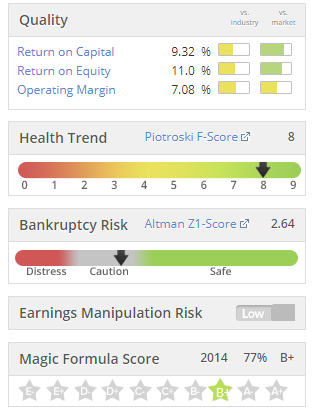
Although some of the firm’s products may have some cyclical exposure, Domtar’s tilt towards healthcare suggests to me that it’s performance should be fairly defensive.
The stock seems affordable on 9 times forecast earnings, with a dividend yield of 3.5% - unusually high for a US stock. History suggests that free cash flow generation is good, comfortably covering dividend payouts:
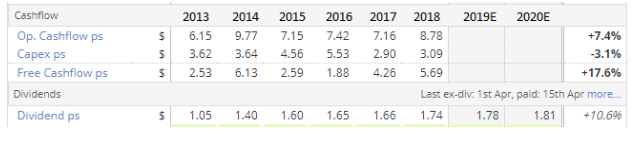
As with Foot Locker, I’m quite comfortable with this stock.
Deutz AG (ETR:DEZ)
Sales of diesel engines in cars have fallen dramatically over the last couple of years. This has caused significant disruption to the market, as reported by SIF folio holding Lookers among others.
But for applications such as heavy plant and agricultural machinery, there’s still no other choice in most cases. That’s where my new European stock fits in.
German firm Deutz makes large diesel engines for applications including agricultural machinery, boats and construction plant. Although diesel accounts for the majority of its business, the group is starting to offer electric and hybrid powertrains, such as the Torqueedo electric drive system for boats.
The Stockopedia stats suggest that the firm’s reported profits have been inconsistent in recent years, despite strong sales growth:
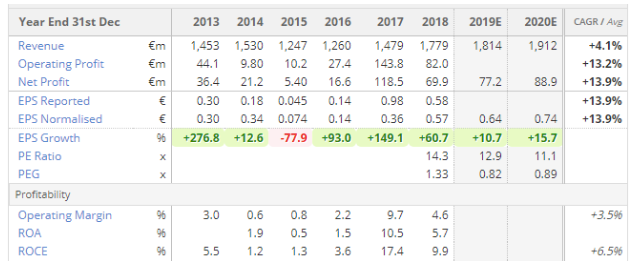
However, normalised earnings per share have shown more consistent progression and this is expected to continue this year. I haven’t looked into the possible reasons for this, such as exceptional costs, one-off losses or acquisitions. But for anyone considering a real-money investment this would probably be prudent.
For my virtual purposes, I can see that Deutz appears to have solid fundamentals and a positive trend of increasing earnings forecasts:
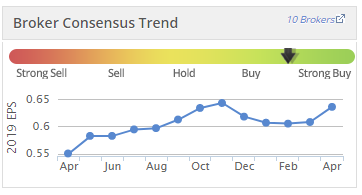
The shares look affordable, on a rolling forecast P/E of 12.4 and with a well-covered 2.2% yield. Adding Deutz to the International SIF means I’m now just one European stock short of my full quota for this region.
Best World International (SGX:CGN)
This oddly-named Singapore-listed firm sells nutritional supplements and beauty products. I know absolutely nothing about the credibility of its products, but you can find out more about the firm’s main brands here.
What I can tell you is that Best World was founded in 1990 and has a market cap of £635m. This hefty valuation may be explained by the fact it generated a return on capital employed of 54% on sales of SGD266m (£150m) in 2018. This suggests the firm’s brands may have a certain value.
Quality scores are very high, as you’d expect:
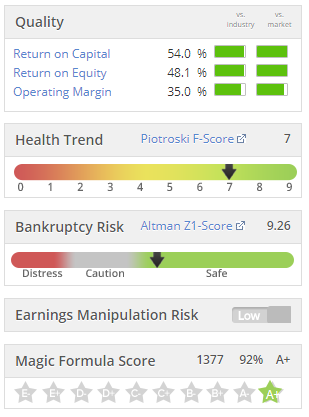
Best World also qualifies for nine Stockopedia Guru Screens, including the Jim Slater ZULU and Naked Trader style screens. These have delivered annualised returns on UK stocks of 21% and 17% respectively, since inception.
If I was buying this stock with real cash, I’d want to investigate the rapid growth seen over the last few years in more detail. I might also want to look understand why earnings are expected to fall next year:
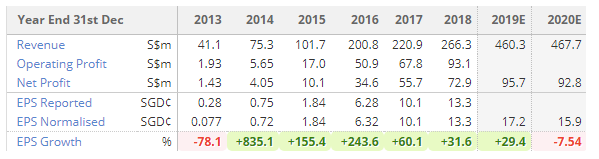
However, Best World International passes all of my screening tests and appears problem free at the moment. So it has joined the International SIF this month.
Woodside Petroleum (ASX:WPL)
Woodside Petroleum is a £17bn Australian oil and gas producer. A lot of the firm’s interests are in liquefied natural gas (LNG), such as the giant Pluto LNG project in western Australia.
The story here is fairly standard for this sector, in my opinion. Since the oil market started to recover in 2016, the firm has cut net debt by 50% to $2.3bn and reported strong profit growth. This has been aided by new projects coming onstream.
Margins are high and return on capital appears to be moving towards double digits:
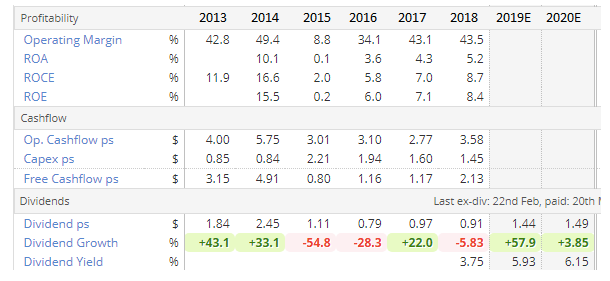
Based on free cash flow over the last three years, I’d feel confident that dividend forecasts for 2019 and 2020 are likely to be affordable. This gives the stock an attractive c.6% forecast yield.
I own shares in another UK-listed oil major, but if I invested in Australian stocks myself, Woodside would probably be my pick from this sector. I have no qualms adding it to the International SIF.
Next week…
That’s all for this week. Next week I hope to be able to add a new UK stock to my SIF Fantasy Fund. I’ll also be gearing up for this UK portfolio’s third annual review.
As always, any comments on overseas investing would be very welcome. This is a team sport and I know that many UK investors (including me) have limited experience in this area.
Disclosure: Roland owns shares of Lookers.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Thanks Roland.