IPO watch - Calnex (LON:CLX)

You might think 2020 is not the year to float your company, but the truth is there are a few recent IPOs on the market. In fact by my counting, there have been close to 20 this year. That’s lower than last year but it’s still plenty of new entrants.
There is a wariness around IPOs - why buy something being sold to you by investment bankers when they have much more information than you do? But there are always exceptions to the rule, and every once in a while this lack of information can result in a great opportunity for the diligent investor.
Here are some of the more notable IPOs this year in order of listing date:
Name | Sector | IPO date | Market Cap | IPO Price | Share Price | % Performance |
Consumer Cyclicals | 07/01/2020 | £38.16m | 30p | 22p | -26.7% | |
Industrials | 12/02/2020 | £1,150m | 240p | 208.6p | -13.1% | |
Healthcare | 27/02/2020 | £268m | 195p | 265p | +35.9% | |
Industrials | 06/03/2020 | £243m | 80p | 101.75p | +27.2% | |
Industrials | 23/03/2020 | £150.7m | 0.68p | 0.48p | -29.4% | |
Basic Materials | 31/07/2020 | £82.8m | 45p | 45.45p | +1% | |
Technology | 21/09/2020 | £6,090m | 500p | 670.6p | +34.1% | |
Consumer Cyclicals | 25/09/2020 | £59.2m | 73p | 66.5p | -8.9% | |
Technology | 05/10/20 | £90.6m | 48p | 99.8p | +107.9% |
We covered Inspecs (LON:SPEC) here although it’s safe to say, with everything else going on this year, I haven’t kept up with developments. The group announced a £64m placing on 19 November that will be used to help pay for the £84.7m acquisition of Nuremberg-based eyewear supplier Eschenbach.
That’s a material development for the £268m market cap Inspecs and is probably worth a closer look in itself. But for now I’d like to focus on Calnex Solutions (LON:CLX) - the clear standout from the list above in terms of share price performance.
Calnex (LON:CLX)
Share price: 99.8p
Shares in issue: 87,500,000
Market cap: £87.3m
Calnex makes hardware and software solutions that test the performance of critical telecoms and data network infrastructure. It’s an important function in a rapidly evolving and expanding industry, and Calnex is trusted by many of the world’s leading operators.
We can see revenue, operating profit, and free cash flow are all growing at decent rates (albeit over just a three-year time period):
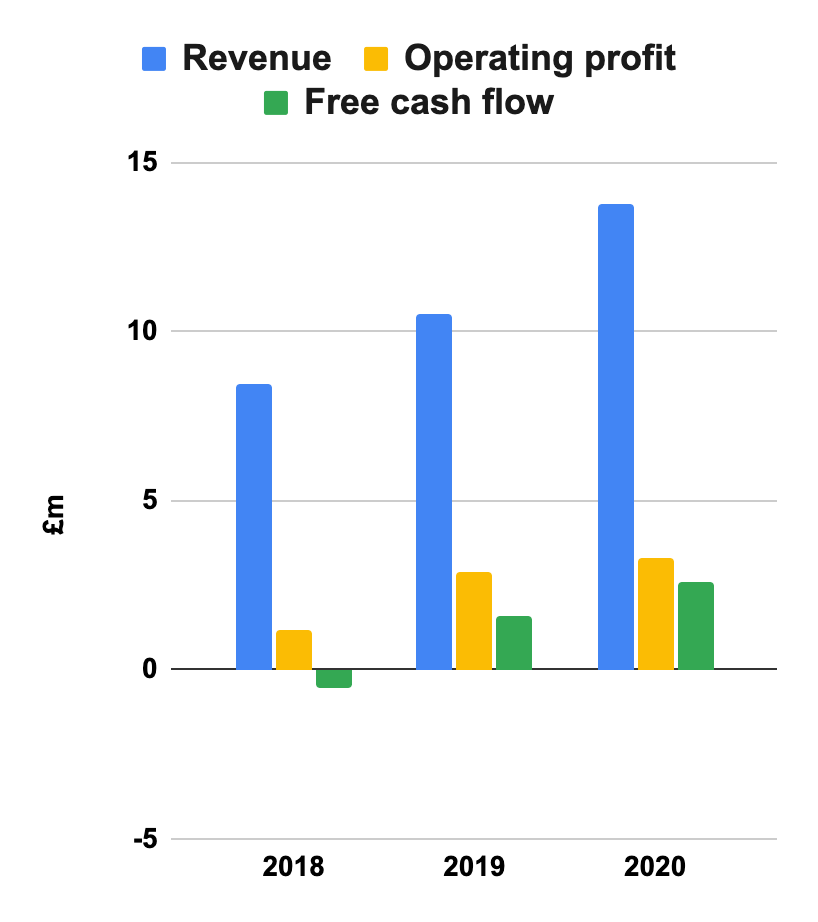
It is profitable, cash generative and entered FY21 with a record order backlog. That sounds promising - my only real question right now is: is it too expensive after a 100% rise, or is there still plenty of upside left on the table?
The group has a Value Rank of just 17 and, while that Rank is often harsh on Technology stocks, there is also a forecast PEG of 3x. That’s way above the 1x or less GARP investors typically look for.
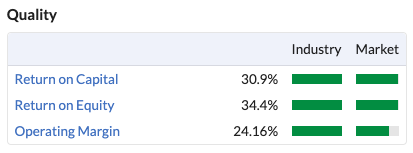
That aside, Calnex shows some promising double-digit Quality metrics:
And the market dynamics look positive (more on these points below).
Calnex has built up a position of trust with global customers and regulators. This provides it with excellent product development visibility and it has developed a useful track record of introducing first to market testing solutions. That dynamic makes Calnex a useful and entrenched player in this market, with commercial testing solutions and a highly relevant R&D pipeline.
That might go some way to explaining the high returns on capital. These testing solutions are also often quite complex, which could enhance pricing power and operating margins.
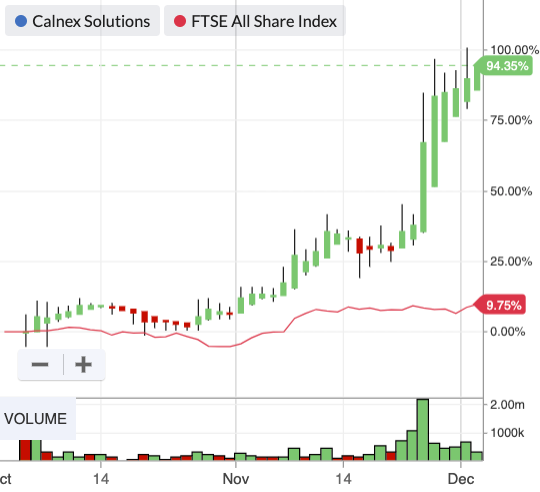
There has certainly been plenty of interest from the investment community so far, with the share price doubling in just a couple of months.
Business structure and history
Calnex is headquartered in Linlithgow, Scotland but it also has a base in Belfast with a development team following the acquisition of JAR Technologies in 2018. A US office manages sales channels, including sales teams in China and India, and supports customers throughout the world.
The group provides its equipment to many of the world’s leading Telecoms Network Operators (including BT, China Mobile and NTT), Equipment Vendors (including Ericsson and Nokia) and Component Manufacturers (including Intel and QualComm). It reports across three geographic regions: Americas, North Asia, and Rest of World (including UK).
There’s a high level of repeat demand in this business. Over the last three years around 80% of revenue has come from returning customers and the group’s ten largest customers (which accounted for 52% of revenue in FY20) have on average a nine-year relationship with the company.
These sales are predominantly derived from Telecoms customers, although Calnex does have some notable non-telecoms customers - namely technology giants like Facebook, Google and IBM.
Calnex also outsources a lot of its manufacturing and distribution to high quality local partners, freeing it up to focus on product development and IP.
Summarising its history briefly:
- Calnex was incorporated in Scotland on 27 March 2006 by CEO and major shareholder, Tommy Cook.
- In 2007 it’s first product, Paragon, was launched to address an emerging need to test the synchronisation of telecoms base stations. These base stations are telecoms towers which manage the radio connections to mobile phones.
- In 2012, the company released its network emulation product, Attero, which is used to impair data traffic to verify that applications and transmission protocols can robustly respond to transmission problems across networks.
- In 2013, Calnex acquired Sentinel, a technology operating as a portable platform for testing synchronisation during maintenance testing post-deployment. This enabled Calnex to offer test solutions from design through to post-deployment maintenance test and debug.
- In March 2018, Calnex acquired JAR Technologies, securing the IP relating to SNE and the company’s development team. SNE is a PC-based network emulation solution offering multi-user capability for low bandwidth applications. In the first year of trading post-acquisition, sales of SNE increased 5-fold as Calnex made use of its global sales channel.
That last point is important to prospective investors. Calnex is entrenched in the telecoms ecosystem. It has also built up a considerable sales network. This strong market position allows it to quickly integrate, scale up and cross-sell value-added testing solutions.
The telecoms market
There are a couple of key drivers of change in the global telecoms market right now. One is the migration of the mobile networks to 5G, a second is the emerging Internet of Things, and a third is the shift to cloud computing. Calnex can drive sustainable revenue growth from each of these trends.
The global market for mobile network testing alone has been estimated by Frost & Sullivan to be around $1.3bn in 2020, and is forecast to grow at a CAGR of 11.5% and exceed $2bn by 2024.
The same consulting firm estimates the global high speed ethernet test equipment market to be around $1.3bn in 2020 and also expects this market to grow to $2bn by 2024.
Key participants in the telecoms industry include:
- Equipment Vendors like Huawei develop hardware and software systems for Network Operators like BT.
- Component Manufacturers such as Intel sell components and sub-assemblies to Equipment Vendors.
- There are also Hyperscale/Large Enterprise entities, such as Facebook, Google and IBM, that build and create their own networks and equipment.
All of the above businesses are customers of Calnex.
Recent trading and outlook
The above certainly sounds intriguing, and the group has already updated the market on trading post-IPO, so let’s take a look at its results so far.
Interim results, 25 November 2020
Highlights:
- Revenue +37% to £7.7m on a gross margin of 78.1%.
- Adjusted PBT +90% to £2.3m,
- Net cash from operations +98% to £2.8m.
Customer order intake was strong, with increased demand across all product ranges and continued high levels of orders from repeat customers, supplemented by the addition of new customers.
Cenkos has upgraded its forecasts on these results, with revenue forecasts for FY21 and FY22 by 10.6% and 12.2% to £15.4m and £16.4m and increased forecast EPS up 24.1% to 4p and 14.3% to 3.9p respectively.
Calnex is investing in both R&D and sales capacity to capture market share, with 5G, the Internet of Things, and cloud computing all driving demand for high value test instrumentation in the years ahead. One reason for the IPO was to enable the group to make more acquisitions, so there’s also growth potential there.
But is a 100p share price just paying too high a price for this promising prospect? A forecast earnings per share figure of 4p suggests a forecast PE ratio of 25x. That’s not overly demanding for a growth stock, but then Cenkos is forecasting a slight drop in earnings per share the following year.
Forecasts aside, the group’s founder, CEO, and major shareholder Tommy Cook will likely be looking to expand. There are certainly some eye-catching growth drivers in this market, and Calnex looks to occupy a privileged position as a trusted tester with good product roadmap visibility.
And alongside these organic drivers, we also have scope for targeted acquisitions now that Calnex is listed. It has proven with JAR Technologies that it can drive value in this way.
Conclusion
There are signs of promise here.
Calnex has a high quality and growing customer base of leading telecoms network operators, equipment vendors, component manufacturers, and other large enterprises, with a high level of repeat custom.
It has proven that it can drive value from acquisitions with its established global network of partners and distribution capability. The group spends generously on research and development, and has also proven its ability to develop innovative and advanced test solutions. Products are often high spec and complex.
Group R&D is informed by its insights into customer technology roadmaps and likely regulatory developments. Those relationships have been earned over time, meaning it can anticipate market demand. All of the above taken together make for some notable barriers to entry.
The admission doc states that the historical revenue CAGR since FY15 clocks in at c16%, and there is a record order backlog and strong sales pipeline going into FY21.
And there is the market itself: an exciting time in telecoms, with 5G, the Internet of Things, and the shift to cloud computing all creating substantial opportunities in the medium term. We have the likes of Slater Investments on the share register. I would speculate that that kind of institutional investor is looking for substantial growth, and the group’s founder and CEO remains its biggest shareholder.
But then we have the unavoidable fact that this is a recent listing, with much less information available on historic trading.
And the share price has doubled. If we take the above 16% revenue CAGR and take that forward, along with the group’s 3y average profit margin of 15% or so, we get the following:
21e | 22e | 23e | 24e | 25e | |
Revenue (£m) | 15.9 | 18.5 | 21.4 | 24.9 | 28.9 |
Profit after tax(£m) | 2.4 | 2.8 | 3.3 | 3.8 | 4.4 |
Shares in issue (m) | 87.5 | 87.5 | 87.5 | 87.5 | 87.5 |
EPS (p) | 2.8 | 3.2 | 3.8 | 4.4 | 5.1 |
Share price (p) | 99.7 | 99.7 | 99.7 | 99.7 | 99.7 |
PE ratio | 35.7 | 30.8 | 26.5 | 22.9 | 19.7 |
It’s worth noting that Cenkos forecasts a higher adjusted EPS figure of 4p for FY21 so there’s a good chance the above table is too conservative. Nevertheless, it suggests that today’s share price is factoring in good growth and that Calnex is now fairly valued rather than cheap.
That coupled with its newness to the market is enough to keep me on the sidelines for now, but I’m curious to know what others make of Calnex. And then there are the other recent listings in the table above - do subscribers see any big winners there or are we better off waiting for these operators to prove themselves as listed companies?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
i bought Calnex at 124 under small cap this week for 124 and they are now down 7.8%.
I managed to buy into Calnex just after the IPO and bought in, so very happy with the performance to date. Spoken with the CEO and CFO on a couple of occasions and wrote the following that may be of interest to others. https://martinflitton1.wixsite...
Thanks for your articles Martin. They helped me get up to speed with Calnex Solutions (LON:CLX) when I decided to buy in on the day of the results. The shares have gone on a bit of a run since then and are fairly priced at current levels. In time their operational performance should catch up.
I did some research on Calnex last week :-
I liked
- The article below independently substantiates two claims made by the Calnex Admission Document - firstly that 5g relies on testing equipment more than previous mobile protocols, and secondly that Calnex has a leading niche position in the test industry
https://eantc.de/fileadmin/eantc/downloads/News/2019/EANTC-MPLSSDNNFV2019-WhitePaper-v1.2.pdf
-Recent expansion in workforce is a sign of confidence and could be a leading indicator of future growth (10 posts in H1 with 10 more planned in H2 vs existing headcount of 96)
- divi promised for FY 2021/2
- apparently good employee relations should attract the best talent which is important in maintaining market leadership
- plenty of previous M & A in CLX's sector (Keysight takeover of Ixia, Anite. Benchmark takeover of Lark) combined with CLX's apparent market leadership provides a potential safety net
Concerns
- Apparently cheap IPO price (trailing PE of 13) combined with relative lack of institutional support for the float (3 institutional investors hold just 26%) make me concerned that a glitch may come soon. This is somewhat mitigated by the excellent recent interims
- Niche nature of products could limit potential runway for growth
- Ambiguous outlook given at the interims suggesting H2 will be in line with H1 (which would be a disappointing H2 outcome), whilst at the same time claiming that trading in the first 2 months of H2 are in line with recent trends (which, if continued for the rest of H2 would mark an excellent result)
- failed Luceo acquisition
- Reliance on distributers for sales (60% of sales are through Spirent)
I have always been interested in new technology stocks and the developments within the industry itself. Luckily I learnt about Calnex Solutions (LON:CLX) very soon after its IPO. To me it had two essential features and criteria which I look for, the founder has retained a major holding, it has a moat around the coy which I would suggest will be very difficult to copy and last but not least is sitting in a niche position within the communications industry.
Whilst I have already top sliced my holding at almost a 100% gain I am certainly a long term holder in Calnex. The only draw back is I don’t see much drift back in the price in % terms which would enable another bite of the cherry. If the owner were to make a sizeable realisation then I might follow suit.
Inspecs has proved to be a very successful investment with 35% growth over 8 months. As a long time user of Eschenbach products, I am partially sighted, the quality of their products are outstanding so this promises well for Inspecs. I am currently seeking a position in Telecoms as I have nver investted in this sector since BT in 1988. I will certainly take up Calnex. Thank you for the excellent data Jack.
Good report Jack , i hold these shares and was interested when i also noticed slater investments as a major share holder , plus major share holders hold over 75 percent of these shares , which as we see today when there is any comment the shares go on an extreme ride . I think Calnex Solutions is just in the right sector at the moment to keep pleasing to the up side.
Interesting, thanks. Calnex seems in some areas to compete with Spirent Communications (LON:SPT) which is one of the survivors of the dotcom bubble.
Thank you Jack, Calnex Solutions (LON:CLX) has been on my watching list and so I'm pleased to have some expert anaylysis. It's price has settled a bit after a spike last week, this morning however you seem to have lit a rocket underneath it....
Calnex (LON:CLX) I have recently dipped my toe in the water with a small holding here and have not been disappointed. The figures look good and the company appears to be in an interesting sector that could bring more growth in the future.
Thanks Jack, excellent! I was just looking the day before yesterday for a comprehensive list on 2020 New Issues, thinking this year might have thrown up some good bargain valuations. The LSE website is hopeless!!
Useful article thanks Jack. I initiated a position in Calnex Solutions (LON:CLX) recently on the back of their excellent interim results. For more background this recent results presentation is worth a look: https://www.piworld.co.uk/2020...
Thanks for the comment and the link, Damian. Do you often go for IPOs or is this a bit of an exception? And which part of the results in particular stood out to you?
There is a lot to like here on the face of it, with the focus on R&D and patents combined with the high level of forward visibility on industry developments.
I normally avoid IPOs like the plague Jack as they're often over-priced and placed on the market at the cyclical peak of attractiveness. However Calnex Solutions (LON:CLX) has gone public for sensible reasons, it has a solid track-record of revenue/earnings improvement and I can see how it's exposed to several areas of growth. Interesting enough to take out a starter position.
Thank you, Jack, for such excellent detailed background and analysis of a company which has recently popped up on one of my screens. It is a big help in fleshing out the rather limited picture I had formed.
Calnex Solutions (LON:CLX) is already well established and has good growth prospects but, like you, I am nervous of going in so soon after the IPO and at the current price. I may live to regret it...
How do it’s products/services stand-up against the competition? Difficult to invest in anything without good insights on that in my view.
Hi Nebraska,
It's a key question, and, for what it's worth, there are a couple of brief comments re. competition in the Admission Doc, for example:
Calnex is focused on the design validation, conformance test and maintenance test phases of the development life-cycle, which it considers to be high value niches, due to their position as critical points in the development life-cycle, requiring high capability and high-value test equipment and where the Directors’ believe there is limited competition.
Given this is an IPO, finding a reassuring level of detail is always a bit of a struggle, but comments like the above paired with the apparent barriers to entry (like good customer and regulator relationships, product roadmap visibility and R&D spend, and complexity of testing products) do paint the beginnings of a positive picture.