Kelsian: Profiting from boats and buses

Kelsian (ASX:KLS) has a portfolio of passenger transport assets and tourism assets. They were previously known as SeaLink Travel Group. Today they own fleets of buses and ferries in different locations in Australia, Singapore and the UK and recently acquired bus operations in the Channel Islands. Their portfolio includes about 4,000 buses and 113 boats.
The nature of the business is that they have long-term service contracts that are usually government backed. This enables a predictable revenue base. They are also able to pass on increases in fuel costs, wages and general inflation under the terms of most of the contracts which protects margins and reduces variability of bottom line profits.
Revenue is diversified across business units and geographies, however Australian buses are the dominant contributor as outlined in the charts below.
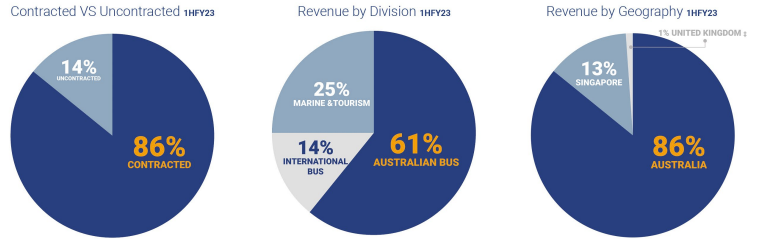
Source: Kelsian Group Limited, FY23 Half Year Results Investor Presentation, 23/2/23
As would be expected, the pandemic marked a difficult period for Kelsian as people’s movements were greatly restricted. The impact was less pronounced for operations under government contracts, as despite the lower patronage, they still received payment to keep the routes operating. The impact was harder felt in the tourism segment where revenues are more closely tied to usage. 2020 was the only year in the last ten where they have returned a loss, and they were exceptional times.
The company has been growing its revenue at a very strong rate. From $200 million in 2017 to a forecast $1.4 billion in 2023 which equates to a compound annual growth rate of 46%. A large portion of this growth has come from acquisitions, but they have also been steadily winning additional contracts. Looking to the future, their growth strategies include looking to acquire bus and ferry assets in New Zealand, North America, Europe and parts of Asia.
But top line growth does not necessarily mean EPS growth. EPS was $0.23 in 2017 and $0.26 in 2022. Analysts are forecasting that it will reach $0.32 in 2023. The reason for this is that a lot of the growth has been funded by issuing new shares, so whilst the company today is bigger, long-term shareholders are not receiving much more income on their shares. Average shares on issue have gone from 104 million to 219 million.
The other component to funding the growth strategy has been taking on more debt. Net debt had grown from $58m to $280 million at December 2022. This increases the balance sheet risk profile with Net Gearing of 57%. The Bankruptcy Risk as measured by the Z2-score is in the Cautious zone.

Of course the absolute debt level is not the only consideration. The company’s ability to cover its interest obligations is equally important. Kelsian has an interest coverage ratio of 4.21 which whilst not outstanding, is ok. This is assisted by the previously discussed point of relative earnings stability and a low level of earnings manipulation risk.
The cash flow situation is also strong. Free cash flow per share is steady and has remained positive over the last six years. It has also generally been above EPS which provides additional confidence that the reported profits are being backed up with actual cash.
All of this translates into a strong Quality Score of 94. The strong cash flow, consistent returns and Health Trend of 8/9 combine to paint a picture of a company in good health.
Dividends have been very steady, growing at a steady rate aside from a dip in 2020. The forecast dividend yield is 2.9%, fully franked.
The market has had a hard time figuring out how to value KLS which is a bit odd given it is a fairly simple business to understand. The challenge probably lies in trying to forecast their growth opportunities and the impact they will have. That said, there was also a lot of euphoria built into the share price back in 2021 as the share price briefly exceeded $10. This did not reflect a change in the fundamentals of the business as shown by the fact that PE ratios were hitting levels above 50.

This does not make a lot of sense for a business whose earnings profile is more akin to that of a utility company.
As the euphoria subsided the stock retreated.One thing that weighed on it was the pursuit of another acquisition. This time it was Go-Ahead, a listed UK bus operator that operates most of the red buses in London. Had it gone ahead, it would have been a very large acquisition and the market was relieved when they pulled out. Go-ahead was eventually acquired by the privately owned Kinetic, who are also an Australian bus operator and the largest player in the Australian market.
The share price continued to slide all the way to $4.32. At this point the selling had probably been overdone and bargain hunters started to step in. Analysts started to gradually increase their earnings expectations and the share price followed suit. This trend has led to a boost in the momentum score. Following the interim results the momentum score has increased 26 points.
The interim results revealed healthy revenue growth of 6.2% as people resumed moving about. This was particularly evident in the domestic tourism business where revenue increased by 41% at the half. International buses were a drag on revenue with a decline of 27%. A big factor was a shortage of labour to operate the buses in Singapore, but management are confident that this has now been resolved. Underlying NPATA grew at 5.1%.
With the share price having rebounded to $6.59 (as at 9/3/23) the value metrics are starting to look a bit stretched. EV to EBITDA is 12.2 and the PE ratio is 17.5. Consequently the Value score has declined to 51.
Kelsian is a business that requires careful consideration of multiple factors. On the positive side it ranks very well in terms of quality metrics and has recently enjoyed positive momentum. It has a dependable revenue base and is consistently profitable.
On the negative side, they have pursued an aggressive expansion strategy. This introduces risk on the balance sheet side, as well as the risk that they may overpay for an asset or try to expand too quickly.
All these elements need to be considered along with the price you would be prepared to pay for a company that, absent acquisitions, should grow at a steady but not astounding rate.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?