KGN: Are the inventory woes over?

The table below shows consensus analysts forecasts for Kogan.com (ASX:KGN) EPS as at the beginning of April in 2021 for the following three years. Below that is the actual EPS results for those years.
EPS forecasts vs actual
FY21 | FY22 | FY23 | |
Forecasts as at 1 Apr 2021 | 0.482 | 0.571 | 0.712 |
Actual results | 0.033 | -0.332 | -0.24 |
The moral of the story is that forecasting is hard. Analysts were expecting a continuation of strong growth. The reality was far more sobering.
Kogan has had a rollercoaster ride since listing in 2016. The share price peaked at $25.57 in October 2020. It is now $5.23, 80% below its peak, but also 92% higher than the low point that was reached in July of 2022.
So what have been the challenges and the triumphs that have led to this wild ride? In a nutshell, it’s about inventory, but first let’s start with some background.
Kogan is an online retailing business. They are best known as an online platform for the sale of goods to retail customers, but they actually have a wide array of business interests. The majority of revenue and profit comes from the sale of goods and services to Australian and New Zealand retail customers. The other types of revenue they earn are:
seller-fee based revenue from Kogan marketplace
commission based revenue from the verticals including Kogan Mobile, Kogan Internet, Kogan Insurance, Kogan Money, Kogan Cars, Kogan Energy and Kogan Travel.
Online retail includes brands that are exclusive to Kogan as well as third-party brands. There is also an online marketplace where other sellers are able to market their wares. In this space it is competing with the likes of Catch (owned by Wesfarmers (ASX:WES)), Ebay and Amazon. Their main business lines are shown in the diagram below.
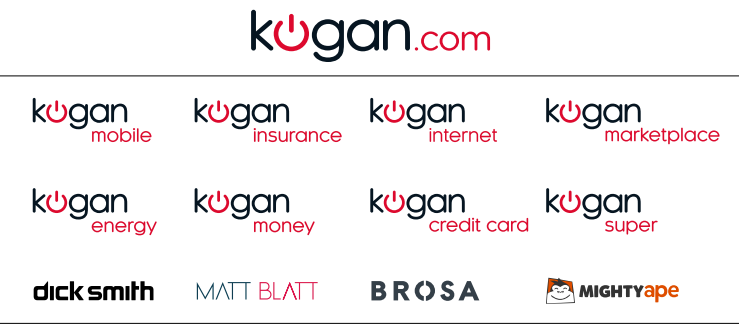
In December 2020, Kogan acquired one of New Zealand’s leading online retailers, Mighty Ape. Mighty Ape is now a significant part of the business.
For reporting purposes the business is divided into two segments, Kogan.com and Mighty Ape.
The revenue and EBITDA breakdown for FY23 is shown below:
Revenue | EBITDA | |
Kogan.com | 68% | -33% |
Mighty Ape | 32% | 133% |
The core components of the business include:
Kogan First
Kogan Marketplace
Exclusive Brands
Third-party brands
Mighty Ape
Verticals (Mobile, Money)
The chart below shows the contribution to gross profit from these core components for each of the two halves of FY23.

(Annual report, p18)
Management has been touting that the business is undergoing a transformation and that the positive effects of this started to bear fruit in the second half of FY23. The diagram highlights the improved contribution to gross profit from exclusive brands and third-party brands. These two areas were traditionally the mainstay of the business, but they have also been the biggest source of problems over the last few years.
As alluded to, the recent travails for Kogan began with some major mistakes regarding inventory levels in 2021. On the back of strong sales in the early part of the pandemic, management stocked up heavily on inventory and even had to lease additional warehouse space to accommodate it. However they over anticipated demand and were left with a lot of stock that they couldn’t sell. It has taken two full years to rectify those mistakes and bring inventory back down to an appropriate level as shown in the chart below.

Source: Annual Report
There are signs that the shifts in the business may be starting to pay off and they may have now turned the corner. Looking at the chart below we can see that the StockRank started to improve from Jan 2022 and moved into the green zone in Jan 2023.

Management describe this as a shift towards platform-based sales which deliver higher recurring revenue, higher gross margins and lower inventory risk. In the past, the model was fully based on acquiring inventory and then selling it, which required a large investment in inventory and then carrying that risk. Providing more services and a platform, reduces that risk. Platform-based sales now account for 57% of Kogan.com revenue, and 71% of gross profit. (Note Kogan.com excludes Mighty Ape). This has also led to improving Sales per dollar of inventory as illustrated in the charts below.


Source: Kogan, Annual Report 2023

Source: Kogan, AGM Presentation, 23/11/23
The turnaround story is supported by the net cash position. In FY23 they completed the repayment of all their financial debt ($35m) and started to build the cash balance. This was made possible by strong net cash from operating activities which grew from $62m in FY22 to $71m in FY23. Inventory reduced from $160m to $68m.
Despite large falls in revenue, gross profit and contribution profit in FY23, gross margin and contribution margin increased.

These improvements are reflected in a Quality score of 92 which is supported by a Health Trend of 6 out of 9.
The share price has jumped over last week since they provided a trading update at the AGM on 23/11/23. It showed that despite a small decline in sales over the first four months of the year, gross profit had improved by 25% and gross margin was 10.33pp higher. This was on the back of further growth in contribution from platform-based sales which have now reached 64%. Further evidence that the turnaround strategy is working.
They did not declare a dividend last year and are undertaking a buy back.
The market has bought the turnaround story and the price has risen, therefore the value metrics do not look as compelling as they did. In fact the forecast PE ratio is quite high at 38.
Kogan has undergone a harsh few years. If they have learned from their mistakes and managed to truly turn things around then they may have a much brighter future.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?