Lancashire Holding: A Hot Pot Yield!

Who's next in the Lloyds insurance serial takeover saga? First Catlin (LON:CGL) is acquired by US reinsurer XL for over 700p per share, then last week Brit (LON:BRIT) accepts a bid from Canadian insurer Fairfax Financial for over 300p per share (post dividend payment), both handsome premia to the pre-bid share price!
Clearly the global catastrophe insurance market is consolidating fast, as besides these two acquisitions, there have already been two other deals in the US reinsurance sector (RenaissanceRe buying Platinum Underwriters, and Axis Holding merging with PartnerRe).
1. Catlin and BRIT have been kind to their shareholders

Source: Bigcharts.com
Of the big five listed Lloyds insurers, that leaves only Beazley (LON:BEZ), Novae (LON:NVA) and Lancashire Holdings (LON:LRE). According to Bloomberg, bid speculation is already swirling around both Lancashire and Novae. Of these three, I am focusing on Lancashire as an attractive investment for a number of reasons, including its status as a potential takeover target.
What exactly does Lancashire do?
But first, a little background on this stock: Lancashire Holding is a Lloyds insurer that offers global specialty insurance and reinsurance products, principally in the fields of Property, Energy, Marine and Aviation. Its two main property reinsurance products include retrocession written on either a single territory or worldwide basis, and catastrophe excess of loss.
3 Reasons to Like Lancashire: Takeover Target, Pumped-Up Profitability, Dishy Dividend
First of all, catastrophe reinsurance (where insurance companies like Aviva pay specialist reinsurance companies like Lancashire) is very profitable - after all, this is why the world's greatest investor, Warren Buffett, operates in this insurance segment with the General Re subsidiary of his company Berkshire Hathaway.
The four merger & acquisition deals listed above highlight that this industry is becoming all about economies of scale – i.e. the bigger you are, the more profitable you are as you can demand higher insurance premiums for the risk you take on. In the UK Lloyd's insurance market, Lancashire, Novae and Beazley all appear to be viable takeover targets.
Impressive Growth Record
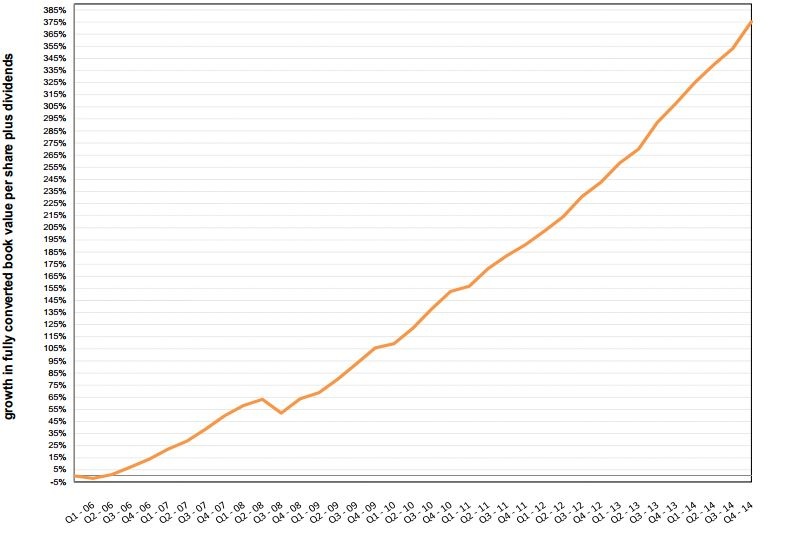
Lancashire has posted impressive growth since 2006, underlined by the impressive long-term growth in book value that the company has achieved, a cumulative 375% growth rate over the last 9 years (Figure 2).
2. Impressive Long-Term Growth in Book Value + Dividends Paid
Source: Lancashire Group
Delicious Dividends
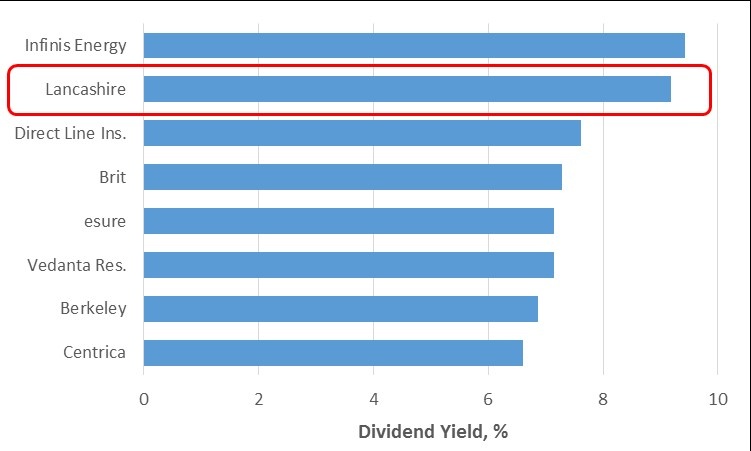
At a time when high income investments are becoming increasingly difficult to find, Lancashire Holdings (LON:LRE) stands out in the FTSE 350 index with its outstanding 9.1% dividend yield, far ahead of any other UK insurer and indeed, the second-highest dividend yielder out of the entire FTSE 350 index (Figure 3).
3. One of the Highest Dividend Yields in the FTSE 350
Source: Stockopedia
You might think that such a high dividend yield is unsustainable – but I would argue otherwise, given that it has paid a bumper special dividend in 6 of the last 7 years (2011 the only exception) in addition to the regular dividend.
Recent Results Rate Highly
February 12's Q4 results were solid, with broker Numis highlighting the $92m pre-tax profit in the quarter beating the consensus $58m expectation by some distance, and Lancashire announcing a 50c special dividend (ex-dividend date: 19 March). This should boost confidence in 2015 forecasts, particularly the 90.6c dividend forecast and the forecast of modest growth in book value.
Cheapest of the Lloyds' Reinsurers
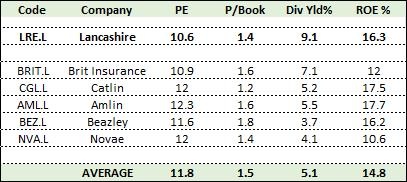
Finally, Lancashire remains the cheapest of the five listed Lloyds' insurers, as can be seen from the table below (Figure 4):
4. Lancashire is the cheapest of the Lloyds Insurers
Source: Stockopedia
Don't Just Take My Word For It, Check Out These other Articles on LRE
I am not the only one to believe that Lancashire is a compelling income story; both noted blogger @chrisoil and also Steve Evans of seekingalpha.com have highlighted the many investment attractions of Lancashire, here, here and here. So by all means check out their well-informed views on Lancashire Holdings (LON:LRE) too!
If you can find a more interesting 9% yielding income stock than Lancashire in the UK market today, then please do let me know! In the meantime, I think that 9% is simply too good to pass up. Get it while you still can!
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
6 comments
Thanks for that Edward
LRE sound interesting - from the POV of its yield and from its differentiation from its peer group - on their website they describe their risk appetite as being quite different from their competitors, so they are not competing for exactly the same business.
I've been a long term fan of BEZ - not least because I have an unalloyed respect for Andrew Horton the CEO.
Comparing LRE with BEZ, the historic yield is attractive but the share price has been much less robust - LRE reached a peak at the start of 2013 and has been on a general downwards trend since then. In contrast BEZ has continued a very clear upwards trend.
http://www.stockopedia.com/charts/technical/?Code=...:20:21
(Sorry, haven't worked out how to include the chart here.)
So, what happened two years ago? Was it a blip? Has it now been fully absorbed? Is the direction of travel going to be onwards and upwards now? Or might there be more mishaps to come?
Would it be better to go for Beazley and settle for a lower yield but a better track record of share price growth?
Being presently out of BEZ I have been prompted by your post to look at its recent price action and I note that it has recently over-corrected after a brief spike. This looks to me like a good buying opportunity.
A question I'd ask about Lancashire is: is it subject to "cliff edge risk"? I.E. is it a business that ticks along nicely for several years and then - Wham! - a major Event hits NAV & earnings for six?
HI Ric,
Well the best I can come up with is this recent Credit Suisse broker downgrade, focused on a weak pricing environment:
(Bloomberg) -- Lancashire Holdings cut from outperform as declining returns will damp stock in future, Credit Suisse says in note.
Sees no valuation upside unless someone offers an M&A premium
Revenue growth, returns on downward trend in weak price environment
2015/2016 EPS ests cut 4.3% and 5.7%
Outperform rating was based on view market hadn’t priced in capital return from Cathedral deal, that’s been realized now
Hi Edmund
I have to say that based on fundamentals this looks like a potentially good investment, particularly with the high yield on offer. The only thing holding me back is that there is a large short position - in fact it is one of the largest short positions in the UK market. Do you have any indication on what the bear case is (other than a potential dividend cut at some point).
Many thanks
Ric
There certainly is a short on responses…
Only 9 years too late.