LVMH delivers record results

The global luxury goods giant LVMH saw revenue and profit hit a new record in 2015. The wealthy clearly haven’t lost their taste for luxury and are unlikely to do so anytime soon. With LVMH covering the full range of the luxury sector it is well placed to withstand market volatility and the fickle nature of fashion.
LVMH describes itself as “the world leader in luxury” and is the only company present across all of the five major luxury sectors. The group’s portfolio includes over 60 prestigious brands and a 3,680 strong store network.
This means that LVMH is not a bet on particular luxury brand unlike its UK listed peers Burberry, Jimmy Choo and Mulberry. Many of LVMH’s brands appear to be timeless such as the cognac Hennessy and the champagne Krug.
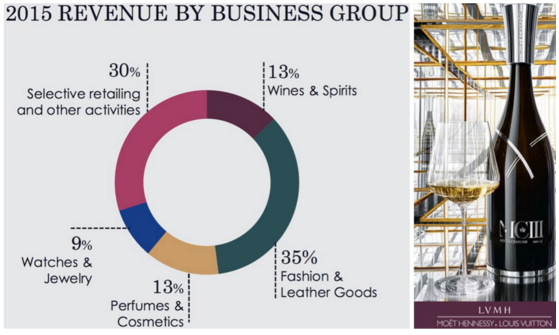
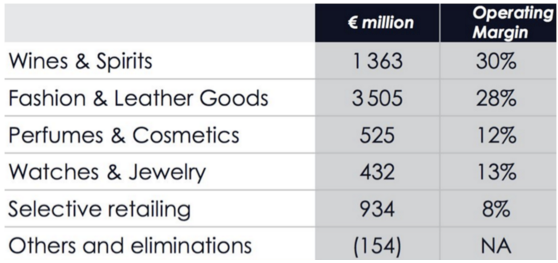
However, the group’s Fashion & Leather Goods division does need to remain in fashion and includes brands like DKNY and Louis Vuitton. It is the mainstay of the business with it generating 35% of revenue and 53% of profit in 2015.
Source: LVMH investor website
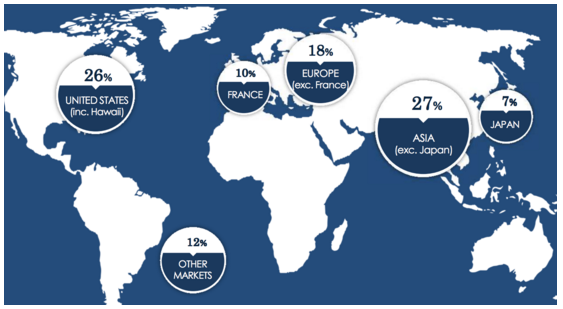
LVMH’s is well diversified on a geographic mix basis with the three main geographic areas being the US, Europe and Asia (excluding Japan). These accounted for 26%, 28% and 27% of revenue in 2015 respectively.
LVMH revenue generation in 2015
Source: LVMH investor presentation
The company has grown through acquisitions with recent deals including the Italian jeweler Bulgari in 2011 and Loro Piana in 2013. LVMH is decentralized so that each business is both “autonomous and responsive.”
The model is similar to Berkshire Hathaway with cashflow from established units used for new areas. LVMH is the creation of Bernard Arnault (Chairman and CEO) and the Arnault family owns the majority of the voting rights.
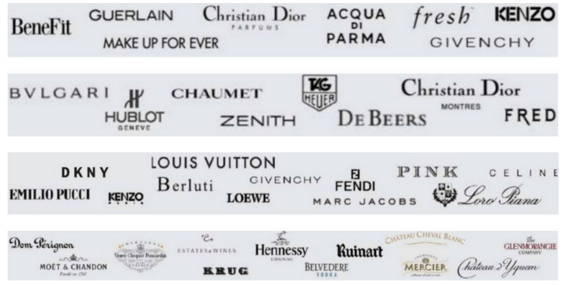
LVMH Group brands
Source: LVMH investor website
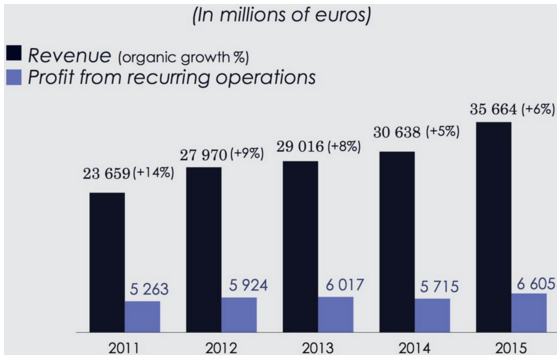
The company’s approach appears to be working with organic revenue growing in all but one year from 2007 to 2015. The global financial crisis saw revenue decline of 4% in 2009 and profit from recurring operations fell 7.6%.
However, the group quickly bounced back with organic revenue up by 13% in 2010 and profit from recurring operations increasing by 29%. This resilience has seen the business offset the Chinese slowdown in recent years.
LVMH five-year track record
Source: LVMH investor website
LVMH Performance in 2015
In 2015 the group achieved 6% organic revenue growth with the performance driven by Europe and the United States. In Asia (excluding Japan) the company suffered a 5% decline in organic revenue due to the Chinese slowdown.
All of the five business areas saw organic revenue growth in 2015 with Watches & Jewelry coming in at 8%. Perfumes & Cosmetics saw 7% growth, Selective Retailing came in at 5% and Wines & Spirits saw 6% organic revenue growth.
The Fashion & Leather goods division was the laggard with only 4% organic revenue growth in 2015. With this division having the highest profit margin it meant that the overall profit margin at LVMH fell back last year.
In 2013 the group generated an operating profit margin (from recurring operations) of 20.7%. However, this fell to 18.7% in 2014 and then saw a further decline to 18.5% in 2015.
LVMH divisional profit from recurring operations in 2015
Source: LVMH investor presentation
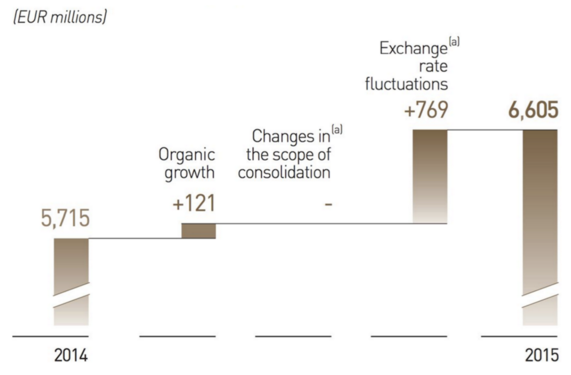
On a positive note the company has benefited from the weakness of the euro following the introduction of QE in January 2015. The group’s reporting currency is the euro but the majority of profit is generated from outside the Eurozone.
Accordingly, while organic revenue growth came in at 6% in 2015 the reported revenue growth was 16%. Organic profit growth was only 2% last year but reported profit growth also came in at 16%.
LVMH profit from recurring operations
Source: LVMH annual report
Summary and valuation
While LVMH reported record results in 2015 the main driver was a fall in the value of the euro on the previous year. This provided a 10% boost to reported revenue and a 14% boost to reported profit.
If the euro hadn’t weakened the group would have seen revenue rise by 6% and profit improve by 2%. Profit growth would have been at a slower pace due to the relatively weak performance of the high margin Fashion & Leather Goods division.
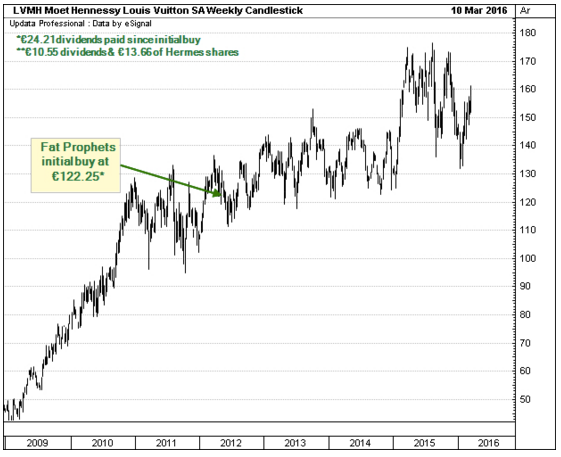
Looking ahead and the onus will be on the Fashion & Leather Goods division to perform well given that it accounts for over half of total profit. While this is hard to call the company has a range of brands that include Louis Vuitton and DKNY.
Other risks include LVMH’s conglomerate structure, the family ownership and the importance of Bernard Arnualt. However, LVMH is also the most diversified luxury goods company in the world and its business units are run autonomously.
The failure to purchase Hermes in 2014 suggests that we may now see a shift away from large takeovers. In 2015 we saw the balance sheet improve with financial gearing falling to 16% at the end of the year versus 21% at the start.
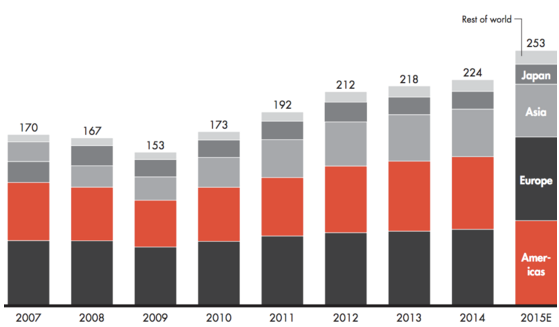
Personal Luxury Goods Market Spending by Region (€ billions)
Source: Bain Luxury Goods Worldwide Market Study Winter 2015
In terms of the rating and the forecast P/E is 19X in 2016, 17.6X in 2017 and by 2020 the figure falls to 13.5X. The forecast dividend yield is 2.5% in 2016 and increases to 3% by 2018 with the payout 2.1X covered over the period.
The valuation is not too expensive, in our view, given the track record of LVMH and the long-term outlook. The newly rich in Asia will drive luxury demand growth for decades to come and in the West the rich keep on getting richer.
This report was produced by Fat Prophets Senior Analyst, Andrew Latto CFA
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?