Market Musings 240922: Start to hunt for deeply discounted quality

Market Musings 240922:
Start to hunt for deeply discounted quality
Where has the market been over-aggressive in its indiscriminate sell-off?
Summary:
- Is a sense of financial market panic in the air?
- Contrarian value to be found as the proverbial baby is thrown out with the bathwater
- Be choosy, look for discounted quality growth companies
- Value also in certain discounted Real Estate Investment Trusts for income seekers
- Don’t be in a rush, markets are unlikely to rebound in a straight line.
- Stocks that look good starting points for more research
Smells like panic is in the air
Another week, and yet more pain for long-suffering stock, credit and bond market investors.
In fact, some of the greatest pain was reserved not for the stock market, but rarely enough, the sovereign bond market.
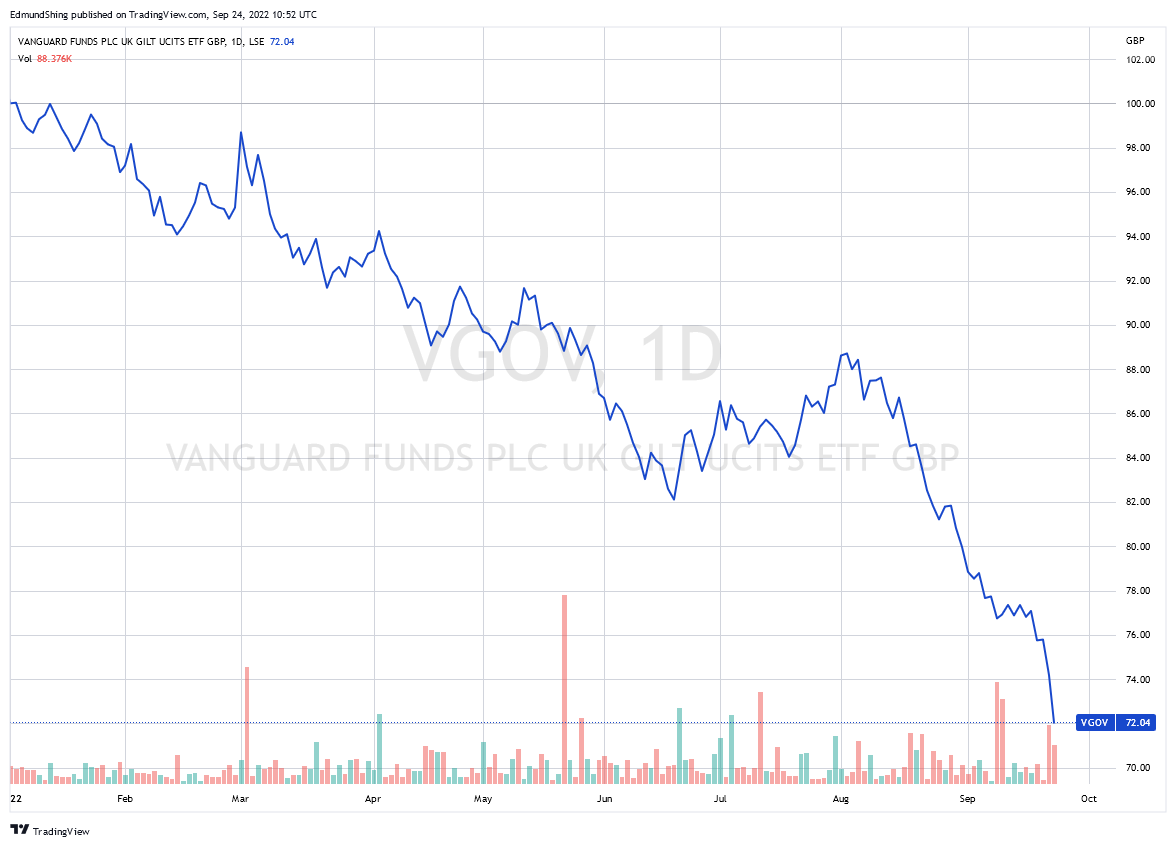
In the wake of the ongoing strength of the US dollar, combined with the nervous bond market reaction to new UK Chancellor of the Exchequer Kwasi Kwarteng’s tax-cutting mini-budget, UK gilts suffered a real shellacking. The £VGOV Vanguard UK Gilt ETF is classified as a 4 out of 7 risk, and yet it has lost 28% over 2022 to date, far worse than e.g. the FTSE 100 stock index.
The VGOV UK Gilt ETF -28% over 2022 (so far)
Source: tradingview.com
Frankly, this week smelt a lot like investor panic, with even formerly resistant segments of the stock market such as the oil & gas sector taking as much of a bath as elsewhere.
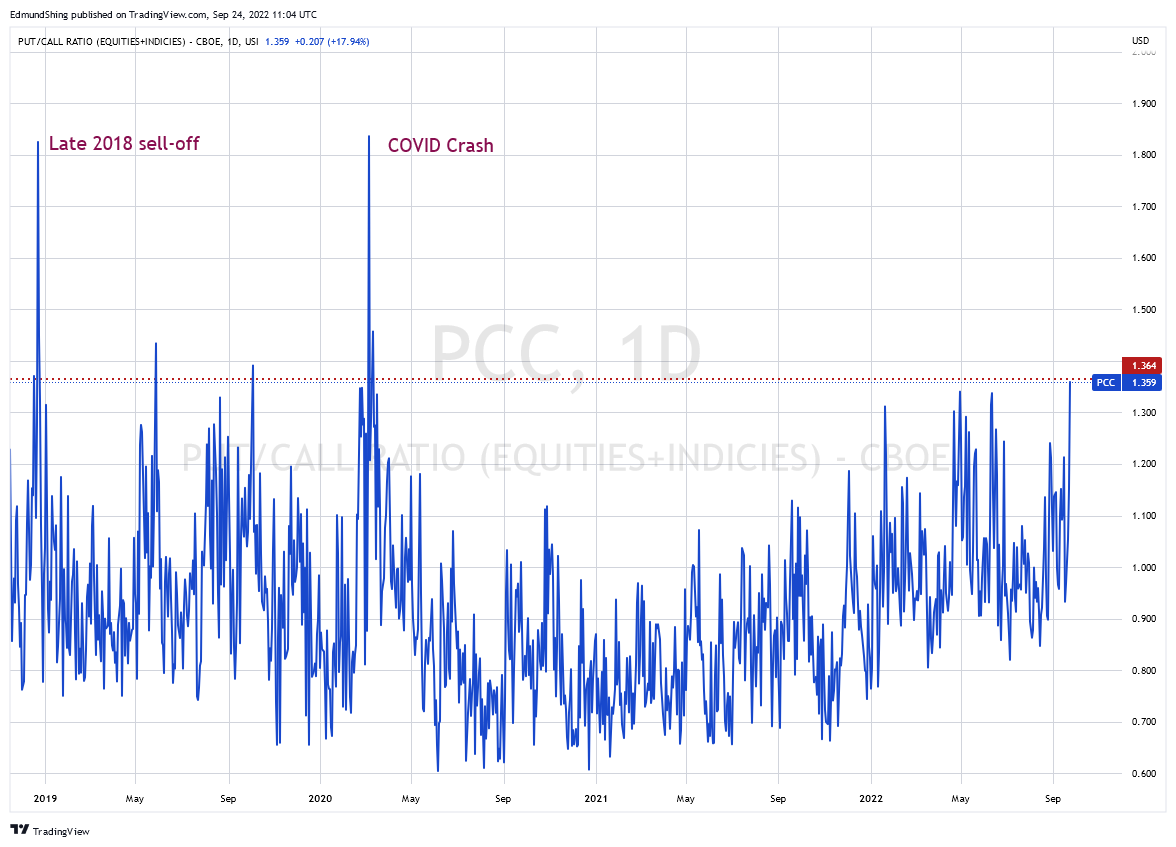
Secondly, the US equity put/call ratio hit its highest level since March 2020 (the depths of the COVID lockdown-triggered market crash). Investors buy calls when they are bullish to get upside to the stock market. But conversely, they buy puts when they want to protect their stock portfolios or position for a falling stock market.
A high put/call ratio then indicates that investors are very bearish on the stock market, as they are buying many more puts than calls..
Most bearish US equity put/call ratio since March 2020
Source: tradingview.com
So markets are rapidly integrating the current/forthcoming recessions in Europe and elsewhere, as higher interest rates and high energy prices take their toll on economic growth.
Institutional investors have been heavy sellers of European stocks for pretty much all of 2022,
Investors have been heavy sellers of EU stocks all year

Source: @isabelnet, from Bank of America
But the contrarian in me smells an opportunity here for the patient, long-term investor. All of this poor economic news is already well-known, so no-one should be surprised at this stage.
I want instead to look for quality stocks and sectors that are the proverbial baby being thrown out with the bathwater, that present excellent contrarian investing opportunities. Yes, this type of investing requires strong nerves, I won’t deny, but also tends to produce good long-term results if you can weather the short-term price volatility.
Hunting for overreactions in quality segments/stocks
Where should we be looking for long-term bargains today?
There are a number of areas that I like to look at right now:
- Real Estate Investment Trusts (REITs) where borrowing is not too high and on the basis of hedged debt, i.e. the REIT is not exposed in the short-term to the sharp rise in interest rates. Also where rents tend to be indexed to inflation, so where one should see rental growth. There are a number of these higher-quality REITs trading today at substantial discounts to Net Asset Value, where not long ago they were trading at a premium to NAV.
- Look for quality (highly profitable, strong franchise, low/no debt) stocks in unloved sectors, where the strength of the business/brands/franchise, quality of management and long-term growth runway outweighs any short-term recession-related worries. Cheap stocks that fall into this category could include: fund and wealth management companies (hit by worries over falling stock and bond markets), quality consumer/retail stocks (worries over hit from economic recession), and selected specialist/niche quality industrial goods/services companies (ditto).
- Cheap UK companies that could make attractive bolt-on acquisitions for larger US or European competitors, given the low valuation of UK small- and mid-caps combined with the recent collapse in the GB Pound.
- Selected oil & gas and mining companies which have higher than sector average profitability, a history of growing production with further exploration potential, no debt and strong free cash flow and dividend generation. An area I still believe in for the long-term relates to the production of industrial metals necessary for batteries and electrification, including nickel, copper, tin and lithium. All of these metals are in very short supply today, have seen prices fall sharply on the back of global recession fears, but should see strong long-term demand growth on the back of heavier investment in energy transition to renewable and low-carbon energy.
- Companies that are counter-cyclical, i.e. that should do well at a time of economic difficulty - such as companies that deal with bankruptcies, companies in administration and pre-pack insolvencies.
Investment conclusion:
- Interesting REITs for further investigation: SUPR Supermarket Income REIT, EBOX Tritax Eurobox, LXI REIT, WHR Warehouse REIT
- Fund managers: POLR Polar Capital, LIO Liontrust, N91 Ninety-One
- Tech/Industrials: SPT Spirent, BOY Bodycote, SOM Somero Enterprise, MGNS Morgan Sindall
- Consumer/media-related: TRMR Tremor
- Retailers: HFD Halfords, PETS Pets at Home, DNLM Dunelm
- Gambling/spreadbetting: PLUS Plus500, 888 Holdings
- Commodities: SLP Sylvania Platinum, CAML Central Asia Metals, AEP Anglo-Eastern Plantations
Of course as ever please Do Your Own Research…
In addition, those looking for potentially undervalued small-cap quality growth stocks might find the following tweet thread from @QCompounding interesting, as it highlights 20 undervalued Quality Small-Cap stocks. This list includes the following 4 UK-listed stocks:
- SDI SDI plc
- TM17 Team 17
- GAW Games Workshop
- CER Cerillion
Perhaps a good starting point for more research…
Have a great week
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
LON:CAML comes up in this discussion but no comment so assume being flagged as some value play: I wonder how this will be affected and for how long that its Khazakstan operations most likely use Russia for transport, so are they still finding markets say in Asia while the west continues to try to punish Russia?
I thought these REITs were the smart choice this year for my ISA as a way to get a good yield without capital destruction much anticipated in bond markets. SO much for that theory. Just wish I was buying now and hadn't done 6 months ago.
Hi Edmund,
I notice you have stayed clear of mentioning any building companies.
What are your views on the building sector for example Persimmon is currently down over 40% would this type of stock be worth picking up.
best wishes
Melvyngd
Excellent article thanks. I'm looking at some of the REITs and some such as Land Securities (LON:LAND) are almost back to where they were in the Great Financial Crash! I'd like to hear some more detailed analysis and commentary on this sector. Having said that I have also been buying fund managers such as Liontrust Asset Management (LON:LIO) and selective retail such as £DNLM
Although currently using a box of tissues per week your assessment was quietly reassuring because I am currently holding POLR, LIO, SOM , SLP, TM17 and GAW- I constantly look at them to confirm to myself that they are good companies and are worth holding on to - your article helps enormously - thank you
Thanks, informative, but you need to look outside the U.K. and also Europe- they are facing immense secular and long-term economic headwinds with overleverage, high inflation, and energy dependence. The economic policies of the Truss govt and the EU project aren't encouraging.
Informative as ever
In addition, those looking for potentially undervalued small-cap quality growth stocks might find the following tweet thread from @QCompounding interesting, as it highlights 20 undervalued Quality Small-Cap stocks
Interesting list. I hold as many as 7 of them! All four UK names plus InMode, Pubmatic and MIPS.
only two companies worth keeping: Cerillion and Games workshop
Always very good articles. Thanks. Absolutely agree on the likelihood of US takeover of UK small caps.
Hi Edmund. I always enjoy your posts. I‘m interested in your thoughts on Tritax EuroBox (LON:EBOX) - the chart is a shocker - due I think partly due to the lack of sentiment in REIT’s but also due to the high gearing, lack of divi cover and refinancing that will be due in 2026. I hold & heavily under water. Would be interested to know what others think too!
Compare EBOX to BBOX (Tritax Big Box ).
BBOX traded at a premium for over 10 years.
Since August it has been at a discount which now reaches 41%.
I have just started a small position but it may well get worse before it gets better.
EBOX has a 43% discount.
BBOX has more liquidity, it is 5 times as large and most metrics are superior.
The important ones are: Free cash flow, gearing and interest cover.
Returns on capital and margins have been better although that may change.
Three Screens I respect for BBOX to one for EBOX.
EBOX has slightly cheaper Price to Book.
From a chart perspective they have followed similar trajectories.
Dead Cross in the spring.
BBOX had a brief bounce in July and another earlier this month.
EBOX only went sideways.
No sign of a bottom on either.
RSI well below 30, so Oversold.
Huge bearish volume.