MTI Wireless Edge - An LSE Defence Stock Flying Under the Radar
Welcome back to the Stock Pitch Series. Today, I’m going to highlight an AIM-listed micro-cap stock with a StockRank of 95 and a ‘High Flyer’ rating. The company in focus is MTI Wireless Edge (LON:MWE) . Here’s why I’m bullish (and I hold stock in it at present).
(Disclosure: At the time of publication, Ed Sheldon had a long position in MWE.)
- Share price at the time of publication: 69p
- Market cap: £61m

The Pitch
Founded in 1970 by engineer Zvi Borovitz, MTI Wireless Edge is an Israel-based technology company that provides radio frequency communication solutions across a range of industries. Today, it has several businesses under its umbrella including:
Wireless Edge: A designer, developer, and manufacturer of state-of-the-art antennas and antenna systems that serves a range of markets including defence, 5G backhaul, RFID, and commercial.
MTI Summit Electronics: A one-stop-shop for RF & microwave solutions in Israel.
Mottech Water Solutions: A provider of advanced remote monitoring and control solutions (based around Motorola technology) for a range of markets and applications, including agricultural irrigation, turf and landscaping irrigation, and water distribution.
PSK WIND Technologies: A specialist in the design, development, manufacture, and testing of ground-based defence systems.
The company is led by CEO Moni Borovitz, who has held the role since 2019. He is the son of Zvi (who sadly passed away in 2025).
Note that MTI reports across three core divisions: Antennas, Water Control & Management, and Distribution & Professional Consulting Services.

The Big Picture
Given its businesses, MTI Wireless Edge looks well placed to benefit from several trends in the years ahead. These include:
Higher defence spending: MTI Wireless Edge offers a range of antenna products for the defence markets including naval and submarine antennas, ground defence antennas, and airborne antennas, so it could benefit from NATO’s increase in defence spending (NATO is targeting 5% of GDP by 2035).
The growing focus on climate change/sustainability/water scarcity: Mottech’s solutions are designed to reduce water and energy usage and increase crop yields so this area of the business should benefit from the growing global demand for efficient resource management and sustainable agriculture (the United Nations Sustainable Development Goals initiative is a key framework for its sustainability work).
The global 5G rollout: MTI specialises in 5G backhaul solutions (behind-the-scenes infrastructure that connects cell towers to networks) so it should benefit from the ongoing global rollout of 5G networks.
This is all encapsulated in this quote from management (pulled from the company’s 2025 full-year results):
“Our target end-markets remain in growth mode. Military conflicts are increasingly reliant on electronics, a shift which is to MTI's advantage, especially when coupled to a global increase in government defence budgets. Demand is increasing for our ABS® antenna solution for E-Band 5G backhaul, representing a substantial opportunity over the medium term and scarcity of water is behind the ongoing drive by governments and businesses to significantly improve the efficient use of this fundamental resource.”
I see the diversified business model as a positive. Ultimately, MTI has a number of ways to win.
Going Deeper
Recent trading updates and newsflow have shown that the company has momentum at the moment:
FY2025 EPS above expectations: In February, the company announced that earnings per share (EPS) for 2025 would be significantly ahead of market expectations at the time.
Strong FY2025 results: Full-year results, posted on 4 March, showed revenue of USD $51.5 million, up 13% year on year, and EPS of 5.86 cents, up 17%. Breaking the results down by division, Antennas saw 11% growth, Water Control & Management revenues saw 10% growth, and Distribution & Professional Consulting Services saw 20% growth.
Multiple defence deals in April: In April, MTI announced defence antenna deals totalling more than USD $9 million.
Solid Q1 update in May: For Q1 2026, revenue was USD $12.8 million, up 6% year on year, while EPS was 1.40 cents, up 18%. These results showed the benefits of the diversified business model – while Antennas revenues fell 20%, the group still managed to generate solid growth thanks to 19% growth in Water Control & Management and 20% growth in Distribution & Professional Consulting Services.
Expansion of Israeli Ministry of Defence order: On 8 June, the company announced that PSK Wind Technologies’ contract for the supply of communications infrastructure to the Israeli Ministry of Defence had doubled in value, increasing from USD $2.2 million to approximately USD $4.5 million.
Looking at the company’s financials, they are solid:
Rising revenues: Analysts forecast growth of around 6.4% this year.
Healthy ROCE: Return on capital employed has averaged around 15% over the last five years.
Growing dividends: Between 2020 and 2025, the dividend payout was increased from 2.5 cents to 3.4 cents, a CAGR of 6.3% (the trailing yield today is around 3.7%).
Buybacks: The company has said that it will buy back stock until March 2027.
Robust balance sheet: Net cash as at 31 March 2026 was USD $8.5 million.
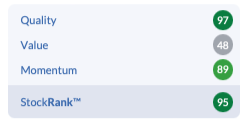
Overall, there is a considerable level of quality. Note that Stockopedia gives MWE a QualityRank of 97:
Turning to the chart, the set-up looks attractive:
Upward trend: The share price is above both the 50 and 200-day moving averages.
Not overbought: The RSI is near 60 so the stock isn’t in ‘overbought’ territory.
Healthy quant rating: The Stockopedia MomentumRank rating is 89.
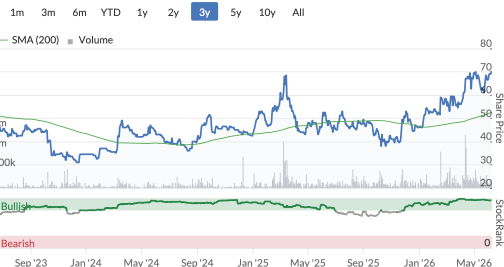
In terms of the valuation, I see it as quite reasonable. Taking last year’s EPS figure of 5.86 US cents, we get a trailing P/E ratio of around 16x.
What the Brokers Say
Given the size of this company, there is not a lot of broker coverage, but the coverage I can find appears to be quite bullish:
Shore Capital (joint broker): Price target of 100p
Allenby Capital (joint broker): Price target of 95p
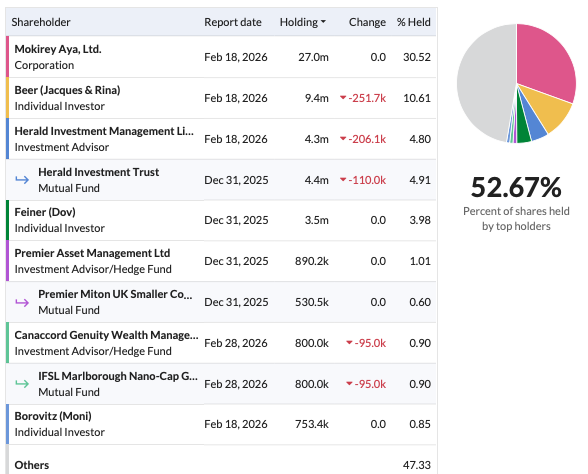
The stock is owned by a number of mutual funds/investment trusts including the IFSL Marlborough Nano-Cap Growth Fund, Premier Miton UK Smaller Companies Fund, and the Herald Investment Trust (a tech-focused trust):
The Bear Case
Some risks to consider include:
A slowdown in defence spending: The bull case here is built around defence antenna demand. If defence spending slows, growth could moderate.
Weakness in core markets: In Q1, Antenna revenues were down overall due to weak 5G backhaul sales in India.
Manufacturing disruptions: While MTI’s core manufacturing facilities are protected by Israel's multi-layered air defence network, there is the risk of operational disruption from potential missile or drone strikes.
International complexity: When an AIM-listed company is headquartered overseas, it introduces added layers of operational, regulatory, and legal complexity for investors.
Corporate governance: Chair Amalia Borovitz Bryl is the sister of the CEO.
Significant family ownership: The Borovitz family owns around 32% of the company’s shares so any move to sell could put pressure on the stock.
Liquidity and trading spreads: This is a very small company so investors should expect the share price to be volatile and trading liquidity to be thin at times.
The Bottom Line
Overall, there’s a lot to like about MTI Wireless Edge. The company appears well positioned to benefit from several powerful trends and its financials look solid.
There are plenty of risks, and the stock isn’t going to be for everyone given the backdrop in the Middle East. However, right now, the stock is trending higher, and its StockRank of 95 is noteworthy.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
A excellent overview Ed.
A few MTI contract/margin thoughts:
Monday's Allenby broker note states that; "c. 20% of additional revenue typically translates into EBIT."
MTI has announced defence contracts worth approximately $9m in April plus the $4.5m PSK doubling in June — call it $11.2m of new defence contracts in 6 weeks. At 20% EBIT conversion, that is a significant $2.3m of incremental EBIT being added to the pipeline in a single quarter of announcements.
Allenby note: further defence sales opportunities ahead, and joint broker Shore Capital flags Mottech water software demand as a potential additional upside source not in forecasts.
MTI appears to be building a contract backlog that is running materially ahead of what the brokers have in their models. This is the type of setup where a stock trading at -40% below broker targets begins to close that gap — not through multiple expansion, but through earnings upgrades as the sales backlog convert to revenue and earnings. I hold.
Appreciate the comment iwright7. I agree - the backlog is very promising.
According to Stockopedia: M. Borovitz holds 32.22% of the shares.
As usual, with Israeli companies, the directors are well rewarded.
Hi Rusty2,
Here is some insight on the ownership from an RNS in Jan:
MTI Wireless Edge Ltd (AIM: MWE), the technology group focused on comprehensive communication and radio frequency solutions across multiple sectors, provides an update in relation to the holdings in the Company formerly owned by Zvi Borovitz, former Chairman and founder of MTI, following his passing in June 2025.
Zvi Borovitz was beneficially interested in 1,146,429 ordinary shares of par value 0.01 Israeli Shekels each in the capital of the Company ("Ordinary Shares"). MTI was informed on 15 January 2026 that the Estate of Zvi Borovitz transferred 382,143 Ordinary Shares for nil consideration to each of MTI's Chief Executive Officer, Moni Borovitz and the Chair of MTI's board of directors, Amalia Borovitz Bryl and it is understood that the Estate executed these transfers on or around 24 December 2025. Following these transfers, Moni Borovitz is beneficially interested in 753,397 Ordinary Shares representing 0.87% of the voting rights in the Company and Amalia Borovitz Bryl is beneficially interested in 382,143 Ordinary Shares representing 0.44% of the voting rights in the Company.
Mokirei Aya Ltd. ("Mokirei Aya") has an interest in 27,020,895 Ordinary Shares, which remains unchanged and is equivalent to 31.35% of the voting rights in the Company. Zvi Borovitz formerly held 25% of Mokirei Aya, with Moni Borovitz and Amalia Borovitz Bryl each holding 25% of Mokirei Aya. Zvi Borovitz's holding in Mokirei Aya has been transferred, in equal amounts, to Moni Borovitz and Amalia Borovitz Bryl, who now each hold 37.5% of Mokirei Aya. Pursuant to UK MAR (as defined below) Mokirei Aya remains a person closely associated with Moni Borovitz and Amalia Borovitz Bryl.
Nice article, Ed! A stock I always wanted to take a closer look at!
Appreciate the comment James!
A high proportion of its sales are to the Israeli military and its other sales seem rather pitiful.
Used to own it but when Gaza started and its work with the Israeli military built up I decided to sell out. I own tobacco stocks so not going to preach morals but not something I would want to own.
there’s also a risk of a wider boycott of Israeli linked companies involved with the military at some point I thing. Always looked cheape
It is heavily linked to defence yes, but the 2025 annual report shows that over a third of revenues come from water control and management, and around 30% of total revenues are international.
The 2025 Annual Report shows that of its £51m of revenue £ 36m comes from Israel. I am a shareholder but I need convincing that the international ( defence ) sales will flow in. Fortunately the stock is on a cheap rating so I patiently wait.