N Brown (BWNG): A stalwart leaves

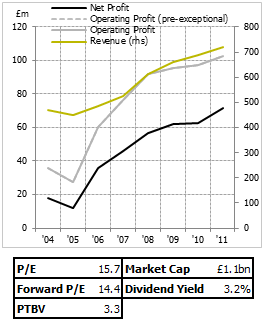 N Brown (LON:BWNG) is one of the shares that has been in my portfolio since it begun nearly 20 months ago. The plus-size and niche clothing producer, home of brands like Jacamo and Simply Be, attracted me initially because of the relatively modest earnings yield on what seemed to be a solid business with a defencible position. Much of my investment methodology has changed since those early days, but that's still a position I agree with - though there's far more to it now. In this post I'll try and look at why I'm selling N Brown now, beyond the most simplistic explanation. That explanation, of course, is that the price has risen - I bought for about 250p and it's now 60% higher at 400p. Frankly, this is reason enough, but there is more to it than that!
The simple
Still, the price issue deserves at least some exploration. N Brown was never ludicrously cheap - not like some of the shares that have made it into my portfolio - but I don't think midcaps do often get into that rock-bottom territory. Operating profit isn't hugely changed from '10 to now (up about 5%, below inflation), with much of the difference in net profit coming about from tax timing issues. This is good, of course - more money is always good - but it's clearly not as good as an increase in operating profit, which would signal an improvement in the underlying situation as opposed to simply jigging around what you owe Mr. Taxman. As an example, this year N Brown paid £15.9m of tax on £96.9m of tax. If no adjustments with respect to previous tax losses and carry-forwards were made, they would have paid £25.4m out.
So N Brown is in roughly the same spot it was when I bought it. In EPS terms, forecasts are flat for the next few years too. The price change, then, has basically come about because of a rerating - a difference of market opinion between 2011, when I purchased, and now. This is fine. What causes a price change is irrelevant to me; the one thing this situation does mean, though, is that N Brown is likely to have changed in my book. If the company was 60% more expensive because they were making 60% more money, it might still strike me as being cheap.
The less simple
I still think N Brown is a good company. I just don't think it deserves a 'premium' price - a price which implies a strong amount of growth, or startling predictability of returns. Loosely, those are the two things that I don't mind paying extra for - and we can see that in the market at large, too. Treasury bonds/bills always have low coupons because their returns are perfectly predictable; risk free, if you trust normal market parlance. Examples of the growth premium are evident everywhere. The dot-com bubble is the obvious, if tired, cliche.
Do I think N Brown is set up for high growth? Not particularly. I do think they'll experience above market growth. I think the business is well-run, and I think plus-size is a growing industry (hey, this'll likely be my last post on N Brown - humour me using these puns one last time!). They've pulled off a classic business coup in becoming dominant players in a small section of a large industry, but the good bit is that theirs is probably the best bit to be involved in. The one big proviso I give to that analysis is that I still dislike the large portion of their revenue (29%) that comes from 'rendering of services' - credit accounts where interest is charged on purchases. They're run like store cards, with the simplicity of just being able to buy what you want and pay back whenever you can, with a 40% interest rate in the interim.
It seems ludicrous that, if we simply use average numbers, a customer who spends £100 on clothes then whacks another £30 on their bill in interest charges. This may well be sustainable, but my base case has to be that people are getting more and more savvy to this sort of unnecessary expense and will cut back on costs like this. Perhaps I'm being naive, or not understanding the value of this service to customers. I often say that investing is half a battle with my own personal biases. As a value investor, an obvious bias of mine would be that I hate that sort of recurring, needless cost! I have to apply a discount in my mind for this, anyway - particularly as I don't have the requisite information to be able to 'adjust' the accounts for a decline in this revenue stream. Just chopping off the profit from it is unfair, since I imagine a good deal of N Brown's admin costs go to this side of things, too.
Finally, though, do I think N Brown are likely to be hugely stable in returns into the future? Well, that depends on what you compare them to. By virtue of their size and defencible position, yes, I think they'll do better than most. Their returns have historically been pretty stable. Clothes are things people are always going to need, too, barring a nudist revolution. They are retailers, though - and retail is always a fast moving sector. Ways of doing things can seem old hat much quicker than people expect - something that'd be immediately obvious if we went back 15 years and looked at the high street then.
They're certainly not like the utilities, chugging away for decades on end. You're betting on management really, being competent enough to keep up with everything's that changing before the company becomes irrelevant.
Summing up
The Benjamin Graham quote seems relevant here:
In the short run, the market is a voting machine but in the long run it is a weighing machine
It's just a weighting game - I like N Brown as a business, but it has its downsides. Stick those on one side of the scales, and on the other side put the inflated price since I first bought, and the result is my decision to sell. I've looked at the price, I've looked at the returns and I've looked at the potential growth and risk factors - and I don't want to pay my share of the £1.1bn for those expected cashflows, so someone who does will take them off my hands.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?