NEXT: a high-yield share in the making?

TL;DR:
NEXT Directory is the driving force behind future growth and recently announced special dividends propel this share into high-yield territory.
NEXT Directory is the future
Three months ago I spent some time analysing NEXT from the private investor perspective. From this I concluded that NEXT is a superbly run company producing great results and would be a fantastic buy - in 2008. Back then the shares were, demonstrably, a steal at less than £10; in the 5 years since earnings per share have more than doubled and the share price has multiplied seven-fold!
However besides NEXT shares being expensive, by most metrics, the graph that really gave me pause for thought last year was one of debtor day history. Typically a rising trend-line suggests that a company is relaxing payment terms for its customers and/or having difficulty collecting the money that it's owed. With NEXT Directory becoming ever more important I wondered if this was a harbinger of upset ahead:
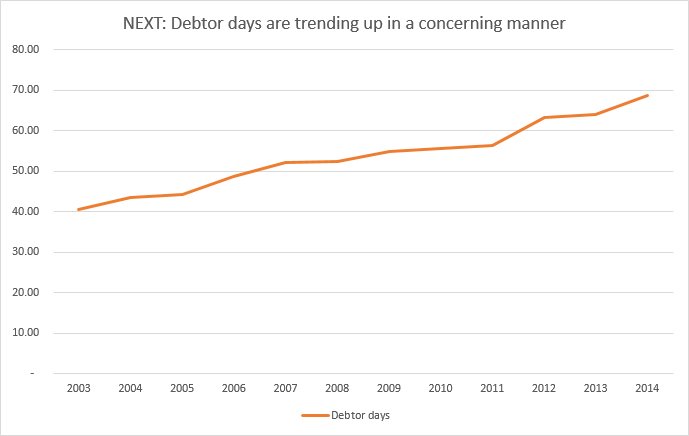
Recently though I've come back to NEXT following their Christmas trading statement. In this management set out how sales growth, of 2.9%, came in at the upper end of previous guidance and that full-year profits will hit a tight range of around £775M. So the picture looks pretty rosy although with a decent slug of realism concerning economic prospects for 2015 and tough comparables from last year.
While considering this statement I realised that previously I erred and should have thought to examine the turnover and receivables of Retail and Directory separately. In the former there are almost no receivables as customers willingly hand over their cash before the company even pays its own suppliers! With Directory sales there is, by design, a long credit period for customers and thus a tail of outstanding debtors. It turns out that despite Directory turnover almost tripling in the last decade this tail remains well managed:
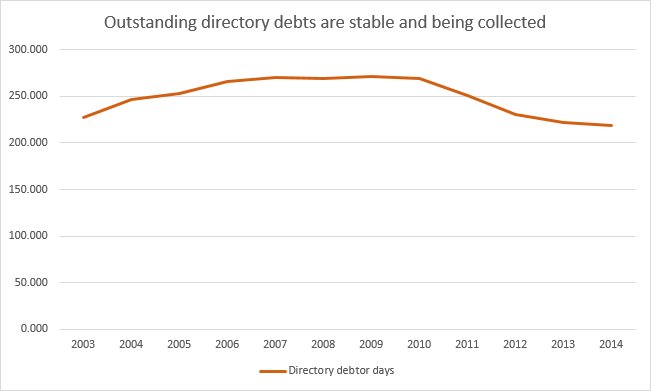
With this Retail/Directory split in mind I've also plugged into my spreadsheet the operating profit figures, for each side of the firm, to check how the margins stack up. Previously I looked at the blended margin, which is both stable and high at around 16%, but teasing apart the percentages is nothing short of a revelation:
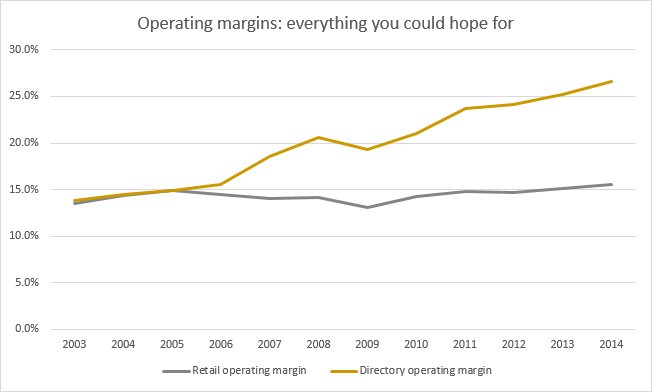
Quite simply NEXT Directory benefits from excellent, at above 20%, and sharply increasing margins on the whole of its business. Given the present level of investment in this area, and focus on online expansion, I can easily see how management are planning to maintain growth, cash-flow and a ROCE in excess of 50%.
High yield and high quality
Along with the concerns noted above I was also, previously, left with something of a dilemma regarding NEXT as an income stock. In years gone by management have invested large chunks of free cash-flow into share buy-backs and left shareholders with a reasonable but low yield of around 3% (on average). There's no doubt that this has proven an effective strategy, which makes a nice change, but nothing feels quite so much like a decent return as cash in your pocket!
However the Christmas trading statement provides a bit of a fillip in this direction with the announcement that buybacks are currently postponed, due to the buoyant share price, and that there would be another special dividend of 50p. A welcome surprise. In addition the proclamation intimates that buybacks might not be possible for quite some time; given the prevailing share price and profit forecasts for 2016.
Suddenly then the prospect of receiving 150p in ordinary dividends, and the same again in special dividends, becomes a whole lot more real. Even now, with the share price at 7165p, this equates to a yield of almost 4.2%; a lot more than the median forecast yield of 2.98%, for all dividend paying stocks in the market, and enough of a signal for me to press the big red buy button!
Of course life is full of surprises and sometimes they're good ones! Just three days ago NEXT revealed a further special dividend, this time hoisted to 60p a share, with the coda that we might well receive one of these a quarter. Altogether then this could lead to a whopping payout of 390p over the coming year and that translates into a yield of near 5.5%. Given how my high-yield screen only returns 25 shares, that I might be inclined to invest in, with a yield above this level then NEXT is a pretty good bet if you're an income investor.
Disclosure: the author holds shares in this company
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
RandomAmbler;
Thanks for the article. Next is a great company - I need to look into the directory business myself. Retail always makes me a bit nervous, and there's a lot of implicit debt in lease form, but you can't argue with their track record.
VegPatch,
Fantastic comment. Thanks very much for posting it.
OK I will try again as my tables seemed to disappear. Apologies. Hopefully this will work.
Hi RandomAmbler
I have met the management team of Next on a number of occasions and they consistently rank in my top 5 for clarity of corporate vision and how they intend to create shareholder value. For full disclosure it also makes up nearly 10% of my SIPP, so I am predisposed to liking the shares (at the moment).
The most telling example I can use is from the Next 2013 Annual report (http://www.nextplc.co.uk/~/media/Files/N/Next-PLC/pdfs/latest-news/2013/ar2013.pdf). Here it explains the corporate strategy very clearly and breaks down the biggest profit drivers in a way that you seldom see in most annual reports like say of Tescos. One example is the yoy comparison of operating margin.
This excellent disclosure allows us to really understand where Next makes its money and what the major moving parts are.
In comparison from the M&S 2014 annual report
http://planareport.marksandspencer.com/downloads/MS_AR2014_Annual_Report.pdf
This tells us that UK GM was down 110bps but not really the drivers behind it. Lots of words, not much detail. To me its the little things like this that give me clues as to who really understands their business and has great Management Information systems.
However the thing that really sets Next aside for me is the incessant focus shareholder value creation. Lord Wolfson & the team around him really understand share buybacks. This is from the 2013 Annual Report and sets out why Next buys back shares
Crucially management compares the use of cash for share buybacks and consequent earnings enhancement against investing those same cashflows into an alternative investment. It calls this its Equivalent Rate of Return (ERR) . The Group then goes one stage further and sets out the maths behind its ERR
So the company chooses whether to buy back shares when they are cheap and the buyback provides a better rate of return (>9%) than the Stockmarket's expected return on equity of 8%. As the share price rises their enthusiasm to buy back share wanes.
At the 2015 interims the Group reset its ERR to £66, as the limit at which to buy back shares. When the share price rises above this level and the return on buying back the shares falls below the market return, the Company then chooses to return the surplus cash (ie that which is not needed to invest and grow the business) to shareholders via Special Dividends.
For me its a company with very high Returns on Capital, it is very well invested eg best in class internet delivery and has superior management who understand what to do with shareholders capital. A powerful combination that promotes the compounding of my capital at a very acceptable rate.
VegPatch
Hi VegPatch,
Thanks so much for taking the time to respond and also for persevering with getting the charts to display - they add a lot of value!
Anyway I agree with absolutely all of your points - I think the management transparency here is just fantastic and a demonstration of how the board regards the owners of the business and their duty of care towards them. I also take your point of how the ability to report at this level of detail implies excellent internal controls.
I hadn't drilled into the maths behind the buybacks before but everything shown here makes absolute sense. The buybacks that they have made so far have demonstrably boosted the eps and led to capital appreciation (alongside the underlying business performance). Now that they are in a position where special dividends are most appropriate I rather like the yield that it implies and their dedication to shareholder returns.
Cheers,
Damian
Hi RandomAmbler
I have met the management team of Next on a number of occasions and they consistently rank in my top 5 for clarity of corporate vision and how they intend to create shareholder value. For full disclosure it also makes up nearly 10% of my SIPP, so I am predisposed to liking the shares (at the moment).
The most telling example I can use is from the Next 2013 Annual report (http://www.nextplc.co.uk/~/media/Files/N/Next-PLC/pdfs/latest-news/2013/ar2013.pdf). Here it explains the corporate strategy very clearly and breaks down the biggest profit drivers in a way that you seldom see in most annual reports like say of Tescos. One example is the yoy comparison of operating margin.
This excellent disclosure allows us to really understand where Next makes its money and what the major moving parts are.
In comparison from the M&S 2014 annual report
http://planareport.marksandspencer.com/downloads/MS_AR2014_Annual_Report.pdf
This tells us that UK GM was down 110bps but not really the drivers behind it. Lots of words, not much detail. To me its the little things like this that give me clues as to who really understands their business and has great Management Information systems.
However the thing that really sets Next aside for me is the shareholder value creation. Lord Wolfson & the team around him really understand share buybacks. This is from the 2013 Annual Report and sets out why Next buys back shares
Crucially management compares the use of cash for share buybacks and consequent earnings enhancement against investing those same cashflows into an alternative investment. It calls this its Equivalent Rate of Return (ERR) . The Group then goes one stage further and sets out the maths behind its ERR
So the company chooses whether to buy back shares when they are cheap and the buyback provides a better rate of return (>9%) than the Stockmarket's expected return on equity of 8%. As the share price rises their enthusiasm to buy back share wanes.
At the 2015 interims the Group reset its ERR to £66, as the limit at which to buy back shares. When the share price rises above this level and the return on buying back the shares falls below the market return, the Company then chooses to return the surplus cash (ie that which is not needed to invest and grow the business) to shareholders via Special Dividends.
For me its a company with very high Returns on Capital, it is very well invested eg best in class internet delivery and has superior management who understand what to do with shareholders capital. A powerful combination that promotes the compounding of my capital at a very acceptable rate.
VegPatch