Nick Kirrage Interview - Inside the mind of a deep value fund manager

Buying bargain basement stocks that nobody else wants is a strategy that’s forged the reputations of some of the world’s greatest investors. Yet, while value investing has a rich heritage and stellar performance history, it comes with drawbacks. Performance can be volatile and deep value stocks can be unpredictable. Ultimately, it’s an approach that suffers periods of underperformance.
With this in mind, it’s hardly surprising that disciplined, long-term value investing isn’t exactly prevalent in professional fund management. In an industry notorious for short-term performance targets, value-focused fund managers arguably suffer from career risk more than most.
But one exception is the Value Investment Team at the asset management giant, Schroders. Headed by Nick Kirrage and Kevin Murphy, the team manages around $18 billion across a suite of value funds, including the Schroder Recovery fund, which they took over in 2006, and the Schroder Income fund.
Having just celebrated the tenth year running the £750m deep-value Recovery fund, I met with Nick Kirrage to find out what it really takes to beat the market in stocks that nobody else will touch.
You’ve now been running the Recovery fund for 10 years, and it’s up 127.1% against a sector average of 72.5%. What are your reflections on what you’ve achieved and how it has performed?
Kevin and I have been investing for over 15 years, and 10 of those have been spent running the Recovery fund. When we took it on there was quite a lot of responsibility, even though very few in the UK market knew about it. It was an unconstrained fund that was benchmark-unaware and half the book was institutional and internal money. We were invited to showcase what we could do, as long as it was in a value style. Of course, the first thing we did was underperform for two years!
But that’s the nature of the market. Value outperforms over time, and when it doesn’t I think a lot of the skill in the job is psychological. It’s about learning not to drive yourself crazy or fall apart on bad performance. Over time you have a strategy that outperforms, but you also know that you’ll struggle with it.
So it was a huge source of celebration after 10 years because we’d set ourselves the target of being in the top decile over that time period, and we were. The fund’s performance is around 18th out of 320 at the start of that period. But the job is only half done. We always said we’d like a 20 or 25 year track record. If we could repeat the fund’s performance from the first 10 years it probably starts to put us in a group of names that everyone knows. It’s not really about running a lot more money, it’s about doing something that, statistically, would have proven that it’s not complete luck. We’ll have done something rigorous, repeatable and valuable for clients.
At what point in your career did you develop this strong value-focused philosophy?
I didn’t do economics at university, I did aeronautical engineering because I like things you can prove and build. The numbers say the plane will fly if the lift is more than the weight and the drag. I’m inherently drawn to an approach where you can look back over 100 years and say ‘this will work’.
The question as to why it will work is really important. The reason why value works is that everything changes in investment except one thing - humans. We’re the bit that’s constant. Our behaviour, our emotion and our psychology is the only thing that doesn’t change. So being able to say that this works because humans are pretty predictable on average over a long time period is a very reassuring thing for me.
Presumably you need that reassurance given that value investing is well known to have periods when it doesn’t work?
While it’s reassuring, someone can take you to one side and say the bad news is that if you invest in a classic low-P/E value strategy you’ve got a 70% chance of underperforming for three years in a row over 25 year investment career. Doesn’t everyone get sacked if they underperform for three years in a row? Yes, probably. So the first thing you sign up to as a value investor is that you hope those three years aren’t the first three. You can’t pull out of the strategy when you’re two years in and starting to get nervous.
Psychologically you’ve got a set of criteria and you have got to fully sign up and embrace it. I love the fact that I’ve got an approach that means I just need to be mentally tough. We do a great deal of statistical and company analysis and I spent a lot of time learning about balance sheets and accounting. But while that’s important, in the end our big advantage is being able to do what other investors don’t, won’t or can’t for reasons that are either real or imaginary.
How do you balance the inevitable periods of underperformance with working in an industry that is so competitive and judged on recent performance?
I can’t escape the numbers that value may underperform. Every value investor in the world is crossing their fingers that we’re not going back to the late 1990s, when there was five years of aggressive value underperformance. People like Neil Woodford did a great job holding the line for many of those undervalued investments. But the truth is that for every guy that survived and and went on to become a guru, there were 10 guys that got sacked three months ahead of time.
There is a luck element but you can help yourself by doing a number of things. First, you can manage expectations and work for a firm that has a heritage of doing this, which Schroders has. You can also work for a house with multiple teams. Within Schroders the Value Investing Team that Kevin and I run manages $18 billion. But that doesn’t really touch the sides in the context of Schroders. Within Schroders we tend to be doing badly when everyone else is doing well and vice versa.
Finally, the most important thing is to be honest with your clients. The volatility of an approach like Recovery is quite significant, and even though it is low turnover it has got very high benchmark volatility because it is so different to the benchmark. When we’re 50% ahead of the benchmark, as we were in 2012/13, we don’t go to clients and say now is the time to invest. But when we’re 15% behind the benchmark, as we were in 2015, we do approach them with the tough sell that now would be a good time to give us more money. After 10 years they can see there’s quite a good track record of us bouncing back. Even though those periods of underperformance are brutal as an investor and difficult for clients, you give yourself the full three years to come good.
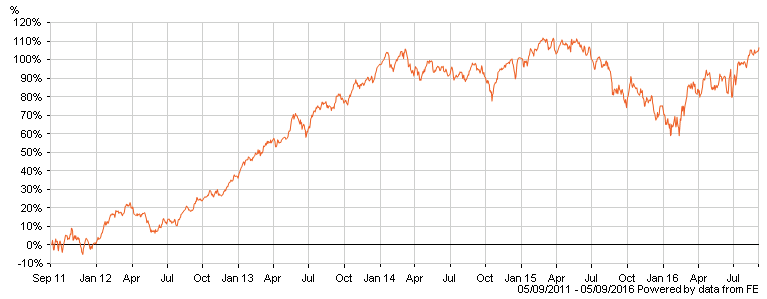 Schroder Recovery fund - 5 year performance: Financial Express
There are a lot of well known names in value investing, but are there any that have been a particular inspiration to you?
David Dreman’s Contrarian Investment Strategies: The Next Step was the first value book I read and I was blown away by it. He’s one of the elder statesmen of value investing and he’s still getting sacked from places he goes to! After that there was The Intelligent Investor and Security Analysis and then Joel Greenblatt and James Montier and all the behavioural finance stuff by people like Daniel Kahneman and Michael Mauboussin.
There’s another guy called Richard Oldfield, who’s a value investor in the UK, and he wrote a book called Simple But Not Easy, and I think that totally encompasses value investing. When people talk about it, you think that everyone can do go off and do it. And in many ways everyone can do it, but it is not easy. The number of people in this environment that are using the justification of being a value investor to buy Unilever on 25x earnings is extraordinary. I feel like I want to shake some of these guys and say ‘I understand what you’re saying but this is a complete bastardisation of everything that Ben Graham conceived.’
When it comes to your investment process, where do you start?
My job is to identify risk and reward, balance the two and work out where the risk is mispriced. We believe that reward is identified as some function of normalised profits and a normalised multiple. You work out what you want to pay for it, which is typically somewhere between eight and 12 times earnings - bearing in mind we’re pretty stingy people. Then you’ll work out a target price, which will give you an upside or a downside. There are a lot of factors that go into that, like looking back at the accounting and watching for red flags.
On the other side you have risk, which is a more intangible thing. Everybody wants to turn risk into a number, and typically that will be volatility. But I believe that permanent risk of capital is associated with indebtedness, although there maybe business factors that are genuine structural risks that you have to take into account.
Leverage tends to be the way that you permanently lose money because businesses get squeezed to death. It’s not always balance sheet leverage, it could be working capital adjustments, factor financing, pensions, lease adjustments or cash trapped overseas.
Once you’ve done all of that, you have work out how to compare these two things - where is my target price and where is my risk/reward?
How do you deal with the fact that you might miss something or that some of these companies just won't recover?
We are continuously trying to evolve how we think as a team and asking how we can get better. It’s a strange industry because if I buy a stock that goes to zero a year later, did I do the right thing or the wrong thing?
Typically, the answer of course is that I did the wrong thing. But I don’t believe that because I live in a world of probabilities. What I want to know is if I make that call 100 times over my investment career, will I be right with 70 of them? That’s an incredibly powerful thing to do. With a portfolio of 50 stocks, if 28 are great ideas and 22 are disastrous ideas and I repeat that percentage every year for 30 years, I’m in the best 5% of fund managers who ever lived on the planet.
That’s hundreds of mistakes, so I need to have high conviction but also humility and understanding of my ability to forecast the future and the probabilities of the world. So we do have a checklist in terms of how we think about things like the balance sheet, the profit and loss and businesses generally. But it’s not completely formulaic and we’re open to evolving it.
Investment is the classic ‘Dave Brailsford cycling team’ world of marginal gains. Tiny differences compound up to massive improvements. And of course tiny mistakes compound into massive impacts on you returns over time.
One of your current biggest holdings is Royal Bank of Scotland, which is very much in recovery territory. What has driven your thinking with that stock?
RBS is in an industry that has had incredibly poor behaviour over a period of time and it takes a very long time to change. We’ve held banks for a long time and I’ve asked myself whether we’ve simply been slowly and incrementally looking at the next speed bump or whether we have genuinely been considering these investments in the context of longer term trends. I recently remodelled Barclays, Lloyds and RBS over 10 years to see in slow motion how the businesses crashed and evolved. The changes are absolutely enormous.
RBS, post the ABN Amro acquisition, had an investment bank with c.£300bn worth of risk-weighted assets but today it has one with £30bn. The amount of capital in those businesses now is three or four times what it was prior to the downturn. Whether that’s enough is another question, and they still don’t make enough money.
But let’s take a blank piece of paper and go through Porter’s five forces. What’s the competition for lending in the UK? Pretty benign, frankly. What are the barriers to entry like in retail and commercial banking? They’re enormous. It will take Metro Bank a fifty years to become the size of NatWest. What is the customer power like? It’s massive because even though everyone hates their bank nobody moves their account.
There are lots of things like this that make me think I don’t have the makings of a terrible business.There are lots of headwinds in terms of regulation, cyclicality and litigation but they are not impediments that stopped other industries outperforming. Regulation didn’t stop utilities doing well in the 2000s and litigation didn’t stop tobaccos going up incredibly.
We do this blank piece of paper exercise once a year, where we hide the amounts we own of each stock and ask how much we would hold today. Ninety percent of all ideas look quite similar when you reveal the amount you own, but some are quite different. The point of the exercise is to explore whether we’re behaviourally stuck around a percentage that we own. With banks, we found that we’d own more than we did.
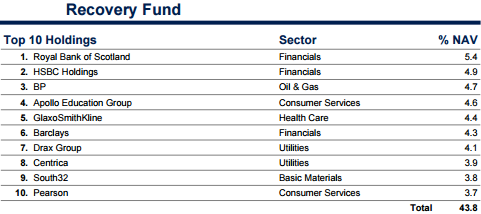
Schroder Recovery fund - Top 10 holdings: Schroders
As a contrarian, you know that there is a long list of behavioural traps that can force investors into making bad decisions. Are you conscious of those risks?
Just knowing about behavioural finance doesn’t absolve you from making those mistakes. In our team we often talk about process over outcome. Outcomes will come if processes are good. So do we have a process that allows us to avoid these kinds of biases? There is a trust element to how Kevin and I work in terms of sharing ideas. But are we too cosy and perhaps a bit afraid to say ‘I don’t like your idea’? How do you keep that tension to avoid confirmation bias? The blank piece of paper is a classic way to try and avoid that representativeness heuristic. Having said that, we’ve all got natural biases and we’re only human.
Coming back to the David Brailsford example, you don’t have to undo your entire human nature. You have to understand yourself and understand and stick with the style and then mentally suffer. When it’s underperforming you don’t have a lot of happy people in the team. Mentally, we need to understand ourselves and understand what it is that we do well - but there will always be errors.
What have you learned from the big successes and disappointments in the Recovery fund over the past 10 years?
I think the failures are more instructive, but we have had some wonderful successes with things that have made us multiples of our invested money. Take housebuilders like Taylor Wimpey. Back in 2009 you couldn’t force people into them because the house price fear was real. I think people do that at the moment with commodities. You’re negative on the commodity so you’re negative on the stock but in between those two things is the valuation that either discounts it or doesn’t.
Housebuilders back then were a great example of people being worried about the economy and house prices did fall in real terms by 15%, but Taylor Wimpey went up 400%. You don’t know it will happen that way but as part of a diversified portfolio, that’s why you buy it at that point.
With loss aversion of course, the winners don’t stick in your mind like the losses. So you remember the ones that went to zero, the ones where you got wiped out or the horrible capitulations where you were forced to sell in the rescue rights issue at a low level. They’re the Wagon Automotives, the Luminars and the Blacks Leisures of this world.
How do those individual disasters affect you?
As a fund manager, high conviction borders on egomania and overconfidence. As a result, the idea that you’d open yourself - Schroders - to being the biggest shareholder in Blacks Leisure when it goes bust, leaves you thinking ‘I don’t want to be in the papers for that!’
But that is the reason it’s attractive. When you get to those levels of distress, the valuation is so extreme because there isn’t a fund manager in the world that wants to touch it. With the Recovery fund, that’s why we never say never. When you’re dealing with that perception of distress you can make extreme amounts of money. Sometimes it’s not a sensible bet to take because the risk/reward isn’t in your favour, but often they can be very interesting ideas.
Special situations can occur anywhere in the market, but are there places that you won’t go with the Recovery fund?
Currently there are around 40 holdings but five or six of them are half-percent positions and on the way out. We need a very good reason to go below a £50 million market cap, although if something is very distressed we might look at it. My experience is that below that level there often isn’t enough upside to offset things like single-person founder risk, liquidity issues, narrowness of the business and single product companies.
With very small companies you have to be very careful because the risk increases very substantially. People obsess with ‘small’ because then it can go up a long way. But British American Tobacco was a £5bn company in 2003 before it went up 1,000% - a ten bagger. Kevin likes to use the phrase ‘deep value hiding in plain sight’.
Having said that, we do believe in the tail and we do believe that we’re looking at businesses that are falling very sharply and getting smaller, so we’re going to cap the size of the UK Recovery fund at £1 billion - it’s around £750m today. The incentive to keep funds open when money is coming in is very high and psychologically you feel like a hero after many years of toil. But taking the decision ahead of time to limit the fund will allow us to continue to access the small-cap end of the market that we think is important. Our global funds can be bigger because they are scaled off a bigger market cap. But in the UK, the cap will protect our ability to generate the performance over the next 10-15 years.
Finally, when you look at the market today, do you feel optimistic about the value opportunities that you are seeing?
Today is not a vintage period for value investors because it’s such a narrow market. I look at it like this: what is the average valuation of the things you pick from and then what is value versus growth within that? It’s not a great time for average valuations because the US is going through the roof. The UK doesn’t look very cheap to us because the averages are being skewed by some big, cheap stocks and some that are very expensive.
Having said that, the stuff that is cheap is despised and is value. When you look at banks, commodity stocks and food and drug retailers, there is no fund manager that wants to touch them. The disparity between what is cheap value and the rest of the market is increasing, so that’s a great time for value investors because nobody wants to do it. If you look at the half trillion of unit trusts in the UK invested in equities, less than 9% have more than 50% in value stocks. I feel that in this environment that if you can hold the line, the rewards to doing that are increasing. You have to understand that when the market is really on sale again, like in 2009, go big. Be picky, but buy and don’t drag your feet too much.
Today we’re in a different environment where it’s not psychologically hard to buy stocks, but it is psychologically hard to buy value stocks. Over the longer term, more difficult choices tend to lead to higher rewards. That bodes well for our deeply out of favour investment style.
If you’re interested in taking these value ideas further, Stockopedia members can view our pre-loaded ‘bargain’ and ‘value’ guru strategies. Among them are the contrarian approaches of David Dreman and the deep value methodologies developed by Ben Graham. Alternatively, you can use Stockopedia’s ValueRank as a starting point to finding potentially mispriced shares. You can find lists of high ValueRank shares in the StockRanks portal.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
13 comments
Just read this article after Ben linked to it. I think the following comment is worth some analysis:
But let’s take a blank piece of paper and go through Porter’s five forces. What’s the competition for lending in the UK? Pretty benign, frankly.
I don't think that is right. The mortgage market seems far from benign to me - it seems highly competitive. Not only are all the large banks competing strongly with each other (pushed in that direction by low returns on assets generally). There is also increasing competition from challenger banks - admittedly a small section of the market at the moment - and peer to peer lending platforms. Yields on unsecured consumer lending are very low at the moment. (If you want proof of this - read the transcript of Metro Bank's most recent analyst call, available on the investor relations section of their website. Metro's CEO basically says they aren't doing any consumer lending at all as the yield simply doesn't compensate for risk.)
The only area where I see the incumbents having a big lending advantage is in their risk weightings. Basically, they can use what is called "AIRB" - the advanced calculation of risk weightings - to hold less capital against their assets than the challenger banks. The challengers don't have the lending history to use AIRB. They are forced to use the standard method which means their risk weighted assets (and hence capital required) are much higher. However, that will not be a permanent advantage. It is temporary only.
I agree, however, that the large banks have a strong market position in deposit taking. They have very high customer retention and it appears that banks generally can only lose customers - not take them, That's an important distinction as it means that competitive intensity on the deposit taking side of the business is very low. RBS, Barclays and (particularly) Lloyds have very, very strong deposit franchises. Unfortunately, they all still have big legacy issues, IT problems, and overstretched balance sheets. I would like to invest in Lloyds, for example, but its loan to deposit ratio is still too high (over 100% last time I checked) so as a matter of prudence I'm not prepared to invest.
I am long Metro Bank (LON:MTRO), however - which I see as a good opportunity to invest in what is, potentially, the strongest deposit franchise in the UK. It also has a very clean balance sheet and I think in the years to come it will become apparent that Metro Bank (LON:MTRO) has the most profitable and predictable model of all the UK banks.
According my maths 127% in 10 years equates to CAGR just over 8% per annum. Take off any up front fees (say 0.5%) and adjust for active management fees, let's be kind and say 2% per annum, then a more realistic figure is around 80% over the decade. Admittedly it is article of faith that the majority of active FMs will not beat the market, so this chap has performed relatively well, but to laud him as some sort of master of the universe when the overall market has risen 72% is ridiculous.
Index classification aside, stressing your MO as a "Value" investor is nonsense, let alone a "deep" one. By definition every participant is a VI. Stock valuation is purely subjective, by way of example how can Jim Chanos act as counterparty to a Warren Buffett trade or vice-versa, as we know is the case from time to time.
Don't they deduct the management fees and costs each year so if it is up 127% in ten years that is net of fees?
Why anyone would buy RBS is completely beyond me. I'd rather stick the money in an Israeli binary options account!
That's kind of the point. Value is contrarian. When the majority believe a bombed out disaster like RBS to be gash, thats a good time to buy, subject to some due diligence checks.
How can you do due diligence on RBS when it's beyond the management's abilities? Some things are just too hard.
127% in 10 years = 8.5%pa. And that's starting counting from the previous market peak. This is the new normal Buffy! Do you think the market will do better than that over the next 10 years? I'm not sure.
Did I read that correctly? Up 127% in 10 years.
Wow, that's stunning. Must be all of, what... 2.5% a year CAGR.
I guess one could live happily on bread and water knowing that they outperformed other funds.
Buffy
"You’ve now been running the Recovery fund for 10 years, and it’s up 127.1% against a sector average of 72.5%."
This would imply the Recovery Fund has returned 8.5% p.a. over ten years vs 5.6% p.a. sector average.
This is a credible performance, possibly incredible if they've managed the assets in a low risk manner.
Hi Smallcapman, 2.5% a year CAGR over 10 years would produce a cumulative return of +28%, not +127%. The latter is equivalent to 8.5% a year CAGR over 10 years, as others have pointed out.
Think you did misread it, it's up 127% not 27%.
Interesting, will need to re read for personal investor lessons
Agreed!