Picks and Shovels U.S.: Why the 'AI savant' is betting against chips

“The race to artificial general intelligence won’t just play out in code and behind laptops. It’ll be a race to mobilize America’s industrial might.”
The author of this quote has been dubbed the savant of generative AI. And now he’s betting against its biggest stocks.
Leopold Aschenbrenner published the seminal Situational Awareness essay on Artificial General intelligence after being fired by OpenAI in 2024. He theorised that AGI, the ‘peak AI’ that can replicate practically any form of human cognition, would arrive far sooner than anyone thought.
He also prophesied that the barrier to mass adoption would shift away from computation and towards power, energy and materials.
Aschenbrenner then spun this anifesto into an investment fund backed by a string of tech superstars. Two years ago the fund started off with $255 million. This week, its 13F revealed a valuation of $13.7 billion.
The growth is astounding in itself. But what’s really interesting is the breakdown right now.
- The portfolio recently acquired put options in a string of semi-conductor manufacturers including NVIDIA (NSQ:NVDA), Oracle (NYQ:ORCL), Broadcom (NSQ:AVGO), Advanced Micro Devices (NSQ:AMD) and the Van Eck chipmaker ETF. Together, these chipmaker puts total more than $8 billion.
- Aschenbrenner is also long on a number of energy and infrastructure companies. Here are the seven biggest of these holdings:
| Ticker | Name | Stock Rank™ | Mkt Cap GBP (m GBP) | P/E TTM |
| APLD | Applied Digital | 33 | 8408.6 | |
| BE | Bloom Energy | 55 | 59788.1 | 1459.0 |
| CORZ | Core Scientific | 24 | 5486.2 | |
| CRWV | CoreWeave | 6 | 41140.2 | |
| IREN | IREN | 17 | 14025.3 | 47.3 |
| RIOT | Riot Platforms | 35 | 6664.3 | |
| SNDK | SanDisk | 71 | 153543.2 | 47.3 |
We can infer two things from this. Firstly, that Aschenbrenner is bearish on frontier hardware stocks, or is at least hedging. Secondly, that he's bullish on those companies further upstream (despite the modest StockRanks).
Aschenbrenner isn't betting on the companies making AI's picks and shovels. He's betting on the companies making the picks and shovels for the picks and shovels.
And when you look at the numbers, it's easy to see why.
Let’s build a portfolio of Aschenbrenner's seven biggest semi-conductor put options. We'll include ASML Holding NV (AMS:ASML) , which is technically a supplier rather than a maker, but it's still operating at the blast furnace of innovation. And we'll exclude Van Eck because we're focusing on companies rather than funds. Then let's compare this list against the seven long positions that we profiled just above.
The performance differential is staggering.
Over the past six months, the upstreamers have beaten the downstreamers by 175.48% to 76.30%. When we zoom out to 12 months, the chipmakers have returned 187% and the foundational companies have returned 851% (for context, the NASDAQ has returned 36% in the same period).
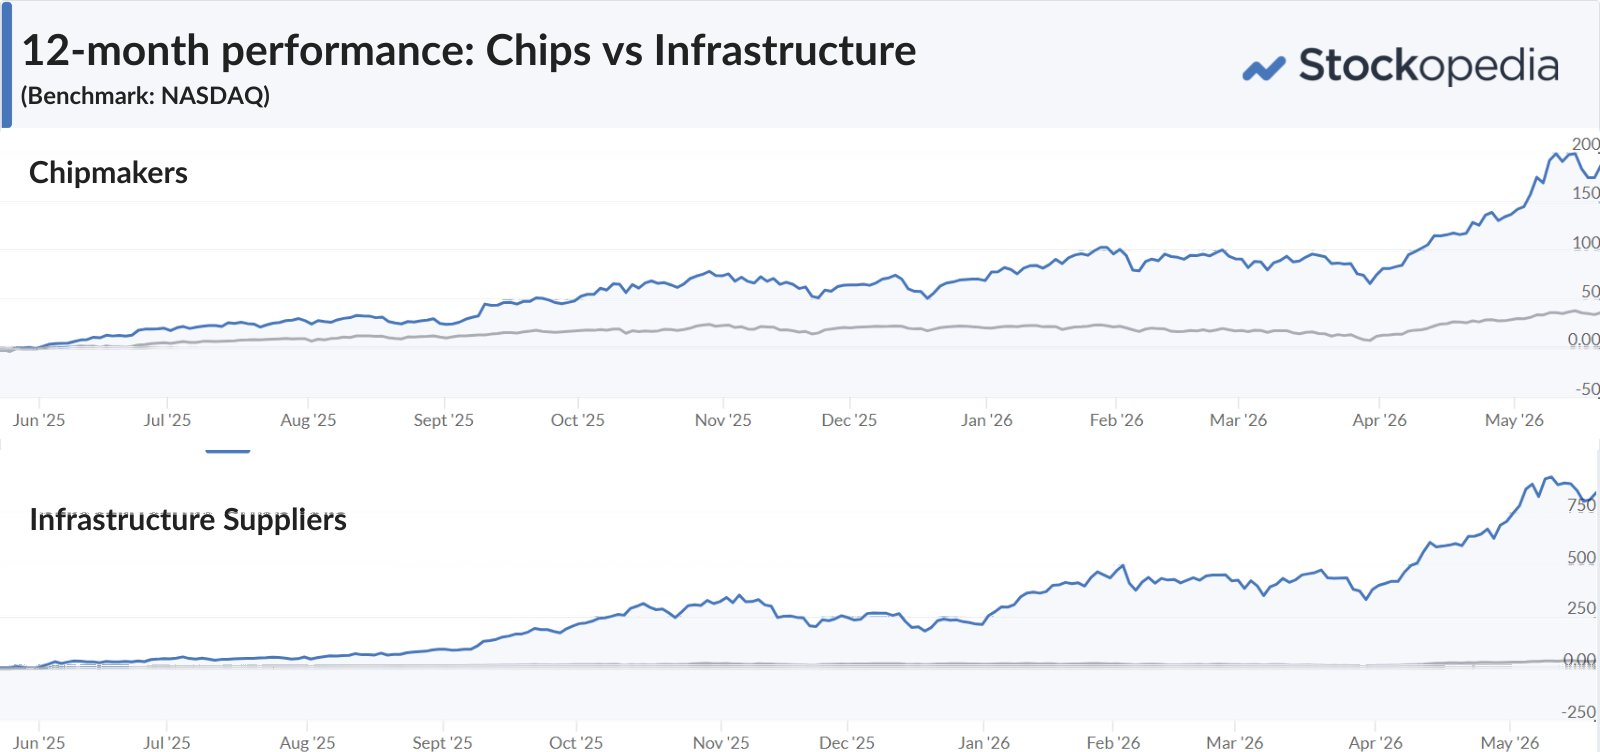
This stark disparity lights up a deeper trend. The locum of value in AI stocks is shifting beyond the geniuses at the frontier and moving upstream, to the companies driving their relentless pace of innovation.
Three themes driving this trend
1. Supply chain chokepoints
The frontier stocks face fundamentally greater challenges than companies further upstream.
Chipmakers rely on a tightly coupled stack of leading-edge foundry capacity, high-bandwidth memory (HBM), networking silicon, and advanced packaging. This chain is pockmarked with single-source parts and severely exposed to Chinese export controls on critical minerals; the recent Sino-American tit-for-tat illustrates its fragility. And delays are already mounting.
Nvidia’s Blackwell GPUs are facing severe delivery lags of 3 to 7 months, while technical challenges have delayed its next-generation Rubin architecture (more on this below). The company is striving to head off further issues by locking down over 60% of Taiwan Semiconductor Manufacturing Company’s advanced packaging capacity. But this merely fans the problem outward, capping the entire industry's physical throughput.
Upstream, the supply chains draw on mature, abundant industrial components like steel, copper and aluminium. Even better, companies like Vertiv Holdings Co (NYQ:VRT) which provides digital infrastructure and lifecycle services to data centers, operate localized manufacturing and delivery footprints spanning 130 to 150 different countries. If they rely on parts from East Asia, they can find a way round it if the chokepoint throttles.
2. The competition
Global spend on semi-conductors is forecast to pass $1 trillion this year. But beneath this glossy headline the chipmakers are being squeezed, from above and below.
Hyperscalers like Amazon, Alphabet, Microsoft, Meta and Oracle, hitherto the upstreamers’ biggest customers, are ploughing billions into their own Application-Specific Integrated Circuits (ASICs) to bypass frontier suppliers. These custom ASIC shipments are projected to grow at a 44.6% CAGR in 2026, far outstripping the 16.1% expected for general-purpose GPUs.
At the same time, more and more startups are springing into the space. Although funding has slightly waned from its 2023 peak, it’s instructive to note that there have been over 1,000 rounds since the Covid outbreak of 2020.
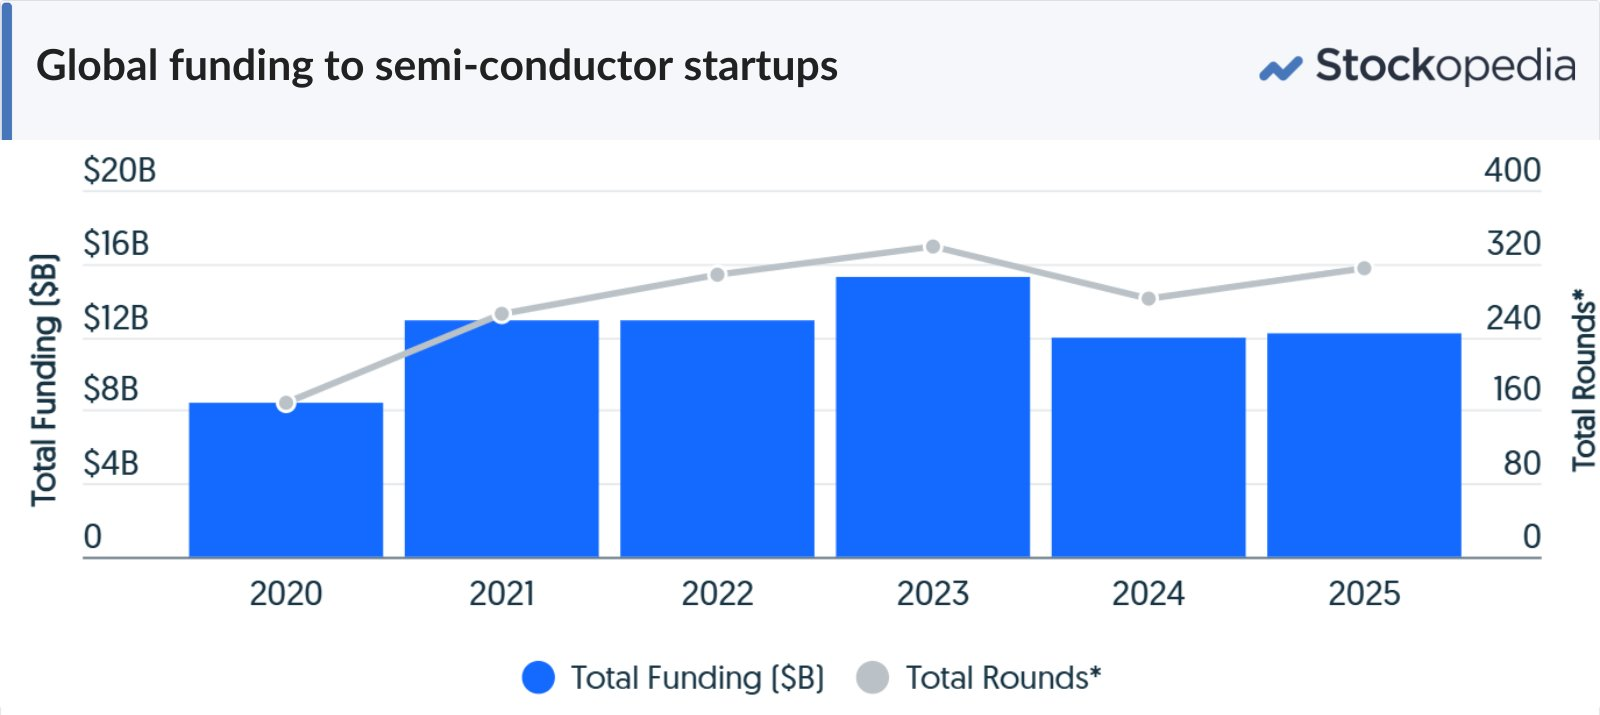
Source: Crunchbase
Broadcom broke cover in late 2025, saying that lower-margin custom processors were squeezing profitability. Even Nvidia is being eroded; analysts project that its command of the AI inference market could plummet from over 90% down to 20-30% by 2028.
Further upstream, the waters drain into forbidding moats, with massive barriers to entry. Bloom Energy has virtually no direct, scaled competition in on-site AI power generation, which enables them to provide roughly 10 years of secure revenue visibility.
In many cases, the moats are getting even deeper. Power management specialist Eaton (NYQ:ETN) has closed $11 billion in strategic acquisitions in the first quarter of 2026 alone.
3. The threat of obsolescence
Chipmakers are happy to kill their own product.
That much was made abundantly clear in March 2025 when Nvidia’s CEO Jensen Huang told his own AI conference that “when Blackwell starts shipping in volume, you couldn’t give Hoppers away.”
Blackwell is Nvidia’s new graphic processing unit. Hopper is the old one. The upgrade cost an estimated $10 billion, and Nvidia isn’t stopping there. Earlier this year the company unveiled Rubin, a successor to Blackwell with reportedly 10x the performance.
This certainly isn’t an isolated case. Across the board, frontier AI chips have an estimated lifespan of just 1 to 3 years, and each update imperils all the others. This trend is only going to get more pronounced as the chipmakers strain to outdo one another.
Conversely, upstream investments in power generation, switchgear, and liquid cooling represent durable, long-term physical assets. They don’t need to be replaced every 12 to 18 months and they provide a much more stable return on invested capital.
For investors seeking recurring revenues and reliable dividends, this certainty outweighs the glamour of the frontier.
Ultimately, each of these three themes comes back to Aschenbrenner’s theory: the primary limitation to scaling artificial intelligence is no longer delivering the innovation, but securing the materials, the electricity and thermal management to keep pace with it.
The downstreamers are the ones facing (and fuelling) this problem. The upstreamers are the ones who can solve it. And like those volatility winners we mentioned in a recent article, these suppliers don’t have to worry about which chipmakers win the semi-conductor war.
They’ll do just fine whatever happens.
A final word of caution
We’re definitely not saying that you should pump your money into Aschenbrenner’s stocks, or any other pick-and-shovel stocks. This piece is meant for education not advice, and it’s worth noting that the ‘Aschenbrenner seven’ list we presented earlier contains two Momentum Traps and one Sucker Stock.
So be sure to do your own research and take an informed decision on whether AI is for you. Even investors who swim upriver can run into trouble if they don’t come prepared.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Oops! Situational Awareness has had to be rescued this week by Ken Griffin's Citadel.
It's assets have fallen from $45 billion at the start of July to $10 billion now (but it's still up 80% on the year).
There does not seem to be much mention on Stocko that - Roundhill Memory ETF (ticker: DRAM) was launched 2nd April and doubled in less than two months ! Although it has recently down a bit its still up by around 132% since launch. Heavily weighted to just a few stocks.
@ DRAM does not have a linked ticker here as yet. And no I am not "clever" enough to have invested!
Tried to buy the US ticker about 6 weeks ago through IKBR but was blocked due to lack of KID document.
Could not buy it through IG group (LON:IGG) either, in my ISA.
If chips need to be replaced after 3 years but power equipment after decades then surely chipmakers make more money.
its all about supply and demand innit - will be intersting to see what happens if and when supply outpaces demand.
Thoughtful and encouraging but every time I click onto the links all the details are hidden . Is this a technical fault as I wanted to follow up on some excellent quality ? Rob
You probably haven’t paid for US and European access.
Thanks Ed C.
Stocko waking up to what is going on out there and not in "Little Britain". There are some onshore for sure but they don't make shoes, man sausage help or grinder salt etc etc.
The IPO of SpaceX 'landed' yesterday - the biggest IPO in history. Ok Filtronic (LON:FTC) but sorry where is the moat.
The IPO would not touch with a barge pole - but that would be a mistake. Just know when to get the hell out. These are great times).
It's a game, a serious game, but don't over think it. Have some fun. Best game in Dodge.
Of course Shoe Zone (LON:SHOE) will put shoes on Man on Mars.
The IPO game changed years ago. Once upon a time companies came to the market to raise investor capital and the investors often enjoyed the gains as the companies grew (sometimes they didn't and they were a car crash). Unfortunately the cash is all raised privately now and the company transitions from ugly duckling to swan off exchange. When there is nothing left to squeeze out they sell it to retail for a princely sum. Maybe SpaceX will be the exception to the rule, but I would encourage you to do your own valuation and come to your own conclusions.
There was an interesting article in the Telegraph about a couple of UK companies that have re-thought the approach to chips for AI and are proposing a non Digital analogue solution, which apparently provides fast (or more efficient) memory access and entails a more economical use of energy rather than needing multiple relays to the memory processor, burning power in the process.
Indeed swollen valuations in the IT industry can be prone to bubble pricking of this sort, so will be an interesting watch.
> The portfolio recently acquired put options in a string of semi-conductor manufacturers including [...] Oracle (NYQ:ORCL)
Is Oracle a semiconductor manufacturer?
Interestingly, the FT has published today an interview with James Anderson, formerly manager of Scottish Mortgage Investment Trust (LON:SMT) saying that the 'spoils of the AI war' will go to a few big hardware suppliers like NVIDIA (NSQ:NVDA) , ASML Holding NV (AMS:ASML) , and Taiwan Semiconductor Manufacturing Co (NYQ:TSM) ...
I wonder what the headlines will be in 5 years time?
Be aware that these big put positions on semiconductor names were published in his 13F form, and relate to his positioning some weeks ago before 30th March. So it is likely he was hedging into the sell off post US/Israel attack on Iran. The likelyhood he has remained short through the semiconductor rally in which the Semi ETF $SMH up +55% since 30/3/26 is low imo. If so he has lost a lot of money.