PPHE checks into London hotels

PPHE Hotel Group saw reported revenue increase by 11.8% in 2015 to €302.5m while normalised EPS jumped by a quarter to €0.99. The profit margin increased due to stronger room rates and an improvement in hotel occupancy. With an ambitious London expansion plan through to 2019 the group looks well placed.
At the end of 2015 PPHE Hotel Group operated 38 Hotels in 6 countries with 8,348 rooms. While the UK accounted for 2,791 rooms it generated two-thirds of the group’s EBITDA profit during the year.
PPHE Hotel Group’s expansion plans are focused on the UK with 1,402 rooms planned out of a total pipeline of 1,579 rooms. Given the importance of the UK the company is set to change its reporting currency to sterling going forward.
PPHE profile in 2015

Source: PPHE Hotel Group investor presentation
Within the UK the main area of focus for PPHE is London with 2,300 rooms in operation in 2015. This is expected to increase to 3,100 rooms in 2016 and will make PPHE one of the largest hotel operators in the capital.
Two new hotels are set to open in London this year in the form of Park Plaza Park Royal and Park Plaza Waterloo. An extension and reconfiguration of Park Plaza Riverbank will also complete in 2016.
PPHE’s London focus: Rooms in 2015 and projected in 2016

Source: PPHE Hotel Group
Looking out to 2019 the group expects to open two new art’otel’s in London – in Hoxton and in Battersea power station – with 512 rooms. However, these will not be fully owned unlike the London Park Plaza hotels opening this year.
London generated over half of PPHE Hotel Group’s profit last year and its importance is only going to increase in the coming years. The only other new hotel set to open through to 2019 is in Nuremberg, Germany.
PPHE’s hotel brands and pipeline

Source: PPHE investor update
London is a leading global city with an economy that is diversified across a range of sectors. The recent fall in the value of sterling will help to encourage more tourists to visit and the opening of Crossrail in 2018 will improve transport links.
The accountancy group PwC forecasts that revenue per available room in London will increase by 2.3% in 2016. This is driven by am increase in the average daily rate with London’s hotel occupancy expected to remain flat.
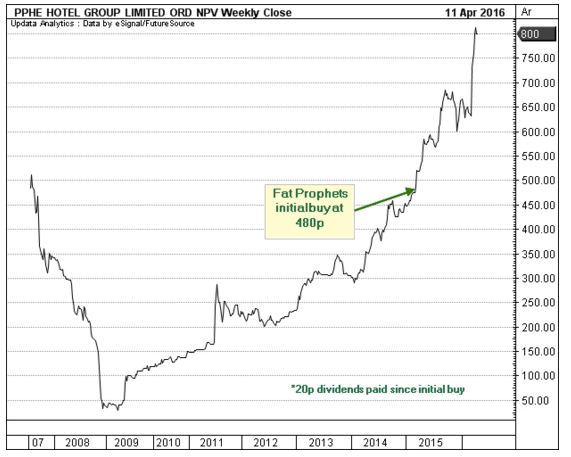
PPHE Hotel Group in focus
PPHE Hotel Group is listed on the main market of the LSE and has a free float of only 26%. The company is founder managed and controlled but appears to have a succession plan in place in the form of deputy CEO Chen Moravsky (46).
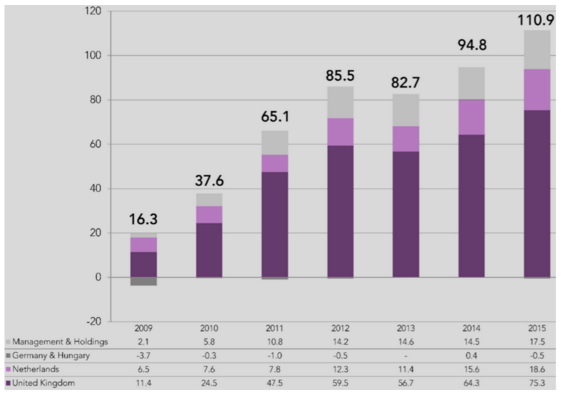
While investors may overlook the business the financial track record since 2009 is impressive. EBITDA has increased from €16.3m to €110.8m on the back of a recovery in end markets and profit growth in the United Kingdom.
PPHE EBITDA generation €m
Source: PPHE Hotel Group
With the hotel sector a capital intensive business PPHE’s net debt came in at €400m at the end of 2015 with the net debt to EBITDA ratio at 5X. While the ratio is high it will improve as new hotels boost EBITDA profit.
PPHE’s book value of €264.8m at the end of 2015 is worth around 637p a share but the assets are valued at cost. The market value of the mainly hotel assets could lift the book value per share to double the official figure.
PPHE Hotel Group in 2015
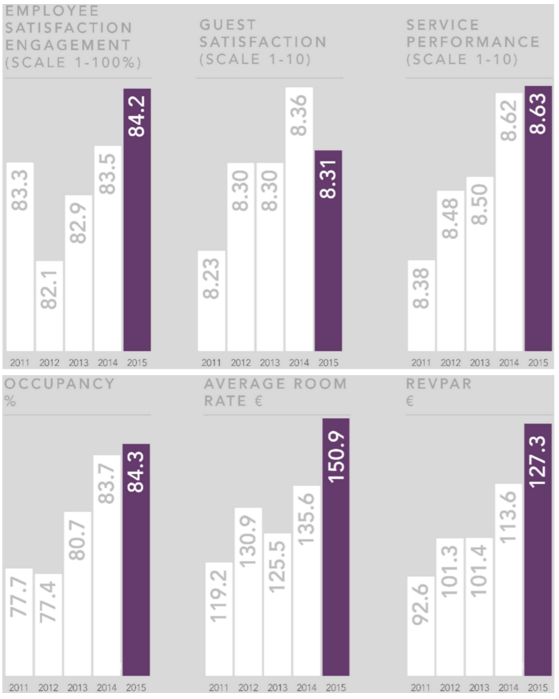
PPHE’s Hotel Group’s “soft” performance indicators saw progress with employee satisfaction and the service performance improving. Guest Satisfaction fell back but this was against a particularly strong result seen in 2014.
These readings suggest that PPHE will see solid repeat bookings and room rates in the years ahead. In 2015 PPHE’s hotel occupancy rate improve to 84.3% from 83.7% in 2014 and the average room rate increased to €150.9.
2015’s performance metrics
Source: PPHE investor update
While the bulk of revenue and profit is generated from the UK the reporting currency has been the euro. In 2015 the strength of sterling boosted revenue earned in the UK in euro terms.
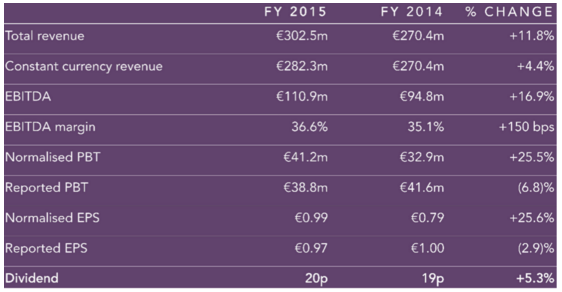
PPHE’s constant currency revenue was up by 4.4% in 2015 but a currency boost of 7.4% meant that reported revenue was up 11.8%. The EBITDA margin improved by 1.5% to 36.6% and normalised EPS was up 25.6% to €0.99.
PPHE Hotel Group 2015 results
Source: PPHE Hotel Group investor update
In terms of the valuation and the €0.99 of normalised EPS in 2015 translates into around 80p at current exchange rates. The consensus P/E forecast for 2016 is 12.2X and is expected to fall to 9X in 2017.
Summary
PPHE Hotel Group is becoming increasingly focused on the London with four new hotels set to open in the city through to 2019. This bodes well given the strength of the economy in the UK capital.
The company’s track record since 2009 is strong and the recent “soft” performance indicators have been improving. Improving service levels should support hotel occupancy and average room rates going forward.
While the share price has seen strength over the last couple of years the valuation is not demanding. The forecast P/E for 2017 is only 9X and the market value is likely to be at a meaningful discount to the market book value of assets.
The key risk is that the London hotel market experiences a drop in demand due to economic weakness. This would hit both hotel occupancy and room rates and result in a profit slump at PPHE Hotel Group.
This report was produced by Fat Prophets Senior Research Analyst, Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
£PPH was also one of the stocks discussed in a positive light on Paul's recent interview with Francis Kershaw.
Here's the link:-
http://qualitysmallcaps.co.uk/investor-interviews/...
ragehammer - I agree the Croatian deal looks interesting. It should enhance earnings per share and the growth prospects.
Also the refinancing of Park Plaza Victoria was interesting. This was done at a 10-year fixed rate of 3.41% (secured). What is notable is that as part of the financing this one hotel was valued at £161.5m. it is likely that the refinancing was done at improved interest rates otherwise why do it? Other motivations might include to diversify the lenders to the group.
The 30th March update also said that PPHE is looking at financing proposals for other London hotels. So the refinancing process should help bring down the cost of debt across the group.
The key attraction for me with PPHE Hotel (LON:PPH) is the real value of the hotel assets being substantially more than the book cost. Finncap estimates the fair value is around £15.37 per share, although they have then applied a 20% tax rate and a 20% risk factor to come up with their price target of £10.80.
The business is wonderfully run as can be seen from the non-financial KPI's above and is still cheap on an earnings basis irrespective of the asset upside I've mentioned above. It also pays a decent and well covered dividend while you wait for the asset valuation to be realised in the price. 2016 is a transformational year with significant expansion of the London portfolio in particular.
Recent announcements include the buying out of the JV partner in Croatia and the refinancing of Park Plaza Victoria (to be followed by other London hotels), substantially reducing interest costs and freeing up capital for continued investment and potentially returns to shareholders in due course.
Key risks include economic recession (travel is usually the first and one of the hardest hit industries) and a significant terror attack in London which would impact demand and short term sentiment significantly.
I was close to buying this back in Jan 2013, however I thought the debt levels, particularly when compared to other hoteliers was too high. What a shame, I missed out on nearly 400% gains!