Proven quality in Software and IT: Moneysupermarket, FDM and Dotdigital

The UK tech sector is booming. Tech Nation’s 2020 report shows that investment in this part of the market surged by 44% in 2019 to some £10.1bn - more than the amount spent in France and Germany combined.
So it makes sense to look for investments in the UK-listed Software and IT Services industry group. Here we have 128 listed Software and IT Services companies to analyse. I’ve highlighted three below: Moneysupermarket.com (LON:MONY) , Fdm (holdings) (LON:FDM) , and Dotdigital (LON:DOTD) . I’m sure there is plenty of opportunity in this space though, so other suggestions are appreciated.
Looking at the group in aggregate there is a clear High Flyer profile:
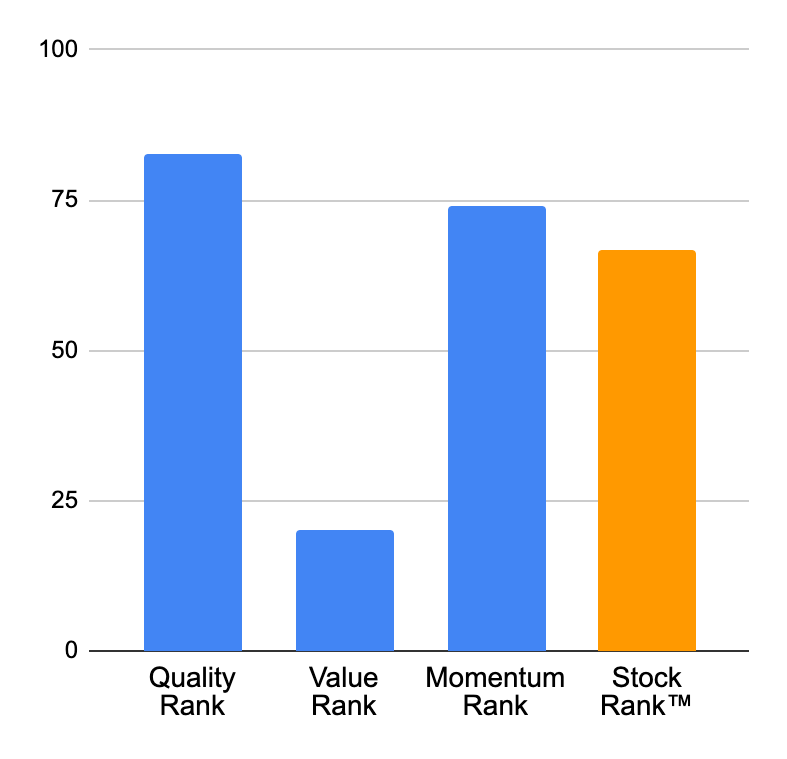
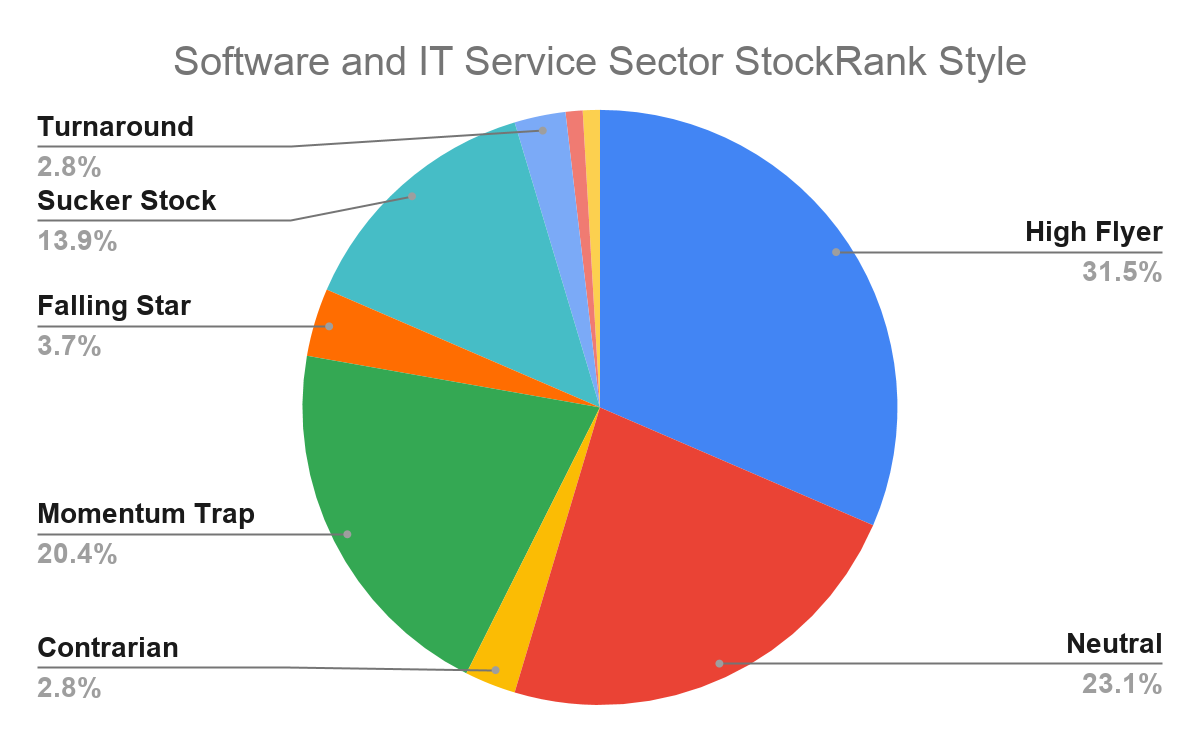
A lack of traditional value is to be expected in this part of the market. But when you dig down into the Styles, a much more characterful and eclectic picture emerges: for every High Flyer you’re more likely to find a Momentum Trap, Falling Star, or Sucker Stock.
The group begins to come to life now.
A breakdown of the RiskRatings further confirms that we should tread carefully in this industry. There are high returns to be had, but there is a lot of volatility as well. In fact there are no Conservative stocks, and the large speculative weighting skews the set firmly towards the more volatile end of the market:
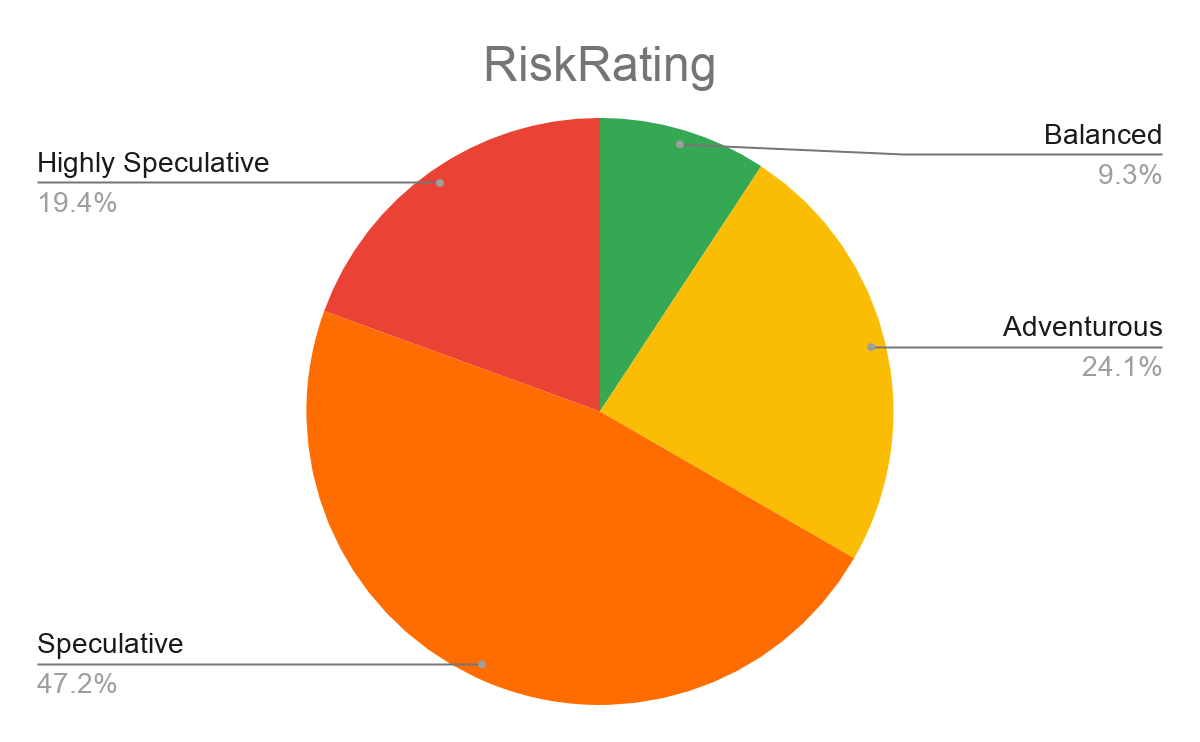
It appears as though fortunes can be both made and lost in Software.
Moat or mirage? Refining the sample
That might in part be because it’s so hard to make moats in this sector. The innovation and evolution is so intense that seemingly incredible bits of hardware and software can soon become obsolete. Today’s high margin must-have can be, by tomorrow, just another binned Blackberry.
High profit margins tend to have an expiry date - if you’ve found a good meal hungry rivals will muscle in.
Some companies can defy gravity and maintain high margins for great periods of time though - and it is these companies that go on to create a tremendous amount of value for their stakeholders.
If an economic moat is a durable competitive advantage, we can think of that in two dimensions: there’s depth (how much money the firm can make from its moat?) and there’s width (how long can those above-average profits be sustained?). Technology firms sometimes have deep but narrow moats, meaning they can be highly profitable for a short period.
So what’s the best way to approach this group?
In a bid to sift the moats from the mirages, I have screened for two long term quality metrics and one compound earnings growth figure:
- Long term ROCE above 10%
- Five-year operating margin above 10%
- Five-year earnings per share CAGR above 10%
These long term criteria might mean I miss out on some more high-risk, high-return options, but I’m exchanging that for the security of proven growth and profitability. It brings the sample down from 129 stocks to just 14:
Name | Mkt Cap m GBP | ROCE % Long Term Avg | Op Mgn % 5y Avg | FCF / Sales % TTM | QM Rank | EPS CAGR % 5y |
5220.21 | 48.04 | 60.82 | 52.08 | 75.00 | 69.34 | |
5020.34 | 1796.00 | 73.24 | 63.41 | 96.00 | 15.07 | |
1717.31 | 46.40 | 29.40 | 25.36 | 89.00 | 12.17 | |
1301.17 | 10.04 | 11.67 | 18.82 | 90.00 | 62.51 | |
980.54 | 59.53 | 19.07 | 16.14 | 98.00 | 17.87 | |
867.23 | 44.06 | 15.16 | 8.97 | 89.00 | 13.01 | |
464.10 | 28.32 | 27.45 | 20.87 | 59.00 | 13.05 | |
309.80 | 25.72 | 24.41 | 19.95 | 96.00 | 25.22 | |
224.79 | 32.97 | 10.04 | 2.52 | 76.00 | 12.22 | |
103.72 | 12.26 | 15.74 | 6.33 | 85.00 | 33.07 | |
95.82 | 17.70 | 18.13 | -1.18 | 83.00 | 36.20 | |
70.73 | 12.68 | 11.03 | 15.76 | 99.00 | 29.44 | |
30.65 | 27.24 | 12.89 | 12.78 | 78.00 | 11.38 | |
22.00 | 11.57 | 19.55 | 48.32 | 66.00 | 73.85 |
This subset has much-changed composite characteristics. Interestingly, it has a lower StockRank than the wider sector:
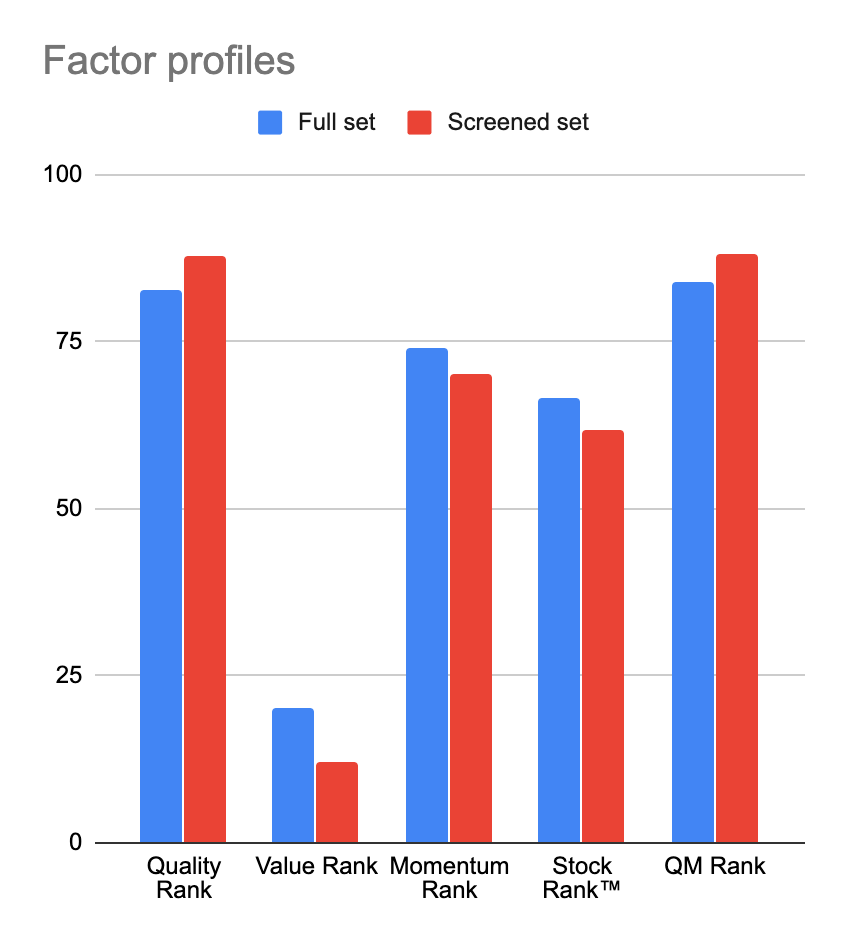
It has a higher QM Rank (of 88 vs. 84) though, which is perhaps is a more appropriate measure for Software stocks (since traditional value metrics often fail to reflect economic reality).
The spread of Styles is much more favourable - now nearly three quarters are High Flyers (compared to just 31.5% for the industry group as a whole), with the remainder Neutral and with one Falling Star:
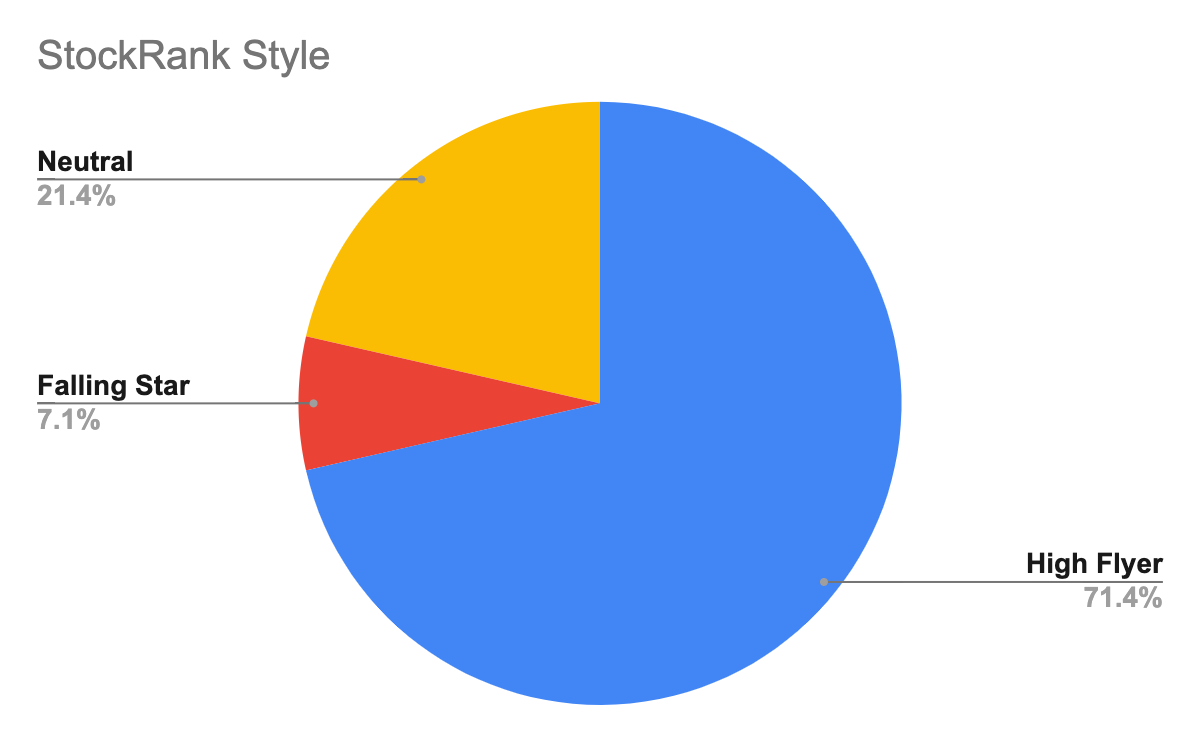
Not only has the StockRank Style improved - volatility has also been greatly reduced. Whereas previously we were exposed to more than two-thirds Speculative and Highly Speculative, there is now a far greater weighting towards Balanced and Adventurous stocks.
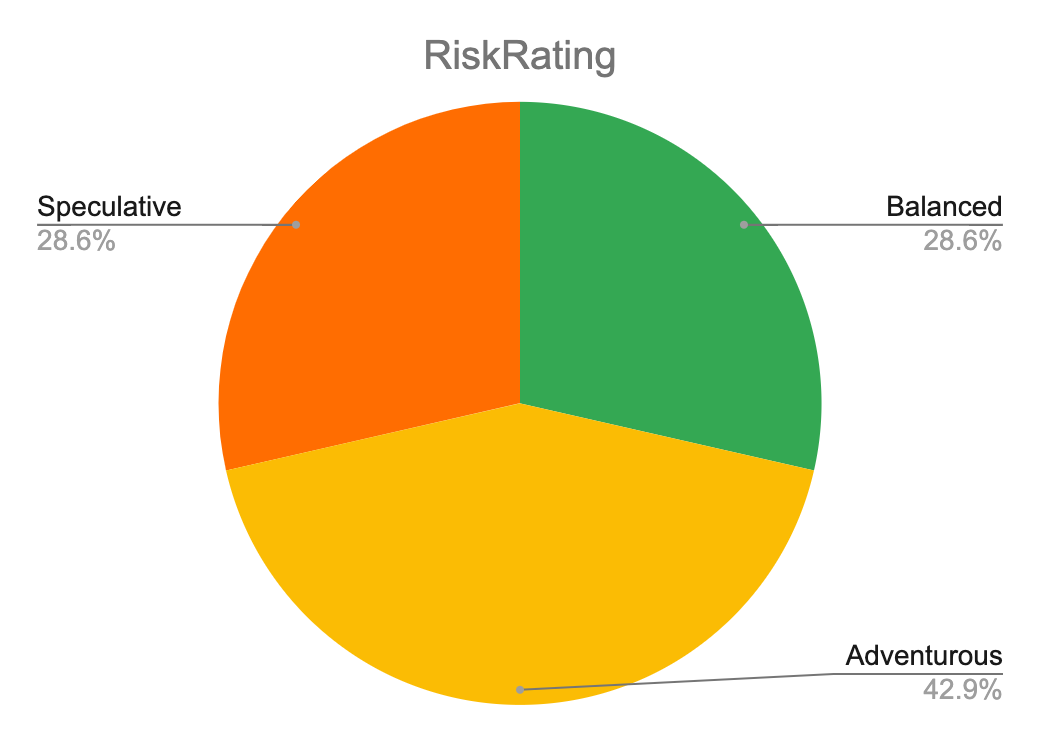
So screening for long term profitability has resulted in a pricier but higher quality collection of companies that exhibit lower volatility over time. On balance, I think it makes for a much stronger set of stocks.
I’ve taken a closer look at three of them.
Moneysupermarket.com (LON:MONY)
- Market cap: £1,717.3m
- Long term ROCE: 46.4%
- Five-year operating margin: 29.4%
- Five-year earnings per share CAGR: 12.17%
What it does
Moneysupermarket.com is a data-driven marketplace that helps customers save money. Its model is highly scalable, as it receives a fixed marketing fee from the product provider for successful sales.
It has several strong brands that drive this business:
MoneySuperMarket is the UK’s leading price comparison website.
MoneySavingExpert is the UK’s biggest consumer finance website.
TravelSupermarket compares travel deals.
Decision Technologies Limited is a leading home communications and mobile phone comparison business.
Growth and valuation
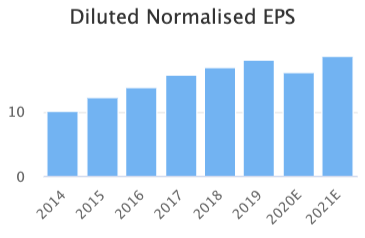
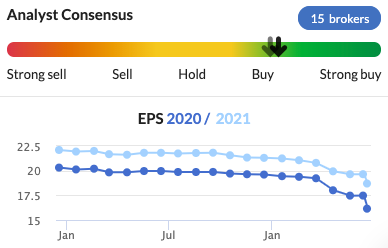
MONY has high returns and margins over time but earnings are set to dip this year before resuming gradual growth in the year after.
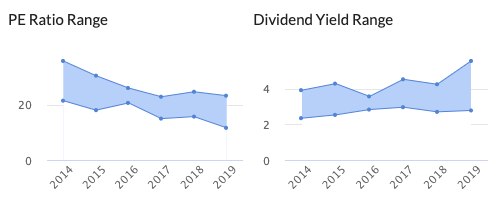
Moneysupermarket shares appear to be cheaper than FDM and Dotdigital. There are signs of value on show here, particularly given MONY’s proven track record:
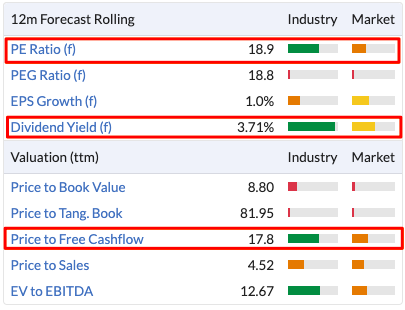
The group has suggested it will maintain its dividend payment, so this should help anchor the valuation in the near term. I wonder about earnings forecasts, though. The broker trends are not encouraging:
That said, MONY’s share price has gone nowhere over the past few years despite solid operational and financial growth. As a result of this, it looks better value than it has done in the past.
Latest statement
In all honesty, the tone of this update is weaker than I expected, although the fundamental picture is probably fine.
Insurance (£188.4m of revenue, c48%):
- Market-wide Car insurance search volumes declined by 22% year on year in April and lower premiums means the likelihood of a return to premium inflation in 2020 is low, although conditions have somewhat normalised. This is the largest insurance vertical and its results are resilient.
- Other key insurance channels were hit: UK residential housing transactions fell by over 55% year on year in April, but this should be improving now as the market reopens.
- Travel bans continue to mean almost no demand for travel and travel insurance products. This is the worst result, but it is also from the smallest part of the group’s Insurance arm.
Money (£86m of revenue, c22%):
- There has been a “very significant” reduction in the attractiveness and availability of credit and banking products as lending criteria have tightened and interest rates have fallen. This is not expected to change in the immediate future.
- Market-wide search demand for credit products was down 37% year on year for loans and cards combined in April as consumers postponed significant spending.
Home services (£68.6m of revenue, c18%):
- This division was better, with strong growth in energy switching and broadband.
MONY has an “Other” segment which generates the remainder of revenue.
Conclusion
This could be a good income and “QARP” candidate (quality at a reasonable price). I don’t have a view on near-term trading prospects.
What I can say though is that MONY has a very cash generative business model, modest net debt, solid liquidity metrics and reasonable Professor scores. Its prospects are underpinned by high levels of investment and widely recognised brands.
It is nowhere near as expensive as some of the other candidates on this list either, with a forecast PE ratio of 18.1x. That’s not much in my view, given its track record of growth in both earnings and dividend payments.
FY19 | FY20(e) | FY21(e) | |
EPS normalised | 18 | 16.1 | 18.7 |
Share price | 332.4 | 332.4 | 332.4 |
PE ratio | 18.5 | 20.6 | 17.8 |
The near term outlook is mixed, and the company continues to suspend guidance but maintaining the dividend is a sign of confidence in its own long term prospects.
All in all, this looks like a highly profitable and cash generative business with growth potential and a useful yield.
FDM (LON:FDM)
- Market cap: £980.5m
- Long term ROCE: 59.53%
- Five-year operating margin: 19.07%
- Five-year earnings per share CAGR: 17.87%
What it does
FDM connects IT and business professionals with clients across a number of sectors and has centres in Europe, North America and APAC.
The Group’s principal business activities involve recruiting, training and deploying its own permanent IT and business consultants (‘Mounties’) at client sites. It’s an international operation, with:
- 50% of “mountie” revenue coming from the UK (£134.2m as of FY19),
- 36% coming from North America (£95.7m),
- 8% coming from Asia-Pacific (£22.3m), and
- 6% coming from EMEA (£22.3m).
I’m not sure quite what stops other competition muscling in on margins in the long term, but for now FDM is carving out a very profitable niche as outsourced IT help.
Growth and valuation
As with other companies on this list, an asset-light, profitable business model has led to very high returns over the years. The group has managed to steadily grow earnings over a long period of time.
The lockdown does appear to have impacted FDM’s business more than Moneysupermarket or Dotdigital. Earnings forecasts have been reduced meaningfully, from 40.5p at the start of the year to 31.1p currently - a 23% reduction.
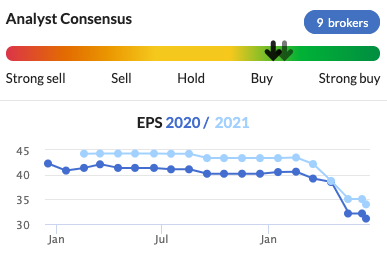
At 27.5 times forecast earnings even after this 23% reduction in consensus predictions, you’re not getting FDM for cheap.
Latest statement
For now, it does sound like FDM is at least on course to meet revised market estimates:
Following the Group's First Quarter Trading and Covid-19 update given on 30 April 2020, the Group has traded comfortably in line with the Board's revised expectations. Mounties placed with clients at 15 June 2020 were 3,706 (15 June 2019: 3,812 Mounties placed with clients). The Group's balance sheet remains strong with £53 million of cash and no debt.
Conclusion
FDM looks to be profitable, with good operational momentum and increasing geographic diversification.
The company has been steadily growing revenue and profits for a long time and it is usefully cash generative, with a cash-backed balance sheet and lots of liquidity. It is expensive, but, in terms of its typical PE ranges, it is actually more modestly valued than it has been in the past:
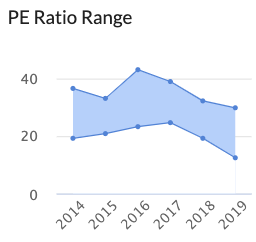
That said, given the forecasts, I just don’t see a whole lot of value here right now particularly with earnings set to dip.
FY19 | FY20(e) | FY21(e) | |
EPS normalised | 37.2 | 31.1 | 34 |
Share price | 898 | 898 | 898 |
PE ratio | 24.1 | 28.9 | 26.4 |
I have yet to see quite what makes FDM special and justifies its margins. Perhaps, like Softcat, it is the culture and customer support?
Dotdigital (LON:DOTD)
- Market cap: £309.8m
- Long term ROCE: 25.72%
- Five-year operating margin: 24.41%
- Five-year earnings per share CAGR: 25.22%
What it does
Founded in 1999 as a web design agency, Dotdigital has developed a popular email marketing suite of products for digital marketing professionals. This expanding market offers plenty of scope for growth.
The Dotdigital Engagement Cloud allows marketers to import data, build segments and triggers, and create relevant marketing campaigns that engage customers across various channels.
Growth and valuation
It’s full steam at the company, which is set on strengthening relationships with partners in North America, and expanding dedicated sales teams across the North America, APAC and EMEA regions.
The rate of earnings per share growth has consistent in the past and looks to be impressively resilient now:
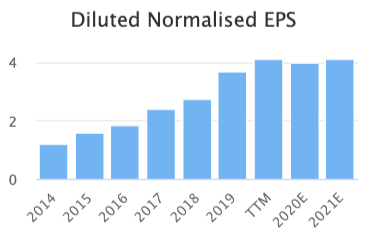
This is down to the group’s high levels (c90%) of recurring revenue.
Meanwhile, the group has bags of liquidity, net cash on the balance sheet and is cash generative. Even after everything that’s happened this year, DOTD is still forecast to grow profits.
As with FDM though, Dotdigital is expensive at 25x forecast PE. That’s a lot given the forecasts for growth going ahead, which are negligible.
FY19 | FY20(e) | FY21(e) | |
EPS normalised | 3.67 | 3.98 | 4.11 |
Share price | 103 | 103 | 103 |
PE ratio | 28 | 25.9 | 25.1 |
What the group does have, though, is an apparently very popular marketing platform, with sticky customers and recurring revenue built into the model. On initial impressions, this puts it ahead of FDM for me, and better explains the high multiple.
Latest statement
Sounds good:
The business has 90% recurring revenues, (of which 90% is contracted), giving us strong future revenue visibility. We achieve a high operating margin and enjoy good operating cost flexibility. Cash at the end of March was on target at £22.0m with zero debt. Customers come from a diversified mix of industry types and company sizes, with no client representing more than 1.5% of revenue. Stress test modelling gives a high level of confidence that we could, if required, maintain our business model through a prolonged global downturn.
The long term outlook for the business is also positive. It is well placed to take advantage of the continued growth within the marketing automation market, which is predicted to grow to $25.1bn by 2023 according to Forrester Research
Conclusion
Dotdigital may well have potential. Ideally, I’d like to see more forecast growth for such a premium rating - but perhaps “resilient” is the new “growing”?
FDM I’m sure can continue to grow as well, but I have yet to see what separates this company from potential competitors.
Of the three, Moneysupermarket.com and Dotdigital strike me as worth a closer look.
MONY has a scalable platform, known brands, proven quality, is maintaining its dividend, and is more cheaply valued than the others. It could be a strong long term growth, income, and quality candidate.
I place Dotdigital ahead of of FDM as well, given its attractive mix of recurring revenue, high margins, low customer concentration and possibly higher growth potential. But perhaps you disagree?
This is just a small fraction of the opportunities on offer in this part of the market - if there are any other stocks in this group worth investigating, it would be great to hear some names.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Jack – I found a summary link to the Forrester 2023 market prediction you mention, which is suggesting marketing automation growth of 14% CAGR from 2017 to 2023. dotDigital (LON:DOTD) have just had a 12% “organic” sales increase, in line with this. What I like about this level of annual market growth and recurring revenue is that a company like dotDigital (LON:DOTD) has to do nothing special to achieve a double digit annual sales increase. As a consequence of reading the market report summary, have just bought some more!
https://www.marketingdive.com/news/forrester-marketing-automation-spend-will-reach-25b-by-2023/522900/
I note also in today's £DOTG update that: Dotdigital was independently rated as a "Strong Performer" in the 2020 Forrester Wave Email Marketing Services Providers Report".
Thank you Jack for a great analysis. I enjoyed reading through your structured approach. I hold Fdm (holdings) (LON:FDM) and having spent 7 years working in a big 4 consulting practice my thoughts around their competitive positioning are:
On balance I'm happy to hold this investment as it continues to publish robust results given the economic climate, but I'm wary of the potential downsides from Government spending cuts and a prolonged economic down turn.
Jack. Thanks for yet another informative article. I invest in this sector quite a lot. Towards the more speculative end of the spectrum, I like IDOX. The forecast to 31/10/2020 is for 2200% EPS growth, and it's in a bit of a turn around situation.
As far as FDM is concerned, I believe that the moat arises because they train all their "mounties" ( consultants ) themselves from scratch, and the quality of their selection procedures and training is considered to be very good.
Please can you tell us what the "Professor score" is about that you mention for MoneySupermarket ?
Thanks re. Idox (LON:IDOX) - I've probably excluded some interesting turnaround situations given the long term profitability criteria I used... I'll check out the StockReport.
Professor scores - maybe this is just a phrase I use in my own head! I thought it was more of a thing... I just mean the F-Score, Z-Score, and M-Scores, which I believe were all formulated by various professors based on their academic studies.
I'm with you on Idox (LON:IDOX) Warrant. I own it and somehow missed the news of the forecast. Note it got short shrift from Paul the other day too.
Postscript - added to my holding on the back of it
Thanks for the excellent review, Jack.
I hold AUTO.L, RMV.L and MONY.L currently, plus SGE.L not mentioned above.
If you like the relatively high growth prospects, low capital requirements and high relative earnings safety that comes with subscription based models - but dont like the bumpy ride of some individual stocks then the iShares ETF IITU.L might be worth a look-see (although not at these extended prices, obvioulsly). This gives exposure to the far larger set of USA S&P500 IT companies.
https://www.ishares.com/uk/ind...