Reckitt Benckiser wins with Powerbrands

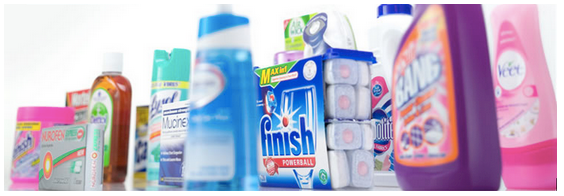
Reckitt Benckiser shows that the best investment opportunities can be right under our nose. Nineteen “Powerbrands” generated 80% of net revenue in 2014 and include names like Finish, Cillit Bang and Nurofen. With strong market positions and attractive margins the company has kept investors in good health.
According to research in “What Works on Wall Street” (2012, P545) the best performing long-term sector has been consumer staples. This area encompasses Tobacco, Beverages, Food and Home & Personal Care.
Consumer staples feature low cost, every-day products that tend to see demand hold up when economic conditions are weak. Companies in the sector usually own strong brands that have withstood the test of time.
Challenges include supermarket own brand competition, changing consumer tastes, regulation, tax and weak growth. These issues have, though, generally been less harmful than the headwinds facing sectors such as banking.
Consumer staple companies have been able to retain and compound value over the long-term. This is in contrast to sectors that deploy significant financial leverage, see leadership positions change and face cyclical demand.
Reckitt Benckiser’s Powerbrands
Source: Reckitt Benckiser website
FTSE 100 consumer staple groups include Imperial Tobacco, British American Tobacco and the alcoholic drinks giants SAB Miller and Diageo. The two remaining FTSE 100 consumer staple groups are Reckitt Benckiser and Unilever.
All six firms have generated significant shareholder value over the long-term and as such merit investor consideration. However, tobacco and beverage companies are potentially at risk from changing tastes, taxes and regulations.
This leaves Reckitt Benckiser and Unilever as arguably the least risky consumer staple companies in the FTSE 100. Both face the challenge of supermarket own brand competition but have managed to hold their own.
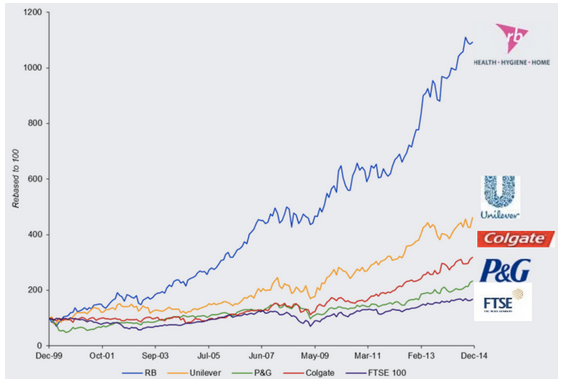
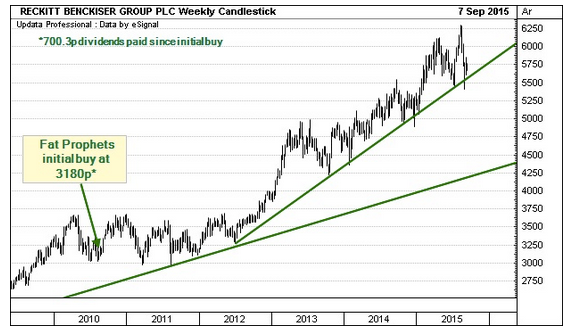
Looking at Reckitt Benckiser more closely and the long-term share price performance has been spectacular. With the forecast P/E rating for 2016 at 22X the issue now is whether it is worth getting on board.
Reckitt Benckiser has outperformed its peer group
Source: Reckitt Benckiser investor fact sheet
Reckitt Benckiser’s Powerbrands
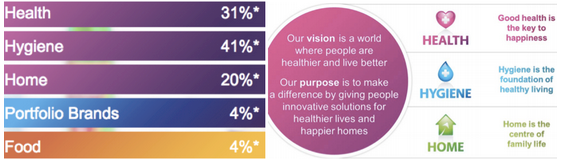
Reckitt Benckiser has 19 “Powerbrands” which generated 80% of revenue in 2014. The two main divisions are Health at 31% of 2014 revenue and Hygiene at 41% of revenue while Home came in at 20% and Foods at only 4%.
The strategy of Reckitt Benckiser is to focus on higher and higher margin divisions of Health & Hygiene. The group is also looking to generate a “more evenly balanced” revenue stream between developed and emerging markets.
2014 revenue generation & mission statement
Source: Reckitt Benckiser website
The Health Powerbrands are Durex, Gaviscon, Mucinex, Nurofen, Scholl and Strepsills. Durex is the world’s top condom brand, Mucinex is the second largest cold and flu brand and Strepsils is the leader in medicated sore throat treatment.
In Hygiene the Powerbrands are Cillit Bang, Clearasil, Dettol, Finish, Harpic, Lysol, Mortein and Veet. Finish is the global leader in automatic dishwashing while Dettol and Lysol are the global leaders in germ kill.
In Home the Powerbrands are Air Wick, Calgon, Vanish and Woolite while the Food division’s Powerbrand is French’s mustard. Vanish and Calgon are the global leaders in fabric treatment and water softener respectively.
Reckitt Benckiser’s geographic mix
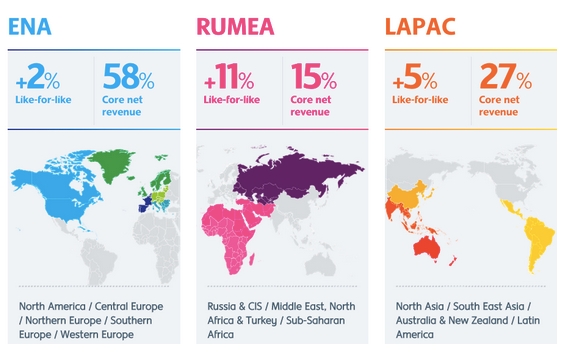
Looking at the geographic mix and 58% of core net revenue in 2014 came from European and North America (ENA). The remaining 42% came from emerging markets but this figure does include Australia and New Zealand.
In 2014 North American and Europe saw only 2% revenue growth while the RUEMA countries saw 11%. In Asia the LAPC countries saw 5% like-for-like revenue growth in 2014.
Reckitt Benckiser 2014 revenue generation
Source: Reckitt Benckiser website
2014 financial performance
Reckitt Benckiser spun out its pharmaceutical division Indivior (previously RBP) in December 2014 on the LSE. As such results are stated excluding the contribution this division made in 2014.
In 2014 the group saw like-for-like sales growth of 4% and constant currency revenue rose by the same amount. However, reported revenue fell by 5% to £8.84bn due to do foreign exchange headwinds.
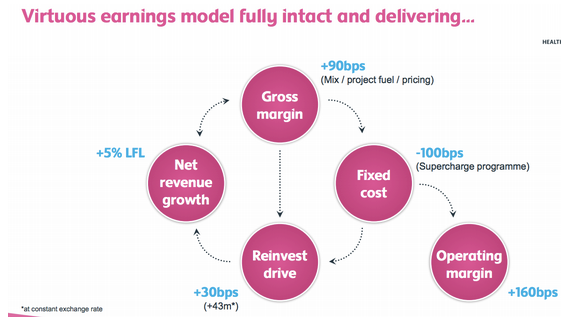
Reckitt Benckiser managed to increase its gross profit margin by 1% and its operating margin by 1.6% to 24.7% in 2014. This helped lift adjusted earnings per share by 4% to 230.5p despite the fall in reported revenue.
In the first half of 2015 like-for-like net revenue growth come in at 5% and constant exchange rate revenue was up 4%. Foreign exchange headwinds remained in place with reported revenue up by only 1%.
The gross margin saw a 0.9% improvement to 57.6% while the adjusted operating margin rose by 1.6% to 21.9%. Adjusted earnings per share rose 7% to 99p and the interim dividend came in at 50.3p due to a 50% payout policy.
The ongoing cost optimization programme for cost of goods sold (COGS) is called Project Fuel. The group also has Project Supercharge which is create a simpler and more agile company, reduce costs and drive through efficiencies.
Source: Reckitt Benckiser first half presentation
Summary and valuation
With a gross profit margin at 57.6% in the first half of 2015 and an operating margin at 21.9% this is a high quality business. The shift towards higher Health & Hygiene will further improve the profit margins and growth prospects.
For every Powerbrand that is bought the direct cost to make it is less than half of the sale price. While the supermarkets appear to be full of promotions for these types of products Reckitt Benckiser is still making a robust return.
The P/E valuation of Reckitt Benckiser is 23.8X forecast earnings for 2015 and then 22.2X for 2016. Looking further out to 2019 and the forecast P/E at 18.3X is still on the high side while the dividend yield on offer by then is only 2.8%.
By contrast Unilever is on a forecast P/E of 18.3X for 2016 and the figure is expected to fall to 13.8X by 2019. However, Reckitt Benckiser is less dependent on emerging markets, which are seeing weakness, and has higher profit margins.
Reckitt Benckiser also has less dependence on areas that can be subject to changing tastes such as food and personal care. It is hard to see brands like Durex, Air Wick, Calgon, Nurofen, Gaviscon and Dettol going out of fashion.
From a long-term perspective the investment case for Reckitt Benckiser does continue to stack up in our view. Given the track record and business resilience this is a business that is worth paying up for.
This report was produced by Fat Prophets Senior Research Analyst, Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?