Share buybacks and what the dividend yield isn't telling you

Seeing the elephant
Focusing too much on operations and not enough on capital allocation can be dangerous.
In his book, Shareholder Yield: A Better Approach to Dividend Investing, US author and investor Meb Faber tells the Indian parable of the blind men and the elephant. The curious group hears about a strange animal. They seek it out and each one inspects a different part of its body before arguing about what to make of this strange beast. “The creature is some kind of snake.” said the man who felt its trunk.
“No, no.” disagreed the next man, who felt its front leg. “The elephant is straight and sturdy, like a tree trunk.” And on and on they go, each party insisting the elephant is something else entirely. None of them could see the complete picture and all of them made incorrect conclusions.
When it comes to looking at stocks, to see the elephant, it helps to look not just at how a company generates cash, but how productively it deploys capital. A steadily increasing dividend isn’t always in the best interests of a company, for example. In fact, sometimes, it can get in the way of future growth.
Efficient capital allocation is one of the fundamental drivers of future value and the way companies distribute their resources is changing. How do we keep up?
The capital deployment tool kit
Companies have five main “tools” for deploying capital
Understanding when to use which tool is vital in creating shareholder value
Financial records are littered with examples of poor capital allocation
Warren Buffett points us to William Thorndike’s The Outsiders: Eight Unconventional CEOs and Their Radically Rational Blueprint for Success. One passage, in particular, stands out:
“CEOs need to do two things well to be successful: run their operations efficiently and deploy the cash generated from those operations. Most CEOs (and the management books they write or read) focus on managing operations, which is undeniably important…” writes Thorndike.
“Basically, CEOs have five choices for deploying capital -- investing in existing operations, acquiring other businesses, issuing dividends, paying down debt, or repurchasing stock -- and three alternatives for raising it -- tapping internal cash flow, issuing debt, or raising equity. Think of these options collectively as a tool kit. Over the long term, returns for shareholders will be determined largely by the decisions a CEO makes in choosing which tools to use (and which to avoid) among these various options.”
Michael Mauboussin, Director of Research at Bluemountain Capital Management, wrote a paper in 2012 while at Legg Mason Capital Management called Share Repurchase from All Angles. It makes the fundamentally important point that the prime responsibility of management is to invest capital - be it physical, financial, or human - at a rate in excess of the opportunity cost of capital.
Alternatively, capital should be allocated to opportunities with the highest returns. This sounds basic but how often do we stop to check that this is what management is actually doing?
In his paper, Mauboussin published the following exhibit of how US companies spent cash between 1985 and 2011:
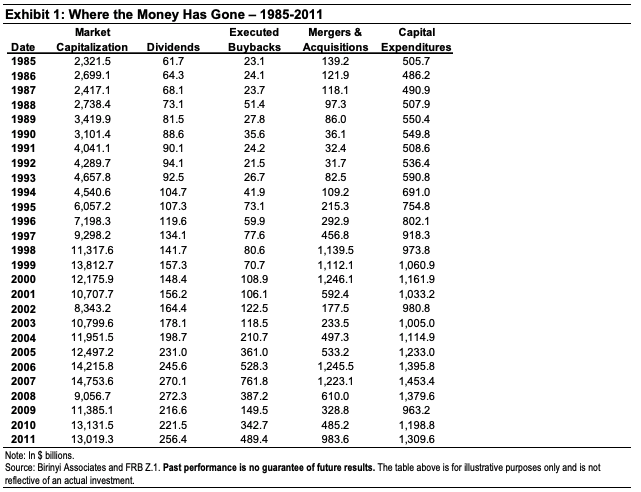
The data show that for every $1 spent in the period, companies spent $0.55 on capex, $0.27 on mergers and acquisitions, and $0.18 on dividends and buybacks.
Profitable capex is the most desirable use of cash. As for dividends, high yielders have been proven to outperform the market over time (when dividends are reinvested). M&A is a little trickier - studies show that value typically goes to the seller, while the buyer tends to earn about its cost of capital. Reasons for this include:
Hubristic management underestimating the complexity and cost of extracting synergies
Eroding value by bidding up the price (the winner’s curse)
Increasing scale driven by ego, influence, and financial compensation (empire building)
Buying at the top of the cycle, when the firm has cash to burn, prices are high, and sellers want to sell
When good chances go begging because of dividend commitments...
- Studies identify many winning high-yield investment strategies
A strong dividend track record can provide a floor to a stock price and reduce volatility
The risk is that higher-return opportunities are abandoned to satisfy a demand for yield
Dividends are a valuable source of income and can be a signal of strength. Studies also suggest they limit the volatility of stocks during tougher markets. Tweedy, Browne compiled this paper, which is a good (and short) introduction to some of these.
Shareholders seek stable and rising dividends, but it is here that problems can arise. What was once “stable and rising” can become “inflexible and burdensome”. At worst, dividends can prevent optimal capital allocation and affect financial health.
Warren Buffett articulated a wariness of dividends in his 1984 Berkshire Hathaway letter:
“Dividend policy is often reported to shareholders, but seldom explained. A company will say something like, ‘Our goal is to pay out 40% to 50% of earnings and to increase dividends at
a rate at least equal to the rise in the CPI’. And that’s it - no analysis will be supplied as to why that particular policy is best for the owners of the business. Yet, allocation of capital is crucial to business and investment management. Because it is, we believe managers and owners should think hard about the circumstances under which earnings should be retained and under which they should be distributed… In our opinion, management should choose whichever course makes greater sense for the owners of the business.”
It appears that others agree. The documented link between dividends and long-run sustainable earnings appears to be weakening (as found in this paper by Brav, Graham, Harvey, and Michaely). Other, more flexible options are winning favour.
Share buybacks and the changing face of capital allocation
- Share buybacks are growing in popularity around the world
Their flexibility allows them to complement, or even replace, dividends
Unfortunately, there is anecdotal evidence of poor execution
Stock buybacks had their “Big Bang” moment in 1982 when the SEC introduced 10b-18. This rule gave companies safe harbour to purchase their own stock. At first in the US, and then at other companies around the world, management began substituting dividends with buybacks. This trend does not look like it will be slowing down anytime soon.
With this tool, management can commit capital to more attractive opportunities as they arise. The problem is buybacks can be executed poorly. They are sometimes switched on when times are good (and shares are expensive) but turned off when the market crashes (and shares are cheap). As Mauboussin notes, this is the exact opposite pattern you would expect from management trying to build value.
If we visualise Michael Mauboussin’s data from the table above, it tells an interesting story:
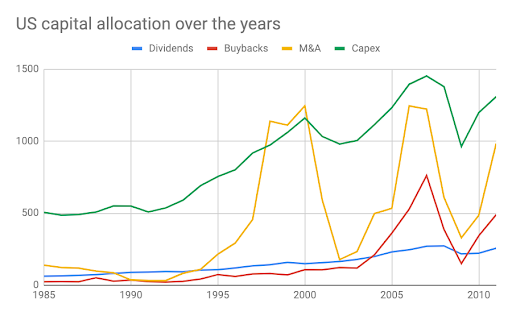
Similar trends to this are observed in other markets around the world. Two points jump out: 1) M&A and stock buybacks are more volatile than capital expenditure and dividends, and 2) buybacks became more popular than dividends in 2004 and have remained so ever since (except for 2009).
When we calculate the compound annual growth rate of each tool, we see that buybacks increased at more than twice the rate of dividends in the period:
- Buyback CAGR: 12.0%
- M&A CAGR: 7.5%
- Dividend CAGR: 5.4%
- Capex CAGR: 3.6%
Interpreting buybacks
- Good buybacks: high conviction. Meaningful quantities bought back at a discount to expected value. Only if no better investment opportunities exist
Bad buybacks: low conviction. Expensive stock purchased to offset options or superficially inflate performance
The data point to a long-term trend of increasing share buybacks in multiple markets. Clearly, we need to be able to analyse and interpret this capital allocation tool.
The key question is: does the stock trade at a discount to estimates of its intrinsic value? Some, such as Mauboussin, argue few executives think about buybacks properly. Using an objective measure such as price-to-book or a composite of different measures to identify a premium or discount might help. For overcapitalised companies with expensive shares, a special dividend is a reasonable alternative.
Look at the net amount of shares bought back and account for the dilutive effect of options. A rough and ready way to do this is to keep track of the change in the number of shares outstanding. Mauboussin splits stock repurchase programmes into three distinct classes. In order of preference:
The intrinsic value school - executives distinguish between under and overvalued. Their buybacks provide a useful signal to investors
The fair value school - steady and consistent buybacks
The impure motives school - using buybacks to inflate EPS, offset dilution, or to lift the return on equity
Conclusion
- Capital allocation is changing
Shareholder yield captures more information than dividend yield
But it is harder to track
As the saying goes, “When the facts change, I change my mind. What do you do, sir?”
The way in which executives distribute cash to shareholders is evolving. Dividends are less popular and share buybacks are winning ground. This has important implications, such as lowering the comparability of indices on a dividend yield basis over longer time frames.
It might be more instructive to look not just at dividend payments, but at the total amount of capital returned to shareholders. The shareholder yield accounts for dividends and buybacks. The trouble is, we lack visibility and solid data regarding the latter. This makes the shareholder yield more of a pain to calculate.
That aside, the fact remains that stock repurchases are an increasingly popular tool for companies to use. Getting to grips with them can only help.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
18 comments
Interesting discussion on the intrinsic worth of share buybacks
Observed research seems few and far between in the UK with a little more available on US markets
Out of interest only, here’s a chart of the S&P 500 overlaid with iShares US Equity Buyback Achievers UCITS ETF
https://www.ishares.com/uk/ind...
S&P 500 Buyback Index Ticker: SPBUYUP is also falling behind the S&P 500 index over 5 years
Does anyone have a view on Man (LON:EMG) Stock quotes a Div yield of 6.33 and average shares reduced by 1.3% with ongoing share buyback programme at present
Hi Timarr
Thanks for the reply. This would be far better chatted about over a pint or two than on a bulletin board.
We have been here before. I've always accepted that Next buyback policy has been better than most companies. What we cant know and the figures can't show is whether the share price would have gone up a similar amount anyway. The PE ratio would be higher of course but NEXT PE is remarkably low for such a successful retailer and arguably THE bell wether retailer.
And of course what we do know for sure that NEXT shareholders who sold ahead of the falls when they were buying back in 2008, 2015, 2016, 2017 and 2018 were rewarded while those who stayed invested were punished.
But my main point is so what if they did reward shareholders. It's the obscene waste of money on them that was the key point in my previous post and nobody else seems to be the least bit bothered by that, but just whether or not buybacks reward shareholders.
Anyway thanks for taking the trouble to reply but with so little interest I'm not sure anything is to be achieved by us discussing or disagreeing on this any more.
The article suggests and, I suggest, most of us instinctively agree that money spent on Capital Expenditure reinvestment is better used than on Acquisitiins.
.
However, the article says returns are:
.
M&A CAGR: 7.5%
Dividend CAGR: 5.4%
Capex CAGR: 3.6%
This suggests Acquistions are more beneficial than reinvestment, or even paying Dividends.
.
Is this correct?
.
Ah, I get why you say that.
It's the compound annual growth rate of money spent by management on M&A - not the compound annual growth rate of returns.
So M&A spend grew at a faster rate, but it's not saying anything about its profitability.
I loathe most buybacks.Whenever they are discussed on bulletin boards it is always the often minor plus or minus points that posters focus on and never the obscene waste of money involved.
How many realise that in the US alone last year more was spent on buybacks than THE ENTIRE UK GOVERNMENT SPENDING??
Yes. That's right. They would have covered the cost of every hospital, every Health Service employee, all the expensive treatment equipment, the buildings and the costs of running them, etc etc etc. And then the same for education, defence and EVERYTHING else. ALL UK GOVERNMENT ANNUAL SPENDING!
And all for what? Perhaps to benefit shareholders and directors sometimes, and that's about it!
OK the UK doesn't spend as much on them as the US does, but some UK Companies have spent more than £50 billion on them over time and £hundreds of billions are spent on them here too. BP spent more on buybacks in one year than the full cost of the brilliant London Olympics. The BP share price then crashed - from memory the Gulf of Mexico disaster. And the banks like RBS and Lloyds bought back £billions. RBS then went bust and Lloyds is still paying the price for their rescue. All that money ended up down the drain. And Lloyds ended up reissuing a lot of shares again in two subsequent rescue rights isses.
Do people realise that very often companies just cancel the shares they buy back? Equivalent to throwing the money down the drain imo.
Meanwhile Governments struggle with debt while Companies happily throw it away. Obviously shareholders would not tolerate the money being spent that way, but if it was spent on improving the lot of people in Third world Countries it might help to solve the migrant crisis. And there are so so many better ways of using that money.
Also note that massive buying back often happens NOT when shares are cheap but the exact opposite.
e.g In 2018 there were the most buybacks in the US since 2008. Look what happened next! 2008 was the big market crash and banking crisis. 2018 saw very big 2nd half falls in the US following the $1 trillion spent there on buybacks. Not only are they an obscene waste of money. Companies can't even get their timing of them right.
Note too that much of the money repatriated to America by Trump has ended up not being usefully employed but on buybacks. Apple spent $100 billion on them last year. Apple's share price has recently crashed 35%!
Next is sometimes used as an example of buybacks working well. Have they? They HAVE rewarded those who wanted out as they got out at £60+ before the share price fell to £36 in 2017. They manifestly did NOT reward those who stayed in for that share price fall. And that's another thing about buybacks. Time and again, even when done sensibly as Next does (i.e NEXT only buyback if confident the share is good value) they don't work as their many fans claim.
But worst of all is not the investment case. It's the criminal amount of money wasted on them.
Next is sometimes used as an example of buybacks working well. Have they? They HAVE rewarded those who wanted out as they got out at £60+ before the share price fell to £36 in 2017. They manifestly did NOT reward those who stayed in for that share price fall.
That covers 0.019% of shares bought back by Next since 2000:
Next have bought back over 60% of their shares over that period at an average price of £16.30. Out of nearly 230 million shares bought back only 8 million were at prices significantly in excess of today's price. Without buybacks the current EPS of £4.29 would have been £1.60 and the current dividend of £1.60 per share would have been £0.61 per share. Basically anyone who bought in 2000 and hung on for the ride has seen the value of their shares rise from around £8 to about £48 - and about 60% of that rise is attributable to buybacks.
Yes, of course if you'd got out at the top of the market you'd have made more money - but who does that on a consistent basis? Only 4.4 million shares out of 230 million - 0.019% - were bought back at above £60 - and yes, those sellers have benefited at the expense of holders. The sellers of the other 220 million odd shares have lost out or, at best broken even.
There are lots of cases where buybacks are wrong but Next (LON:NXT) isn't one of them - it's the exception that proves Buffet's rule: if buybacks are executed at below intrinsic value they're value enhancing for long-term shareholders.
But you know, I think we've been here before :)
timarr
When can we screen on shareholder yield please.
Unfortunately, it's hard to get good data on the shareholder yield. I'm not sure of anyone that shows it yet due to this and the admin of maintaining it... I can't give any guidance as it's a big project in itself and I know there's already a lot of work going on to make other upgrades
I guess this is stating the obvious, but often dividends depend upon the stage of development a company is in.
Young growing companies normally don't pay dividends, because all the free cash needed for reinvesting in the development of the company. As the company's growth slows, it starts to pay a dividend. Mature large companies pay a dividend because (usually) outsize growth is no longer there, so a stable company with a decent steady div, growing in line with inflation (if possible) is attractive to the income seeking investors and institutions,
This is, of course a generalisation, but probably covers 80% of cases. Berkshire Hathaway doesn't pay any dividend, for example.
No, it's definitely worth mentioning!
I was just reading up on a Fama French study actually called "Disappearing Dividends: Changing Firm Characteristics or Lower Propensity to Pay?" - not sure if you've read it but they track dividend data back to the 1920s, so QI.
Using Compustat data from 1963-98, they find that the assets of divi payers average about 8x those of non-payers during 1963-67, but by 1993-98, it had increased to more than 13x those of non-payers. This suggests that the size gap has been widening. They also agree with you about companies turning to dividends when it becomes harder to grow from investing in operations.
It's US stocks only, mind.
No mention of Directors attempts to raise their bonuses and their personal share purchases through buybacks regardless of where the share price lies. e.g, historically, Centrica.
It didn't come up in the research papers I was reading... I suppose it's implied in Mauboussin's "impure motive" school of buybacks although it's not spelled out. I'm sure it happens, I'm not familiar with the Centrica case though. Certainly sounds like a conflict of interest
Hi Jack
Take a look at Accounting Rules? Stock Buybacks and Stock Options: Additional Evidence.
As usual it's Buffett who says it best:
But generally whenever a stock I hold starts buying back its shares I take a long, hard look at the economics. Even being generous I reckon 2 out of 3 buybacks have little economic justification for shareholders. However, when they're done well as with Next (LON:NXT) they can compound shareholder returns.
Good article, though.
timarr
Thanks!
I will do. CEO comp was a point also raised by Silver Moon. I agree about Buffett, he has a real knack for summing complex topics up and making it all sound so obvious...
How do you gauge the economic justification - do you do a DCF or compare share price to some kind of relative valuation? I think Patrick O'Shaughnessy and the people at OSAM have done some work here which I'd like to check out.
How do you gauge the economic justification - do you do a DCF or compare share price to some kind of relative valuation?
Hi Jack
DCF? No, you're confusing me with someone who thinks more analysis of more data makes for better decisions - I prefer to be roughly right rather than precisely wrong :)
So, either I'm looking for shares trading at a discount to net tangible asset value (rare but not unknown) or trading on low multiples of OCF with relatively high levels of FCF - i.e. lowish capex.
Taking Next (LON:NXT) as an example, they're currently trading at 12.7 times their OCF and their FCF is nearly 80% of their OCF. They've shown that they can maintain current levels of profitablity so you wouldn't expect massive capital drawdowns from here, bar a wholesale market crash. So I'd say that's cheap and a buyback is a decent use of capital.
With lower quality companies (mainly measured by ROCE) I'd want even better figures,
timarr
Very generous Timarr!
"2 out of 3"....I would say a lot more have little economic justification for shareholders. A LOT!
In too many cases, Management pay themselves a very very generous salary, an equally generous bonus and then set themselves up with a juicy LTIP and or share options. Most of the latter vest on some measure of EPS, which magically gets hit thanks to a buy back.
Hand out shares like confetti and then use shareholder funds to buy back the shares and hide the dilutive effects.
Of course, they fully deserve three bites at the cherry and us shareholders should just sit back and be glad we have such wonderfully dedicated management who care so much about the company. The fact that the buy backs improve EPS and that allows them to hit the target for their options to vest is purely coincidence.
I know "Our Graham" is a fan of Buy Backs, but personally, as a buy and hold investor, I just don't see how 95% of them leave share holders any better off. In almost all cases, Next being an exception, they primarily benefit Management. Occasionally large institutions are able to sell/dump holdings via a Buy Back but even those are few are far between when compared to how often Management appear to be the main beneficiaries.
Dividend payers outperform non-dividend-payers because bad companies can't afford to pay dividends. Dividends are okay strictly in moderation.
I agree sensible dividends are a good thing and a strong vote of confidence. There is also the compounding effect when they are reinvested, and the fact that a strong track record of payments can prop up the share price and reduce volatility.
It's interesting that research points to companies opting for buybacks where once they might have started paying a dividend, though. There are also more companies doing a combination of dividends and buybacks, where once they might have just paid a dividend. That's why I'd like to get hold of some better data on shareholder yields...