Should I be buying oil stocks for the SIF Portfolio?

When oil producers’ cartel OPEC announced plans for a modest production cut last week, reactions were mixed.
OPEC’s commitment to cut production to between 32.5 and 33.0 million barrels per day implies a cut of between 240,000 and 740,000 b/d from August’s production level of 33.24mb/d. The hope is that this might be enough to help rebalance the market without sacrificing too much of OPEC’s market share.
Saudi-led OPEC has resisted a cut until now in order to defend its market share. Instead, OPEC producers have aggressively ramped up their oil production over the last two years. OPEC oil production in August 2014 was 30.35mb/d. Last week’s proposed cut still represents a production increase of more than 2mb/d compared to two years ago.
The problem now is that many OPEC countries are desperate for the influx of cash an increase in the price of oil would provide. They’ve seen US oil production fall by around 600,000 b/d over the last year. They may believe that by making a similar cut, they can erase the remainder of the global supply glut and lift oil prices.
We’ll have to wait until November to find out more. So far, western oil companies that have adopted the lower for longer mantra have been proved right. But having followed the oil market quite closely over the last couple of years, my personal view is that we are getting closer to a recovery.
Even if I’m wrong, I believe most diversified portfolios should have some exposure to the energy sector. At present, the SIF portfolio does not have any oil stocks. In the remainder of this article I’ll explain why, and take a look at some possible choices.
Why are there no oil stocks?
I do own some oil stocks in my personal portfolio. But I have not added any to the SIF portfolio because with one exception, none of the stocks in the UK oil and gas sector have qualified for my screen.
One reason for this is that the screen isn’t intended to pick up cyclical stocks exiting a major downturn. The screen is designed to identify companies that are already profitable and have the potential to deliver above-average returns.
The oil sector has a poor track record in this regard. When Brent crude oil traded above $100 almost continuously from 2011 until mid-2014, this didn’t generate bumper returns for shareholders. Escalating costs and over-ambitious new projects swallowed up the tidal waves of revenue that flowed into company coffers.
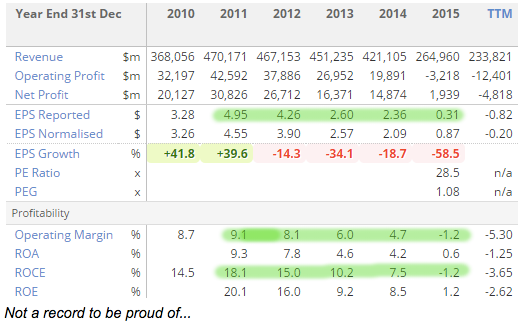
For example, Royal Dutch Shell’s return on capital employed peaked at 18.1% in 2011. By 2014 it was down to 7.5%. Over the same period, reported earnings fell from $4.95 per share to just $2.36 per share. Dividend growth averaged just 2.3% between 2010 and 2014.
3 oil stocks to consider?
Fewer than 10% of the 113 UK oil and gas stocks listed on Stockopedia have a StockRank above 60. In comparison, more than 30% of stocks in the Food & Tobacco sector have a StockRank over 60.
It’s not hard to see why oil and gas stocks are so out of favour with Stockopedia’s computers. Very few of these stocks are profitable or pay reliable dividends. Many are heavily indebted.
Interestingly, the top-ranked stocks are mostly dual-listed Russian firms which only show up when you select the ‘Include Dual Lists?’ checkbox at the top of the page. The top-ranked of these is NK Lukoil PAO, a £26bn oil and gas firm with a StockRank of 99.
Lukoil has been a regular fixture in my screen results for the last few weeks, and I’ve been debating whether to add it to the portfolio. Russian oil firms appear to have survived the combined impact of sanctions and the oil market crash in much better shape than many investors expected. This is partly because the falling value of the ruble has helped to mitigate lower oil prices. The RUB/USD exchange rate was 35 in early 2014. Today, it’s 65. Anecdotal reports also suggest that a more lax environmental regime in Russia helps keep operating costs lower than they might be elsewhere...
In any case, Lukoil’s numbers certainly look good. According to Stockopedia, the shares trade on a trailing P/E of 10 and a rolling forecast P/E of 6.1. The forward dividend yield is about 6% and net debt is pretty modest, at just 2.3 times trailing net profit.
What’s stopped me investing in such stocks is a lack of market knowledge and the perceived additional risks of investing in Russia. Rightly or wrongly, I’d rather leave Russia to those who know more about the market.
However, I do have some indirect exposure to the Russian oil market in my personal portfolio, via BP. The UK’s number two oil and gas firm has a 20% stake in Russian oil and gas giant Rosneft. BP has operated successfully in the Russian energy market for many years and should return to profit this year. Profits are expected to rise sharply in 2017, so could BP soon become a candidate for the SIF portfolio?
I used Stockopedia’s excellent checklist tool to see how close BP is to meeting my screening criteria:
3.png)
It’s clear that BP is some distance away from satisfying qualifying for my screen. Perhaps the biggest obstacles are the group’s lack of profitability and its rising debt. Extrapolating from 2016 broker forecasts, I estimate that BP may generate an earnings yield (EBIT/EV) of 4%-5% this year. That’s well below my 8% threshold. Another problem is that net debt is currently 8.6 times forecast net profit, much higher than my limit of five times.
Barring a violent move upwards in oil prices, I don’t think BP is likely to qualify for the SIF portfolio in the near future.
A smaller firm?
One alternative choice is to focus on smaller producers with strong balance sheets. But this is still risky, in my view. I think that investing in an oil services company might be a better idea.
Although these companies are seeing margin pressure from their customers, they’ve become an essential part of the energy industry ecosystem. They provide much of the engineering know-how that’s required to develop and operate oil and gas fields.
One stock which might soon qualify for the SIF screen is FTSE 250 firm Petrofac:
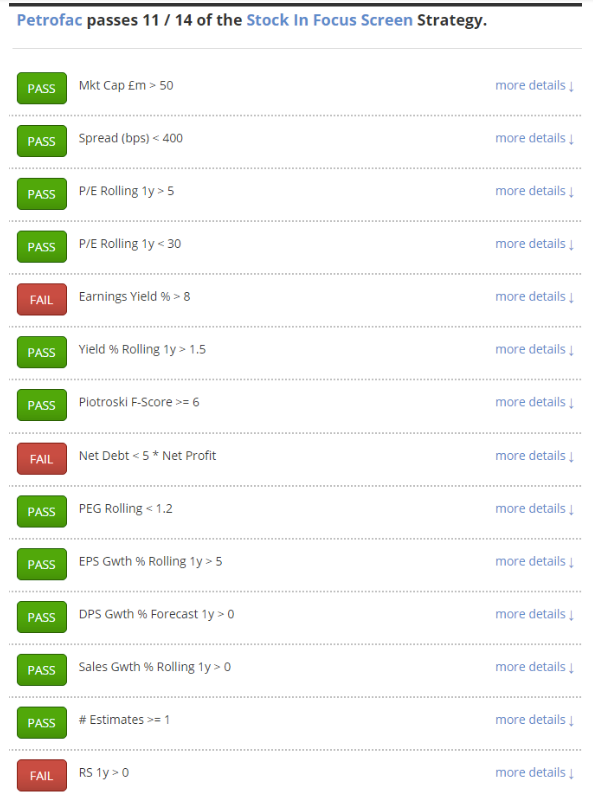
Petrofac doesn’t quite meet my criteria, but I think this could change if the firm’s 2016 figures meet expectations. I estimate that Petrofac’s earnings yield could top 10% this year, while the ratio of net debt to earnings should fall sharply.
I suspect the SIF portfolio will remain without an oil stock for a little longer. But the market outlook is definitely improving. I believe 2016 will see oil firms deliver some solid results on which to base investment decisions.
Disclosure: Roland owns shares of Royal Dutch Shell and BP.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Here is my contribution on Russian Oil stocks,
I bought two in 2013 on the US market. Gazprom OGZPY and its exploration arm GZPFY known as 'Neft'.
They performed well and paid dividends until I sold most in 2014. I held some OGZPY for the dividend but sold at a capital loss which exceeded the income.
When I tried to buy some at the 2015-2016 lows the North American brokers intervened saying I could only sell because of the embargo over Ukraine.
I could have bought in London but my broker there charges huge commissions and custody fees for 'foreign' stocks. You should look into this before buying. However the stocks themselves are cheap on Western metrics as your article points out.
This is accurate. Believe it. They will stay 'cheaper' because of the Russian discount.
I am presently unloading my other Russian investments held through trusts and funds because the stock market there is on a roll and the translation into devalued sterling gives a useful profit. Currency devaluation gives the domestic stock market wings, see the FTSE and Argentina as other examples.
I also read another article saying OGZPY would get cheaper.
Keep an eye on it and your other one. I shall. They can be good investments.
When oil hit its recent low around Feb this year I set up an Oil portfolio in Stockopedia but without committing any real money (at the time I didn't know about Fantasy Funds or I would have set it up in there).
It was just for interest because I wasn't anywhere near brave enough to commit real money to that type of portfoio and I wanted to find out if my gut instinct that "now is the time to buy" was right or not.
I used Malcy's Oil Bucket list (malcysblog.com) as the source of the buys and just bought an equal weight of everything on his list.
Now in hindsight I wish I had bought it for real because that portfolio is up about 97% in just short of 8 months!
Out of interest the shares I bought (or rather didn't buy for real) on 12th of Feb were...
Amerisur Resources (LON:AMER)
Bowleven (LON:BLVN)
Cairn Energy (LON:CNE)
Faroe Petroleum (LON:FPM)
Hurricane Energy (LON:HUR)
Ithaca Energy Inc (LON:IAE)
Pantheon Resources (LON:PANR)
Parkmead (LON:PMG)
Premier Oil (LON:PMO)
Rockhopper Exploration (LON:RKH)
Sound Energy (LON:SOU)
Tullow Oil (LON:TLW)
Victoria Oil & Gas (LON:VOG)
Highest stock rank of any of them is 70, lowest is 15.
I guess my point here is that picking individual oil stocks is probably fraught with difficulty but perhaps some NAPS style basket of oil shares picked mechanically based on some factor or opinion and bought at the right time might be a strategy that people could work with?
Hi Roland - you're brave man to discuss O&G stocks on Stockopedia. From my own posting history, I've found this sector consistently attracts more red thumbs than any other sector (apart from the pro and anti Brexit camps). Not sure whether this is just down to Stocko users' own bad experiences (the sector does some prey to more pump and dump antics than most) or whether its simply the apparent dislike Stocko's valuation algorithms have for O&G companies.
As a somewhat contrarian investor, I started to build up my O&G portfolio towards the end of last year when the US$10 barrel of oil was apparently a racing certainty. I already had long term holdings in the majors, RDSB and BP as well Petrofac on the service side but started to look at some of the smaller companies either with reasonable balance sheets or, in my view, a decent chance of exploration success with the drill bit. The table below sets out my sector portfolio showing the current market cap, Stocko rankings and share price performance over the past three months.
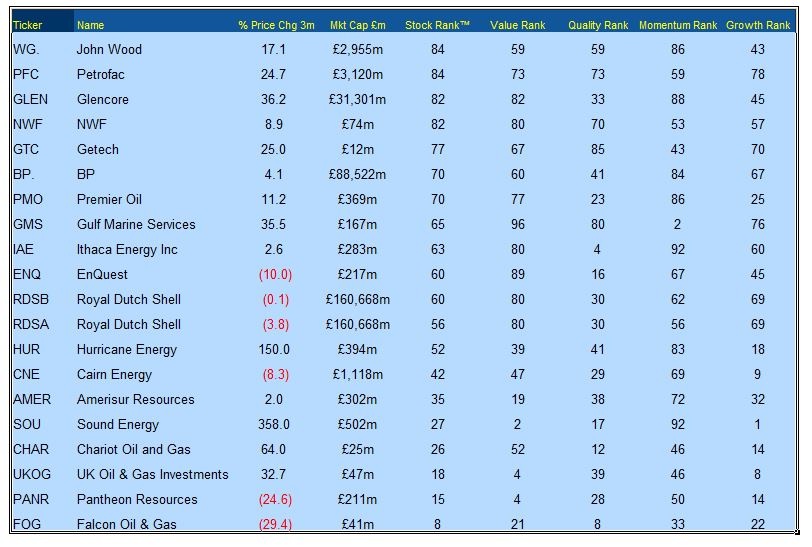
The three month price change stats are slightly arbitrary (although the 6 month picture is broadly similar) but give an indication of some general features of my recent experience with the sector. A few observations:-I am the first to admit there is plenty of junk in the sector - I've found a few (and quite possibly still have several) but as ever with investing you have to kiss plenty of frogs to find your Prince Charming. Rather than go "all-in" on a single conviction stock, I have tended to take opening stakes in several and then add to successes and thin out the losers. In my view, the sector does require patience and a reasonably strong constitution but does seem, for the time being at least, to provide decent returns.
Gus.
Gus
Excellent posting, thanks for sharing (I hate the expression, but it works well at times :)).
Regards
Howard
Amerisur Resources (LON:AMER) anyone? Doesn't have the stockrank at the moment but I think that's because ranks are backwards looking. I think there is loads of potential there due to their new oil pipeline! Would be interesting to see how close to the other criteria it is.
The story was that the introduction of the pipeline would cut costs to $15 per barrel. The pipeline would have a capacity of 50,000 bopd. Implementation was very slow and post implementation it was found that there was a bottleneck over the border in Ecuador so throughput is only 5-6000 bopd (due diligence?) and they still rely on trucking.
It operates in a highly impoverished area which under the FARC was dependent on coca production. Peace does not mean prosperity in this case (referenced in rns's as 'social issues' or suchlike).
For me this is a classic story stock and I would require evidence of profitability before investing.
Finally the more recent rns's indicate that they might have problems with the water levels in some wells.
BARGEPOLE!
It may well be a story stock but you seem to have made up a large percentage of the story in your reply!
Writing “due diligence” in your post doesn’t really excuse you from actually checking the facts before posting.
The committed minimum throughput through the pipeline was 5000 bo, you must have typed in an extra 0 in your capacity number. So the throughput was planned to be 5000 bo, and the latest update says....
Average dailythroughput was 6,152BO during the Period.
Peak daily throughput was 7,045 BO during the Period.
It seems almost all of the oil they drill goes out though the pipeline because their production rate is...
Average daily production was 6,971 barrels of oil per calendar day ("bopd") during the Period.
Peak daily production was 7061bopd during the Period
So any remaining trucking seems minimal and declining.
The story that cost per barrel is reducing down to $15 a barrel seems to be playing out. I agree that evidence of profitability is important but I would say that about any stock.
Roland
Thanks for the article, useful as always. In particular I liked the way you have illustrated an application of your investing disciplines, screening and Stockopedia tools/reports onto a sector, and one which seems to be beginning to become favourable but has not yet met your buy criteria. I will watch with interest to see if, in the future, the sector does improve to the extent your selection criteria allows you to acquire an oil stock.
Regards
Howard