Should I buy International Consolidated Airlines for the SIF Portfolio?

Virgin Atlantic founder Richard Branson once said that “If you want to be a Millionaire, start with a billion dollars and launch a new airline.”
It’s a view shared by legendary investor Warren Buffett. Back in 2013, the Sage of Omaha described the airline industry as “a death trap for investors”. Buffett made the comment in response to an AGM question about whether the trend towards consolidation in the airline industry had made it more attractive for investors.
In a 2002 interview with The Telegraph, Buffett expanded on this theme: “You’ve got huge fixed costs, you’ve got strong labor unions and you’ve got commodity pricing. That’s not a great recipe for success.”
In the UK stock market, there’s one company that epitomises these risks. British Airways owner International Consolidated Airlines has been a big player in the consolidation of European airlines. It now owns Aer Lingus and Iberia, in addition to the UK flag carrier.
IAG has also had to cope with a fair amount of industrial action in recent years. Staff at British Airways and then Iberia were not prepared to accept chief executive Willie Walsh’s revised employment terms without a fight.
For much of this time, IAG was contending with $100 oil. When the oil market finally started to collapse in 2014, forward hedging meant that fuel costs for airline groups like IAG didn’t fall quite as fast.
Despite all of this, IAG has been a very successful investment in recent years. The shares have risen by 95% since 2013 and IAG has started to make dividend payments. Rapid earnings growth has appeared to justify Mr Walsh’s aggressive acquisition strategy.
Stockopedia likes the shares too. IAG has a StockRank of 91. The shares have qualified for my SIF screen on a number of occasions since the portfolio was launched. With the shares now down by about 15% from their January highs, IAG now looks cheap. Broker forecasts suggest that IAG currently trades on just six times forecast earnings and offers a potential yield of more than 4%.
In this article I’m going to look at whether IAG stock looks cheap enough to offset the risk of a cyclical downturn in the airline industry. I’ll also ask whether there are any financial warning flags investors should beware of.
A tough stock to value?
On the face of it, IAG offers decent value. The stock has a ValueRank of 83 and trades on 8.8 times trailing earnings. A price/sales ratio of 0.6 is very attractive, given IAG’s earnings yield of 13.8%.
However, this flattering picture is only a year old. Booming market conditions plus IAG’s acquisition of Iberia and Aer Lingus mean that the firm’s historic earnings are pretty meaningless. IAG’s turnover has tripled since 2010, while net profits have risen by 650%.
Underlying asset value isn’t reassuring either. IAG trades on 2.6 times its book value and 6.9 times tangible book value. My final concern is that while cash flow has improved over the last few years, Stockopedia’s normalised figures suggest that the airline hasn’t generated any free cash flow since 2010:
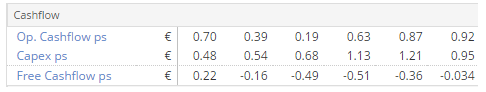
These figures are normalised by Stockopedia’s data provider, Thomson Reuters. Although my experience is that they are generally reliable, it’s often also worth taking a look at the actual accounts. These can provide more details and additional colour.
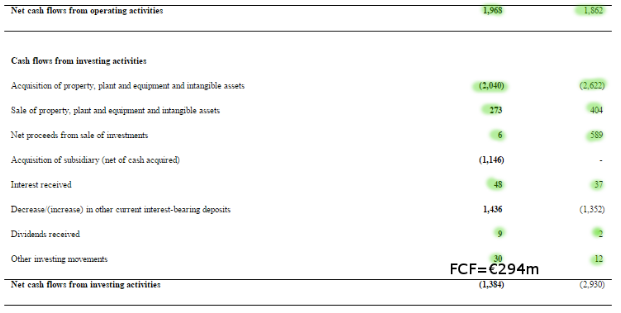
In this case, IAG’s cash flow statement for last year suggests that if we ignore acquisitions and a shift of money from short-term deposits into cash, IAG’s free cash flow was positive last year, by €294m:
Now that the group’s acquisition spree has come to an end, I hope to see free cash flow improve.
Genuine quality or a boom?
IAG isn’t the only apparently cheap stock in the airline sector at the moment. Based on forecast earnings, easyJet and Flybe both look very cheap. Even Ryanair looks affordable.
This may not be a coincidence. Consolidation, falling fuel prices and ruthless cost-cutting have helped drive a boom in demand for air travel. According to an article (paywall) in the FT last year, airline profit margins have not been this high since the mid-1960s. The International Air Transport Association (IATA) says that airlines are finally expected to start generating returns in excess of their cost of capital, for the first time since the IATA’s records begun in the 1990s.
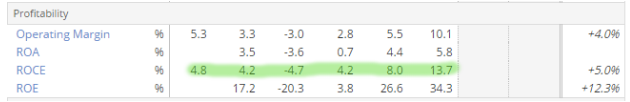
Here are the profitability figures for IAG. I’ve highlighted return on capital employed -- it’s clear that the firm’s returns can only have exceeded the cost of capital over the last 1-2 years:
The fact that airlines shares are so cheap suggests to me that the market is pricing in a cyclical top for airlines. I’m tempted to agree. A number of major airlines, including IAG, have recently indicated that they will reduce the pace at which they are adding new capacity.
This combination of record profitability and slowing growth concerns me. Cyclical industries almost always overexpand before being forced to contract. A rise in fuel costs or slowing demand growth could squash profit margins. While ticket prices have fallen to reflect cost cutting and lower fuel costs, at some point they will have to rise. This too could affect demand.
There’s also the question of debt. Stockopedia figures show net debt of €2,774m for IAG, which looks pretty benign relative to last year’s net profit of €1,539m. But the group’s own reporting shows a much higher adjusted net debt of €8,264m at the end of the first quarter.
The difference is the result of IAG’s inclusion of “capitalised rolling four quarter aircraft operating lease costs” in its measure of net debt. These don’t show up on the balance sheet as borrowings but are debt-like in terms of the payment obligations they imply.
The good news is that net debt did fall by about €250m during the first quarter. But I’d like to see further falls before IAG cranks up its dividend payments too far. A burden that’s manageable now could become problematic if market conditions change.
Is momentum favourable?
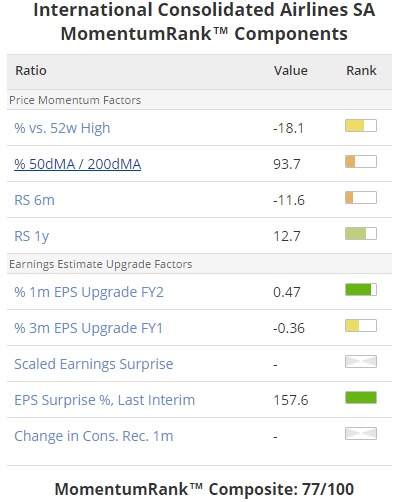
Cyclical shares can be great investments if your sense of timing is good. IAG’s MomentumRank of 77 suggests that the shares could continue to fly. The shares look very cheap on 6 times forecast earnings.
But I’m not totally convinced. One reason for this is that the stock’s chart suggests to me that IAG may have peaked back in April 2015:
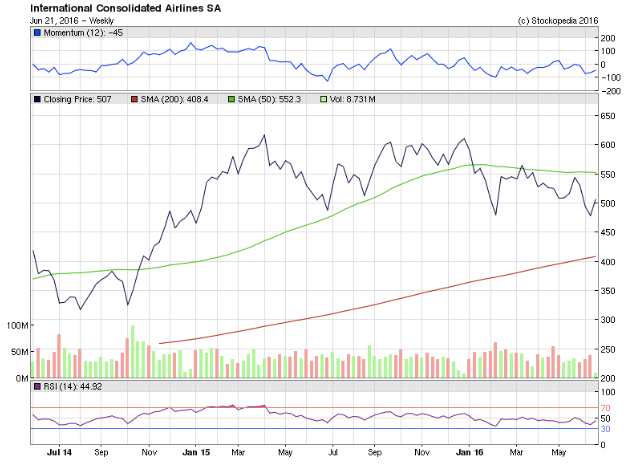
The factors which make up the MomentumRank are also quite mixed. The share price is nearly 20% below its 52-week high and momentum has turned negative.Earnings forecasts have fallen from April’s peak of €1.12 per share to €1.08.
It’s tempting to trust the StockRanks and buy into IAG’s temptingly cheap valuation, but the SIF portfolio isn’t purely mechanical. IAG qualifies for my screen, but in this case I’m not going to buy. The cyclical risks are too great, in my view, especially as the SIF portfolio is already overexposed to cyclical stocks.
I’d be interested to hear your views. Have airlines peaked, or do you think they will continue to cruise comfortably for another year or two?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
International Consolidated Airlines SA (LON:IAG) issues the first post-Brexit profit warning:
http://www.investegate.co.uk/intl-con-airline-grp--iag-/rns/response-to-result-of-eu-referendum/201606240952231922C/
Did I dodge a bullet with this one? And does it have wider significance for the airline sector? I'm not sure.
Food for thought, though.
Roland
Yes looks like it, read across maybe, how about cost of fuel or is that all hedged?
Wizz Air Holdings (LON:WIZZ) does look tempting now, down 18 today.
I too am continually tempted by International Consolidated Airlines SA (LON:IAG) (and £EZJ), but will not bite. As above if I was temptepd by the sector I would go with Wizz.
Although in terms of customer experience I flew Vueling (see acquisition spree) not long ago and it compared well to its peers I thought.
It qualifies for two of Stockopedia's Short Selling Screens, which, at the very least, would give me pause for thought.
OsullivanB,
Thanks for your comment. I didn't mention the short-selling screens in my article due to space constraints but also because my feeling is that in part, International Consolidated Airlines SA (LON:IAG) qualifies for the James Montier Trinity of risk screen due to its acquisition spree.
Here are the criteria for the Montier screen:
P/6y Avg Earnings > 16
EPS > 2 * EPS 6y Avg
Altman Z Score (1) < 1.8
My feeling is that the first two criteria are only valid because earnings have risen so rapidly over the last couple of years. I touched on this in my section on IAG's ValueRank.
Regards,
Roland
Thank you, Roland, for that helpful reply.
Bernard
Hi Roland.
Thorough and well thought through analysis of the pros and cons. Interesting to see the "monkey" overcame the "mechanical" with your final decision not to invest. I think the killer for me with International Consolidated Airlines SA (LON:IAG) is that as a previous regular business passenger with BA I became very aware of a decline in custome service quality as they chased costs down such that it became something of a chore travelling with them. There seemed to be a fair bit of resting on the reputation of previous laurels which coupled with a legacy of generous staff benefits that needed to be cut back to make them competitive made them less enjoyable to travel with.
As a hard nosed investment, I prefer Wizz Air Holdings (LON:WIZZ) . Greater capacity for growth and less legacy issues. Better placed on all Stock Ranks although more expensive on a p/e basis and not yet paying dividends.
Gus.
Hi Gus,
Thanks for your comment. I'm not a big fan of BA economy either!
I agree that Wizz Air Holdings (LON:WIZZ) does appear very well placed at the moment. In fact, the shares would qualify for my screen if it wasn't for the lack of a dividend. We'll have to see whether Wizz can progress into maturity without too many growing pains!
Roland