Should investors diversify across multiple 'factors'?

At a first glance, the stock market may look like complete and utter chaos. Prices move up and down in a seemingly random and inexplicable walk. But academics and practitioners have been studying the market for decades in order to identify order within the chaos. Gradually, from the genesis of work by Fama and French decades ago, they have built a gradual consensus that there are a group of risk premiums that can help explain and predict stock market returns. These can be measured as 'quantitative factors' and used to build portfolios with a higher chance of beating the market.
As Stockopedia subscribers will know, value, momentum, and more recently quality, are all factors that have been proven to help explain stock market returns. But while these are some of the most important factors, they are the tip of the iceberg. Haugen and Heins (1972) found that over the long-run, low-volatility stocks beat higher-volatility stocks, while a recent paper by Ibbotson, Chen, Kim and Hu (2013) showed that illiquid stocks have a tendency to outperform liquid stocks. Institutional investors have begun to market products that offer exposure to these drivers.
Harry Markowitz, a pioneer of modern portfolio theory, once described diversification as the only free lunch in finance. So the question we seek to answer in this article, is do the same benefits come from diversifying across factors ?
Blending virtues with vices
Different factors have their own unique advantages and drawbacks. Investors can get the best of all worlds by blending factors in such a way that the virtues of one factor cancel out the vices of another.
Lets take a look at value and quality as an example. Good quality firms tend to be profitable companies with a strong balance sheet and a good competitive advantage. Their levels of intrinsic value (ie. true worth) may be higher than unprofitable companies with poor balance sheets. The risk is that high quality companies could be expensive because the market has already factored their quality into the share price. However, cheap stocks are more likely to be priced below their intrinsic value, so investors could buy high quality companies at bargain prices by blending value with quality.
We can't time the market
Some portfolio managers use different factors during different phases of the economic cycle. This is called style drift and perhaps it makes sense given that different factors generate different returns during different periods. Value stocks tend to underperform momentum stocks during a bull run. However, momentum stocks can suffer sharp reversals, especially during a bearish phase. Unfortunately, investors do not have a crystal ball to predict which factor is about to perform best. We can therefore lose out by betting on the wrong factor. So in theory, factor diversification should limit the risk of picking the wrong factor, while at the same time providing exposure to the factors that outperform.
What evidence suggests that multi-factor investing works?
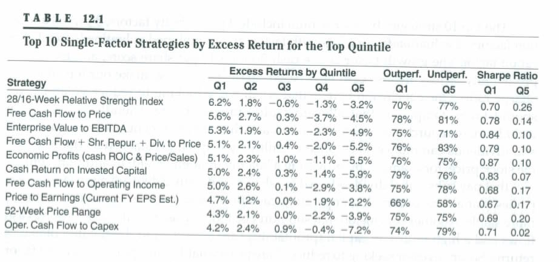
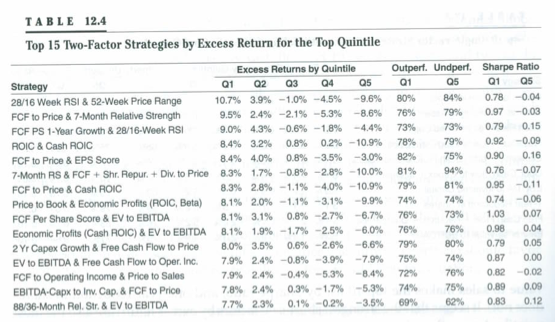
Richard Tortoriello - author of Quantitative Strategies for Achieving Alpha - encouraged investors to think of factors as 'building blocks' that can be used to construct market beating portfolios. Tortoriello believed that once a 'factor with investment value is identified, it can be combined with other factors to create complex models that generate even stronger and more consistent excess returns'. To make his point, Tortoriello tested single-factor and double-factor strategies. He found that strategies which picked stocks using two factors tended to beat single factor strategies (see tables below).
Tortoriello is not the only practitioner who advocates diversification across market factors. This white paper by Robecoargues that companies underperform when factors 'disagree' with each other. For example, a company with good value and good momentum will outperform a share with good value but poor momentum. To illustrate their point, Robeco introduce 'generic strategies' (ie. strategies that only target value stocks) and 'enhanced strategies' (ie. approaches which blend good value with good momentum).
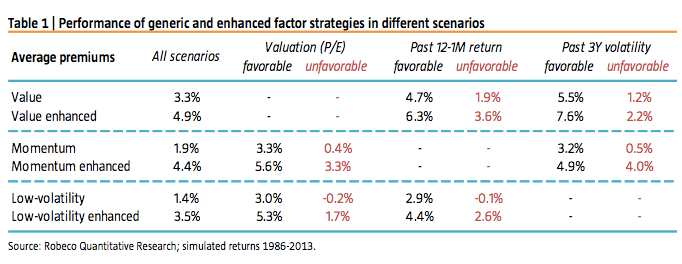
The table above shows that returns of the enhanced 'strategies' were all higher than the returns from the 'generic' strategies. For example, 'value' returned 4.7% over a 12 month period whereas 'value enhanced' returned 6.3% over the same timeframe. Furthermore, strategies tended to underperform when factors were opposed to each other. For instance, companies with strong momentum but 'unfavourable' (expensive) P/E ratios only returned 0.4%, whereas shares with good momentum and a 'favourable' (cheap) P/E returned 3.3%.
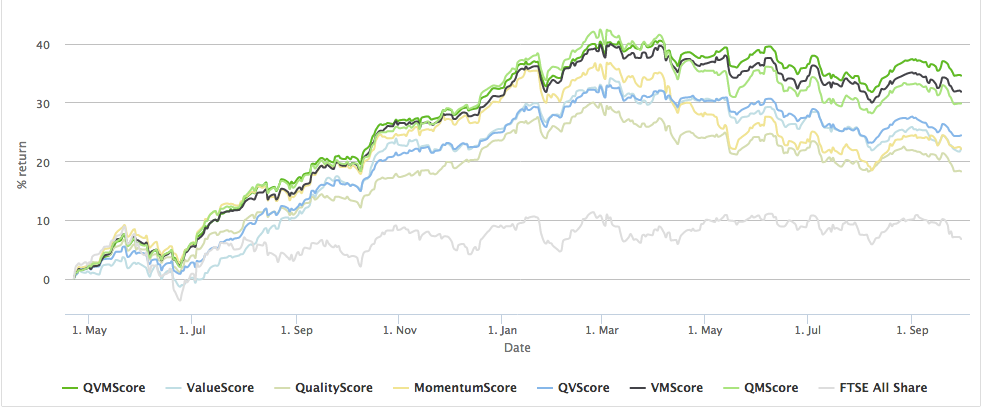
Stockopedia's live tests have also shown that since May 2013, portfolios built using the three factor StockRank (Q+V+M - quality, value and momentum) outperformed portfolios that were constructed using the two factor crossover ranks VM, QM, QV which in turn beat single factor portfolios (V, Q, M).
Taking it further… diversifying within factors
Investors can also diversify within factors, a process is at the cornerstone of
Stockopedia's StockRanks ranking methodology. To explain, one can select stocks using a diverse range of metrics that all measure a specific exposure to a more abstract factor. For example, investors could select value stocks by using a range value metrics, including the P/E, P/S and P/B ratios. Research by James O'Shaughnessy - author or What Works on Wall Street - suggests that 'combining several value ratios into' an investment strategy 'leads to more consistent, higher returns than using any single value ratio alone.'
Again, this is because different metrics deliver different returns during different periods. Low P/S companies could outperform low P/E firms one year, but several years later the pattern could reverse and low P/E firms may start to outperform. Investors would of course do well if they picked stocks by using the single metric which generated the best returns, but investors don't have the gift of foresights to predict which metric is going to beat the market. We could therefore lose out by betting on the wrong metric. O'Shaughnessy therefore argues that a 'methodology that includes all the value' metrics could help to 'smooth out the attendant risk of betting on a single factor.'
“You should always make a stock pass several hurdles before investing in it." James O'Shaughnessy - What Works on Wall Street
Conclusions
Diversification across factors provides several advantages. We can't be too sure when one factor (ie. value) will outperform another (ie. momentum) but we can improve our chances of picking the winning factor by diversifying across value and momentum. Different factors also have their own respective advantages and drawbacks which can cancel each other out. Value stocks may be cheap for a reason, but we can ensure that we are buying a good company at bargain prices by overlaying quality with value.
Stockopedia's StockRanks are a metric which help investors to find companies that are diversified across three different factors (namely quality, value and momentum). We've put together this free brochure which explains how the StockRanks work. Feel free to check it out and leave any comments or feedback below. We've also written this free ebook on the value factor.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?