SIF August review: Gold fails to glitter (TAM, RWA, POLY)

August has been another benign month for the stock market and for my SIF systematic portfolio. I’m writing this monthly review a week earlier than usual due to next week’s bank holiday. But barring any nasty shocks over the next four days, both SIF and the wider UK market look set to end the month with modest gains.
As usual, this review will cover all the stocks that have been in the portfolio for my minimum period of nine months (or longer). Three stocks satisfy this criteria this month. Two have already been held over from previous months, while one has reached its first review date.
Polymetal International (LON:POLY) - this Russia-based gold miner has delivered a stable operating performance but growth seems to have stalled.
Tatton Asset Management (LON:TAM) - this financial advisor platform provider has been a big winner so far for SIF. Can I keep holding?
Robert Walters (LON:RWA) - recruiters are performing well at the moment and momentum looks strong.
I’ll take a look at each of these stocks in a moment, to see whether they still satisfy my screening criteria. But first, let’s take a quick look at the portfolio itself.
SIF Folio: August performance update
Regular readers will know that I try to avoid making predictions about the direction of the market or macro-economic trends. My system is to let my rules control the makeup and cash weighting of the SIF (Stock In Focus) portfolio.
As a natural pessimist (realist?), I expect a reality check at some point. But for now I’m happy to report that SIF has continued to outperform the market in August.
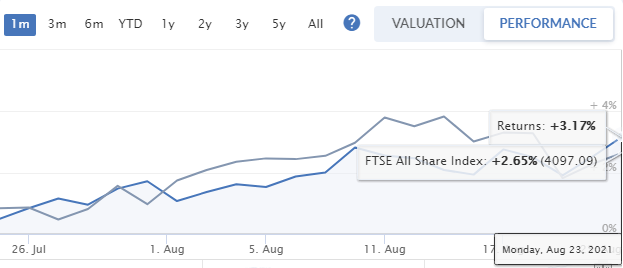
According to the Stocko charts, the SIF folio rose by 3.2% during the month to 23 August. This compares to a 2.7% gain for the FTSE All Share Index, which I use as a benchmark.
Note that I’m using the excellent new time-weighted return performance view on these charts. This adjusts out the impact of any cash inflows and outflows, providing a true view of portfolio investment performance versus the benchmark.
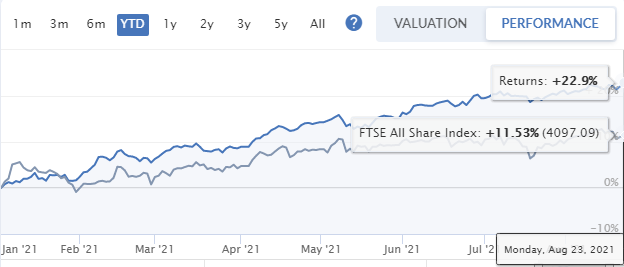
Over the year to date, the portfolio has doubled the return of the wider market:
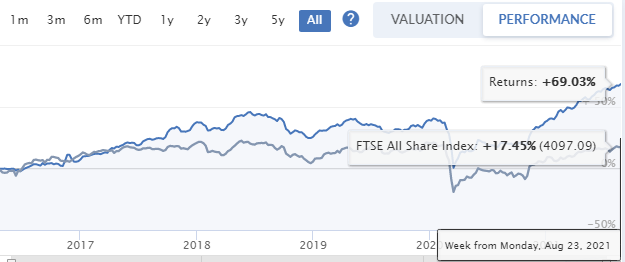
Finally, since the portfolio’s inception in April 2016, it’s generated a gain of nearly 70% (excluding dividends), versus less than 20% for the FTSE All-Share:
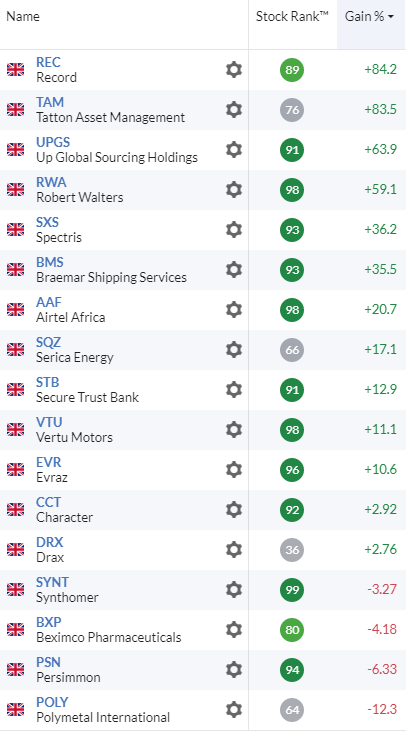
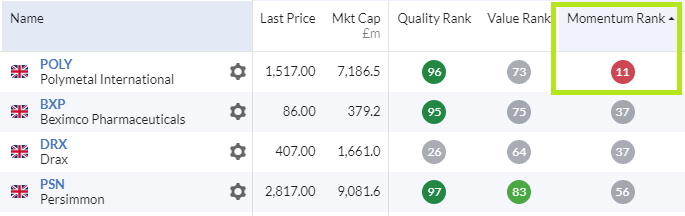
To wrap up this section, here’s a snapshot of all the portfolio’s current holdings, before any changes that might result from this review.
Polymetal International (LON:POLY)
(Buy report: 04 November 2020)
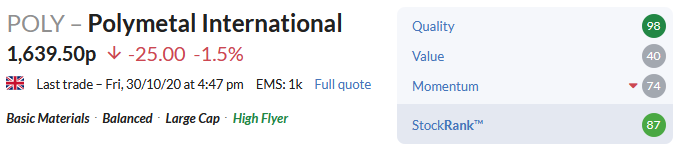
When I added FTSE 100 gold miner Polymetal International to SIF in November, the stock was classified by Stockopedia as a High Flyer. Today, this Russian firm is a Contrarian stock and the worst-performing member of the SIF folio, as we can see above.
I think that the best way to review this holding is to explain what’s happened since November, and what I think it means.
*November 2020*
*August 2021*
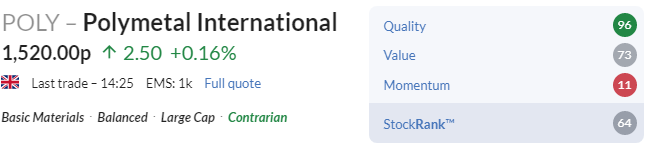
Let’s start with the graphics above. We can see that Polymetal’s QualityRank is largely unchanged, but that since November, the MomentumRank has collapsed and the ValueRank has risen. This switch accounts for the change in the StockRank Style over the last nine months:
High Flyer: Strong scores for quality and momentum, poor value
Contrarian: High scores for value and quality, weak momentum
You can read more about these styles in this guide to the style classifications. All I’ll say here is that both High Flyer and Contrarian are considered to be winning styles within the Stockopedia taxonomy.
However, the switch in style implies that Polymetal International has gone from being a relatively expensive, fast-growing company, to being a cheaper, slow-growing company. For a portfolio like SIF, which targets affordable growth, this might not be ideal.
What seems to have happened is that the growth seen from 2017-2020 has come to a halt.
Polymetal’s 2020 results showed that net earnings rose by 57% to a record of $1,086m last year. This was driven by an increase in production and a 30% rise in the price of gold from January - August 2020.
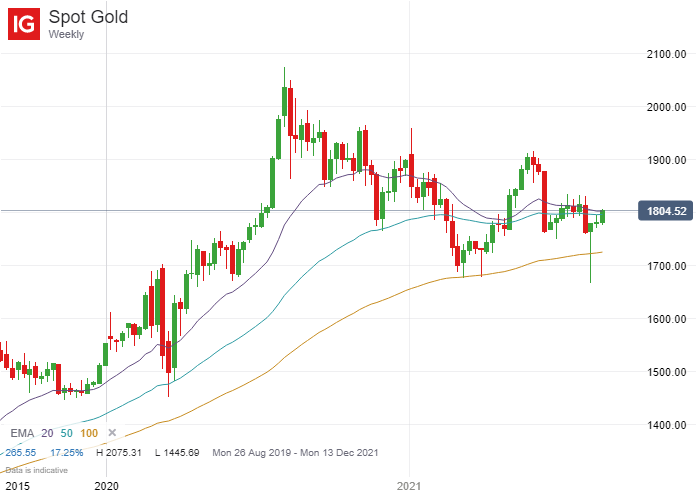
Source: IG Index
However, this performance is not expected to repeat in 2021. Company guidance is for all-in sustaining costs to rise from $874 to $925-$975 per ounce, offset by production growth of around 7%. Profits are expected to be broadly flat this year, ending the run we’ve seen since 2017.
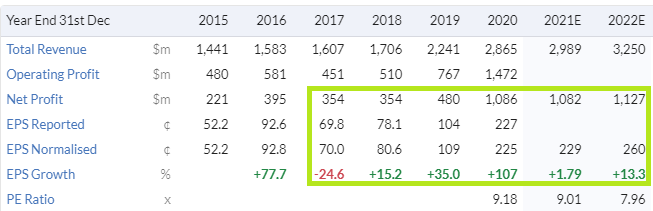
Although stronger growth is expected in 2022, this isn’t enough to persuade the market to assign a stronger valuation to the company. I can’t quibble with this. Operational efficiency is only one element of the company’s profitability. Gold, oil and foreign exchange rates all exert a powerful and often unpredictable influence too.
When earnings growth comes to a sudden halt, momentum suffers. We can trace the collapse in Polymetal’s MomentumRank to two specific problems.
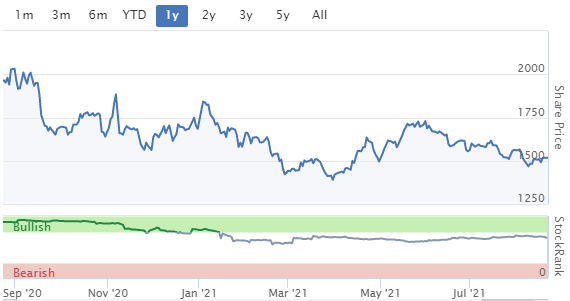
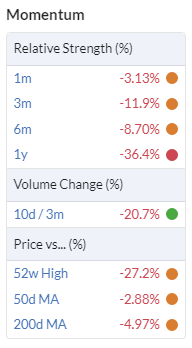
Price momentum: Polymetal’s share price performance has been weak over the last year, lagging the wider market:
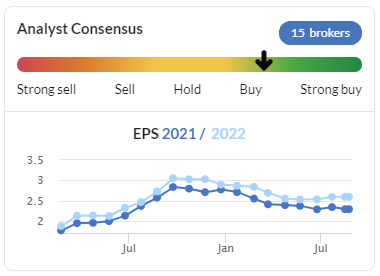
City brokers covering the stock have also cut their forecasts on several occasions:
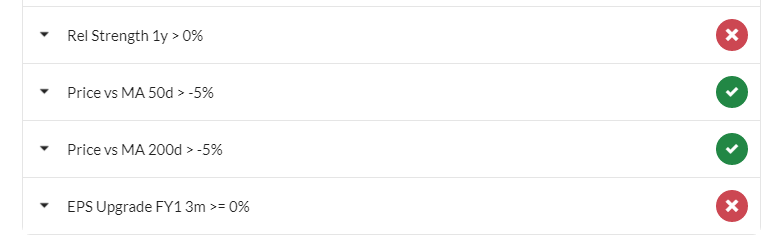
My decision: I highlighted Polymetal’s falling share price and falling earnings forecasts deliberately. These factors reflect two of the tests in my selling screen. Polymetal fails both of these tests:
For this reason, I will sell Polymetal International from the SIF portfolio and my own mirror portfolio this month.
In doing so, I’ll remove the worst-performing holding in SIF and the one with the lowest MomentumRank.
The overall loss on this position, including dividends, should be about -9%.
Total return: -9%
Verdict: Sell
Robert Walters (LON:RWA)
I covered the latest trading update from recruitment group Robert Walters in my review last month. The short version is that the business is performing well. As far as I can tell, it seems likely to continue doing so.
My decision: Robert Walters continues to pass all of my screening tests, so will remain in the SIF folio for a further month.
Total return to date: +63%
Verdict: Hold
Tatton Asset Management (LON:TAM)
I also covered Tatton Asset Management in some depth last month. There’s been no further news from the company since, so I don’t have anything new to add this month.
My decision: Tatton Asset Management continues to pass all of my screening tests, so will remain in the portfolio for at least one more month.
Total return to date: +89.5%
Verdict: Hold
Conclusions
In his book One Up On Wall Street, famed US fund manager Peter Lynch said that “selling your winners and holding your losers is like cutting the flowers and watering the weeds”.
I’ve tried to design the SIF system to help me follow Lynch’s advice in a more systematic way. When I hold a stock that’s successful, my rules allow me to continue holding the shares even if they’ve become more expensive - as long as they’re still displaying positive momentum.
Conversely, my rules mean that stocks which fail to deliver growth will gradually be weeded out of the portfolio.
Tatton Asset Management and Robert Walters have performed well for the portfolio. Although I’m mindful of the cyclical risks faced by these businesses, both stocks appear to have the potential to deliver further growth. So they stay and will be reviewed again at the end of September.
In contrast, Polymetal International’s contribution to the portfolio over the last nine months has been negative. Although I don’t think this is a bad company, it no longer satisfies my holding criteria. So it must go.
I’ll sell SIF’s virtual holding in Polymetal International and my own real-money holding after this article has been published, sometime later this week.
Disclosure: At the time of publication, Roland owned all of the shares listed in the SIF portfolio.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Hi Roland,
Ive just taken a look at what is sat in your buying screen today (see below).
At what point do you review these companies and then look to add them to the PF. I note that there are curently only 4 or 5 of the stocks in the buy screen held within your PF. I appreciate you cannot chop and change each week/month, but at what point do you review the buy screen and decide one of them (or more) need to be promoted to the SIF.
Thanks for the ongoing write-ups. Really interesting as usual.
K
Hi Kevin,
I review the screen results for potential buys in most weeks (except when I do this monthly roundup).
I sort the stocks by StockRank (descending) and look for a new company that doesn't overlap too much with any of the existing stocks in the portfolio. If I find something, then I'll review it and decide whether to add it to the PF. Here's the latest buy:
https://www.stockopedia.com/co...
Looking at the screening results in your comment, for example, I would not consider £TW because SIF already holds Persimmon (LON:PSN) (disclosure: I hold). I'd be unlikely to buy Morgan Sindall (LON:MGNS) and Tyman (LON:TYMN) for similar reasons.
In general, I also reject overseas stocks (e.g. Steppe Cement (LON:STCM) and Hon Hai Precision Industry Co (LON:HHPD) above). They may be excellent companies, but they don't fit within the risk profile I target for this portfolio.
Occasionally, I may also reject companies for cyclical reasons - e.g. Anglo American (LON:AAL) recently:
https://www.stockopedia.com/co...
Finally, there are some companies I won't buy because there's something I dislike about the business that doesn't show up in my screening. One example might be a monster pension deficit, or some aspect of the accounting that I mistrust.
I hope this makes sense. My screen is a starting point for building the portfolio, but I only add shares selectively. I aim to create a diversified portfolio I'm happy to own myself.
Regards,
Roland
Thanks Roland. Thats really useful. I am getting a good feel for what you are doing now and will be looking keenly to see if there is anything I can replicate. I'd ,ike to get a bit more structure to my investments and I like the idea of having some rules to guide me, rather than my haphazard approach as it is now.
Can you remind me (Ive probably asked or seen this before), do you have historic performance data for how your PF has performed over each year?
Thanks very much.
Regards
Kevin