SIF Folio: B&M could offer value despite premium price tag

This week I’m continuing my hunt for reasonably-priced defensive stocks I can add to the SIF Folio. Last week I considered high street cake shop Cake Box Holdings, but I couldn’t convince myself to hit the buy button.
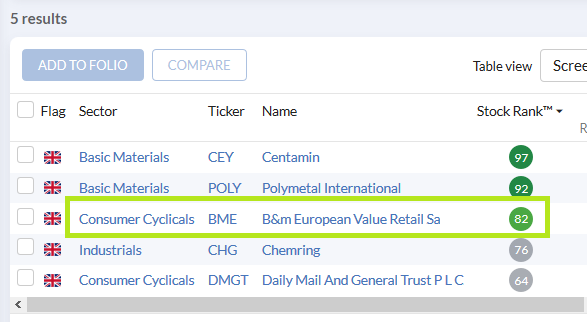
My next candidate is variety discount retailer B&M European Value Retail SA (LON: BME). This £3.9bn FTSE 250 firm has popped up on one of my stock screens recently as a potential SIF stock.
If you haven’t visited any of B&M’s 656 stores before, they’re roughly the size of an Aldi or Lidl supermarket and target a similar customer base. B&M sells a wide variety of goods including:
Non-perishable, ambient groceries
Fast-moving consumer goods (FMCG), including branded products
Homewares
DIY/gardening
Seasonal products
Pet supplies
This product range is carefully curated and includes around 100 new lines per week. This focus on novelty is combined with a good mix of staple value items to ensure customers make regular repeat visits.
B&M also runs 293 convenience stores under the B&M Express and Heron brands, plus 101 stores in France under the Babou and B&M brands.
The group is run by CEO Simon Arora. Mr Arora acquired the business with his brother Bobby in 2004, when it had just 21 stores. Bobby Arora is B&M’s trading director - I believe his expertise in product selection and sourcing is a crucial element of the group’s success.
Owner-manager attraction?
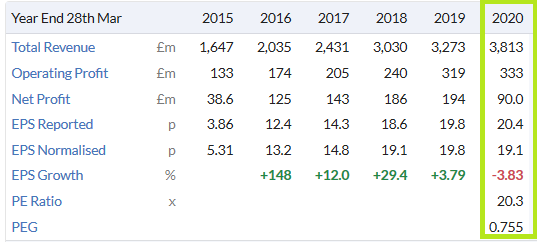
The core B&M model appears to work well. Group revenue has risen from £2,035m in 2016 to £3,813m last year (y/e 28 March). Broker forecasts suggest group revenue will rise to £4,133m this year, making this a potentially impressive growth story.
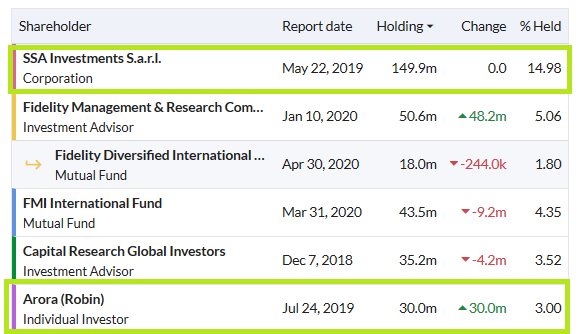
Although the Aroras have sold down a significant amount of their stake, they remain 15% shareholders through their Luxembourg-based investment vehicle, SSA Investments S.a.r.l. A third brother, Robin Arora, also owns a 3% stake.
A defensive pick?
B&M’s focus on everyday essentials allowed the group’s UK stores to remain open during lockdown. This makes it one of an elite group of retailers who’ve reported strong results this year.
Although this business is listed in the consumer cyclicals sector, I think B&M’s product mix and value focus means that it’s worth considering as a defensive stock.
Modern shopping patterns tend to include smaller and more frequent shops at several stores. Chains such as B&M have benefited from and perhaps driven this consumer behaviour, in my view.
The company’s value focus also means that it’s likely to be resilient in a recession, a point made by CEO Simon Arora in the firm’s latest results:
We should also not forget that as a discounter, our appeal is strengthened when large sections of the population are worried about their personal finances or are having to live within constrained household budgets.
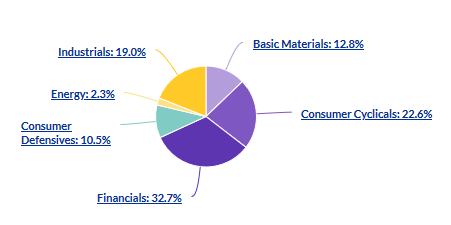
Right now, only 10% of SIF is invested in defensive stocks (British American Tobacco and Finsbury Food):
At first glance, I think B&M could be a useful defensive addition to SIF. Let’s take a closer look.
Value retail at a premium price
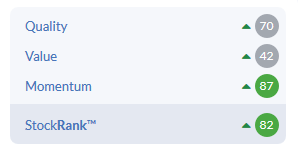
As I suggested in the title of this piece, B&M shares aren’t very cheap. The stock’s ValueRank of 42 is by far the lowest of its factor scores:
The shares currently trade on 20 times trailing earnings - not cheap for a retailer:
There’s not much value on offer elsewhere, either:
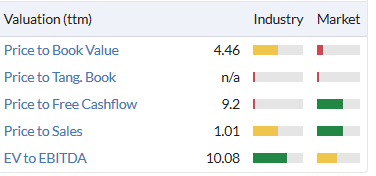
Asset backing is minimal, due to the group’s heavy dependence on leased property and moderate use of debt. B&M’s latest balance sheet (28 March) showed:
Lease liabilities: £1.3bn
Debt: £775m
Cash: £428m
Net debt (excluding leases) of 1.0x adjusted EBITDA
However, additional detail provided in the results suggest true leverage is somewhat higher than these numbers suggest.
Before the year end, the company received £150m from the sale-and-leaseback of a new warehouse in Bradford. In April 2020 (after the year end), this cash was paid out as a special dividend. If this had been paid in March, the year-end adjusted net debt/EBITDA multiple would have been 1.45x.
B&M’s working capital position also benefited from the early impact of the COVID-19 pandemic. Panic-buying in March meant that inventory was converted to cash more quickly than expected. At the same time, shipping delays from China meant that cash outflows in new inventory were lower than expected. This situation is expected to reverse this year.
B&M’s leverage is higher than I’d like to see, but not necessarily problematic. If the group’s quality metrics stack up okay, then I’d be inclined to accept its balance sheet.
Quality: a profitable retailer
B&M competes with supermarkets on some product lines, but it’s far more profitable. Since 2015, the group’s operating margin has averaged a healthy 8.6%. Return on capital employed has averaged 12.8%:
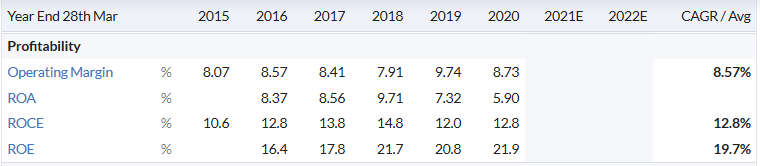
For Wm Morrison Supermarkets, a similar-sized business, the equivalent figures are 1.4% and 3.3%.
B&M’s Piotroski F-score, which is a heavily weighted factor in the QualityRank, is also fairly strong:
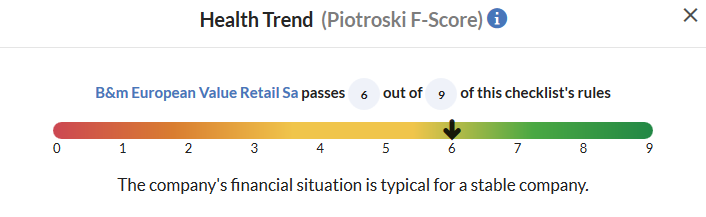
Apart from leverage, the only quality factor that concerns me with B&M is a more subjective issue - capital allocation.
UK vs overseas: B&M’s UK rollout and its acquisition of Heron Foods (a budget supermarket) appear to have worked well. I believe the Arora brothers have a very good understanding of the UK value retail market.
However, the group’s ventures into Europe have not been so successful. The acquisition of German discounter Jawoll was a costly failure that resulted in a £114m loss last year, when the business was sold.
Management say they’ve learned from the problems in Germany and are confident that their 2018 acquisition of French retailer Babou will be more successful. However, store closures during lockdown in France mean that progress has been disrupted.
I think this situation is worth watching carefully. History tells us that even the best retailers can come unstuck when they expand overseas.
Momentum: strong
B&M’s MomentumRank of 87 is the stock’s highest factor score. Let’s split this into its two components to understand why:
Earnings momentum: Last year was a tough one, but if we exclude the loss from the sale of Jawoll, B&M’s earnings from continuing operations were flat, at 19.5p per share. Broker forecasts suggest return to strong growth this year:
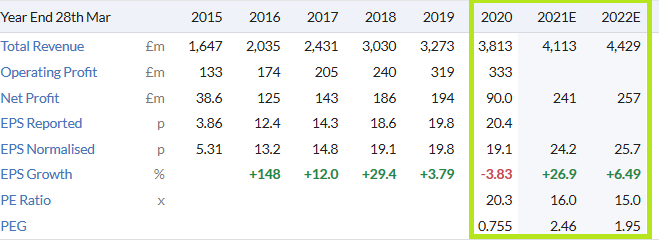
B&M is targeting an estate of 950 stores in the UK, up from around 650 at present. So there’s still a lot of potential, assuming margins can be maintained. I note that analysts are pricing in a reduction in growth in next year (FY22) - perhaps this reflects some caution about expansion potential?
Price momentum: B&M’s share price has bounced back strongly since March. The shares now score very well on key technical measures of momentum:
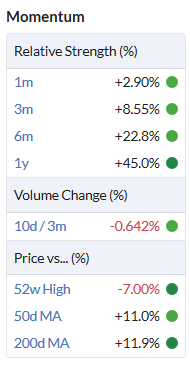
A clean sweep of green lights! I don’t see any concerns here, except that the valuation of 16 times forecast earnings already prices in a fair level of growth.
My decision
My view on B&M is a little mixed. I wrote recently about my dislike of efficient balance sheets - that applies here too. There’s more leverage than I’d really like to see.
However, the group’s management are invested in the business and appear to have a pretty good handle on the UK market. My experience as an occasional customer is that B&M is a Ronseal business - it does exactly what it promises to do.
I also think that the economic fallout from coronavirus means that market conditions are likely to be favourable for B&M for the foreseeable future. As long as operational execution remains good, I think we could see continued growth.
On balance, my view of the group’s near-term prospects is positive. So I’ve decided to add B&M to the SIF folio and to my own holdings this week. As usual, I’ll make the trades after this article has been published.
Disclosure: Roland owns shares of Finsbury Food and British American Tobacco.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
I note the Stock Ranking has moved from 22 in March to 97 in November, The 22 ranking in March a sell trigger for me.........where did I go wrong?
Really interesting read, thanks.
share price has rebounded strongly..partly due to trading through lock down..i think longer term to buy on dips is good..for short term .as with the rest of the market its anyones guess.....slight reservation is high valuation....thanks for article alerting pros and cons...
Thanks Roland for sharing. I held B&M until a few weeks ago when I was happy to take my profit. I too like their value proposition, but I'm not yet convinced to buy back in (as I have with Halford) as I think there are too many downsides. I'll be watching carefully though.
Hi Roland, very useful article.
I already own B&M. They strike me as a bit of a Primark of their sector. I re-visited one recently and they've significantly upped their basic food offering - which from what I know it looks super competitive. I also believe that they will make a decent fist of Baboo, given they have had a dry run with Jawoll - the only concern I would have is, as a family run outfit, are they listening to people who know French Retail.
My other thought is that in a recession they will outperform some of the more up-market retailers.
I also own FIF and BAT.
Finally - they typically stock one decent whiskey at a very competitive price. So if you have to drown your sorrows it wont cost so much.
Finally - they typically stock one decent whiskey at a very competitive price. So if you have to drown your sorrows it wont cost so much.
Thanks Berksbee, I'll have to check that out...
Don't bother - after today's results you can afford something special!