SIF Folio: Beating the market after six months - time to take profits?

The results of my SIF stock screen have almost completely dried up as we head into July. This mirrors my own view that after such a strong market rally, it might be time to take some money off the table before reality strikes later this year.
Fortunately as always, I’m not paid to make macro judgements, only to follow the rules. As it’s the end of the month, this means reviewing those stocks in my Stock in Focus (SIF) virtual portfolio which have been held for at least nine months. Only stocks which continue to pass my SIF screening tests can be kept.
There are six stocks to review this month. This is an unusually high number, as a result of two holdovers from April and May and last September’s buying spree. The companies up for the chop this week are:
Capital (LON:CAPD)
H&T Group (LON:HAT)
The Renewables Infrastructure Group (LON:TRIG)
Pershing Square Holdings (LON:PSH)
Gulf Keystone Petroleum (LON:GKP)
Luceco (LON:LUCE)
I’ll give my verdict on each of these companies in a moment, but as we’re now halfway through the year, I also want to take a quick look at the performance of the SIF folio as a whole so far in 2020.
SIF Folio half-year review
How has my systematic portfolio fared during this year’s stock market crash and subsequent rebound? Not too badly, I think.
SIF went into the crash with a heavy cash weighting which reduced the impact of the market slump. I think it’s important to emphasise that this positioning was the result of my rules-based approach. It wasn’t down to any manual intervention by me.
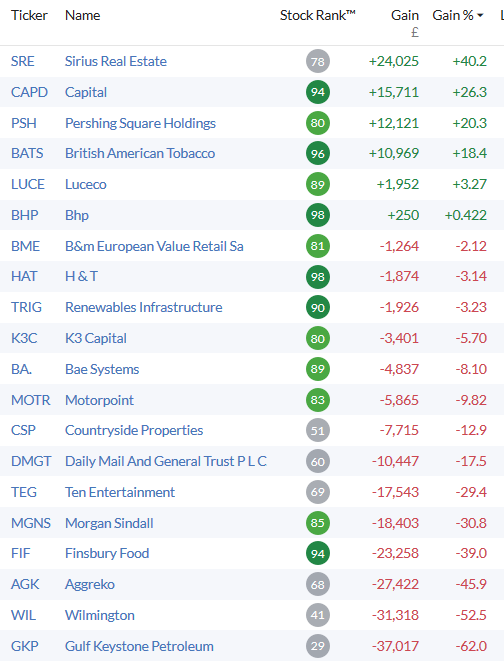
Following the rules made me a net seller in the months before the crash. When valuations dropped, I had plenty of cash available for buying. At the same time, my screen cranked into life and provided a number of new stocks (e.g. BATS, SRE) for me to add to the portfolio. These have helped to offset losses from older holdings:
Here’s how this year looks on a chart. SIF is the blue line, the FTSE All-Share is the grey line:
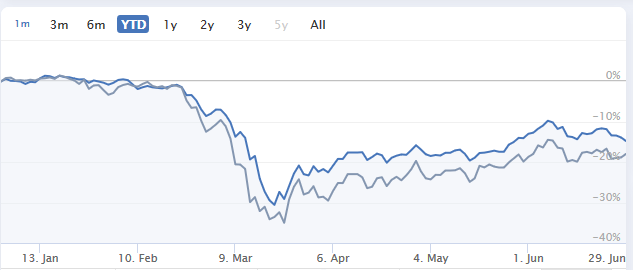
SIF is down this year, but the portfolio has beaten its benchmark index by a healthy 5% (as of 29 June 2020):
SIF 2020 YTD: -14%
FTSE All-Share 2020 YTD: -19%
Taking a broader view, here’s how the portfolio has performed against its benchmark since its inception in April 2016:
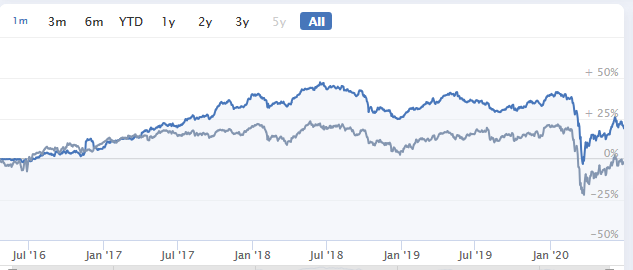
The numbers here show outperformance of 18% since April 2016:
SIF: +21% (4.7% annualised)
FTSE All-Share: -3% (c.0% annualised)
One final note about dividends. The numbers and charts above exclude dividends. But I’ve kept a record of dividend payments and I’m happy to report that they continue to exert a very favourable effect on SIF’s total returns.
SIF + dividends since inception: +30% (6.5% annualised)
Although these figures will not equal the kind of double-digit annualised gains achieved by some active investors, this performance has been achieved by following a relatively simple set of rules.
For an investor taking a similar approach without documenting it as I do, I think this market-beating performance could have been achieved in no more than one hour a week. I think that’s potentially useful.
Overall, I’d say that this year’s crash has certainly strengthened my conviction in following a strict, systematic approach to investing.
As always, I’d be interested to hear your thoughts and experiences on investing through this year’s turmoil.
That’s enough portfolio talk for now. Let’s take a look at the six stocks I mentioned earlier.
Capital (LON:CAPD)
(Original coverage 02/07/2019)
Note: Capital is the company formerly known as Capital Drilling. The name change seems to reflect this Africa-focused mining contractor’s broadening range of services.
I’m not a gold bug, but I can’t deny that SIF’s exposure to gold has provided an excellent hedge to this year’s market crash. Recent updates from the company have been broadly reassuring, in my view.
SIF’s Capital position is now showing a healthy profit, but this stock continues to pass all but one of my screening tests. The only exception is that its spread is often greater than my 4% limit. However, I see no logic in selling a stock because its spread is too wide. So I’ll continue to hold for at least one more month.
Verdict: Hold
Total return to date: +24%
H&T Group (LON:HAT)
(Original coverage 16/07/2019)
Pawnbroking, gold and loan group H&T has provided more gold-linked hedging for SIF. But as a consumer-led group with a big retail presence, H&T has also been hit by lockdown.
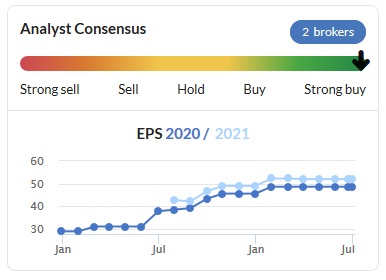
The shares fell on Monday after the company issued a COVID-19 trading statement that warned of an uncertain outlook for the remainder of the year. But the group’s actual performance so far this year seems positive to me, with increased online services, good cash generation and reduced net debt. Brokers have remained positive, too:
After making some slight COVID-adjustments, my view is that this stock continues to qualify for the SIF screen. So I’m going to hold for another month.
Verdict: Hold
Total return to date: -2%
The Renewables Infrastructure Group (LON:TRIG)
(Original coverage 03/09/2019)
I’m a long-term fan of this investment trust, which invests in renewable energy - mostly wind farms. However, recent developments have indicated a greater range of uncertainty about future income. The shares also continue to be valued at a premium to NAV.
The dividend yield on offer is about 5.3%, which looks attractive to me. But for now, I think the upside is limited. TRIG no longer passes all of my screening tests due to its strong valuation, so I will be selling the shares from SIF this month.
Verdict: Sell
Total return: 0%
Pershing Square Holdings (LON:PSH)
(Original coverage 03/09/2019)
Gold has been a good hedge this year, but concentrated exposure to US big caps has proved even better. When I added FTSE 250 listed US investment trust Pershing Square Holdings to SIF in September, I didn’t really know what to expect.
However, this has worked out to be one of the better trades I’ve made in recent years. Pershing Square (through its parent hedge fund Pershing Square Capital Management LP) took out hedges early this year, when the full risks of the coronavirus pandemic became apparent.
These hedges worked superbly and provided $2.6bn of fresh cash. The fund used this money to buy more US shares in late March. Stocks purchased included Berkshire Hathaway, Starbucks and Lowe’s. You can find more details in the annual report.
The US market rebound has been even more dramatic than we’ve seen in the UK. SIF’s Pershing Square holding has delivered a gain of 22%, including some dividends.
However, this year’s gains are not expected to match last year’s blockbuster 58% gain, resulting in a sharp fall in forecast earnings for 2020. This means it no longer qualifies for the SIF screen, so will leave the portfolio.
Verdict: Sell
Total return: +22%
Gulf Keystone Petroleum (LON:GKP)
(Original coverage 10/09/2019)
Perhaps I should have known better. Kurdistan oiler Gulf Keystone has been a disastrous performer for SIF, losing more than 50% of its value despite last year’s chunky special dividend.
The sour crude from Gulf Keystone’s Shaikan field sells at a big discount to the Brent benchmark. March’s oil price crash meant that the firm was actually giving its oil away, for a period. Things have since improved, but plans for production growth have been paused for now. Highly-rated CEO Jón Ferrier has said he plans to retire this year.
I do believe this stock offers value at current levels. But this value could be hard to realise. GKP could be a value trap - a view taken by Stockopedia’s algorithms:
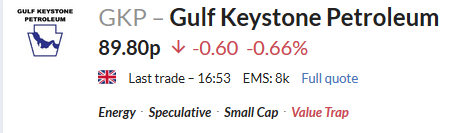
This is a bad loss. But it does demonstrate the benefits of diversification and position sizing. A 50% loss on a 1/20 portfolio position is only equivalent to a 2.5% portfolio loss. That’s manageable (and not too scary).
Verdict: Sell
Total return: -57%
Luceco (LON:LUCE)
(Original coverage 24/09/2019)
LED lighting producer Luceco looked like a cracking buy early a few months ago. At the end of January, SIF’s position was showing a gain of nearly 70%. Unfortunately, it didn’t last:
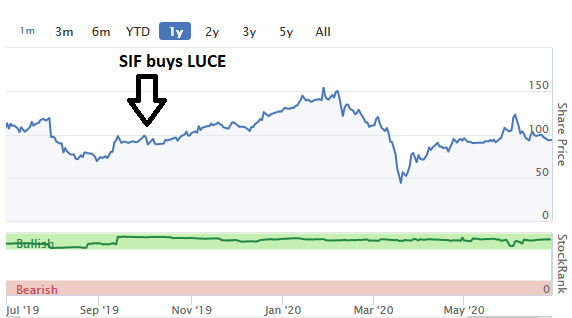
Early on in the year, the risk seemed to be that the firm’s Chinese production facilities would be disrupted by COVID-19. The risk then shifted to customer demand.
The situation now is uncertain. The firm’s latest update indicates that adjusted H1 operating profit should be at least in line with 2019. But as Paul commented in a recent SCVR, this seems almost too good to be true. What does H2 hold in store? We don’t know.
An H1 update is due at the end of July. But brokers covering the firm have cut their forecasts sharply, suggesting that earnings will fall this year.
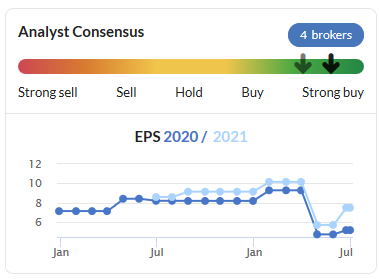
This means Luceco no longer passes my screening tests and will leave the portfolio, locking in a modest gain.
Verdict: Sell
Total return: 5%
As always, I’ll sell the stocks indicated from SIF and my own real-money portfolio after this article has been published.
Disclosure: At the time of publication, Roland owned all shares listed in the SIF portfolio except Pershing Square Holdings.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
I still hold TRIG; actually I sold them this morning when it looked like my holding was to be diluted by over 10% with a placement of shares at over 5.6% discount to the recent share price then bought them back when I thought the RNS was referring to a Rights issue!
But it says "members of the public are not eligible... only .. persons selected by ... the "joint bookrunners" who are "Investment Professionals"... I 'phoned the InfraRed switchboard number given in the RNS but they could not put me through to anyone unless I specified a name or extension.
Maybe I will just hold them now and hope that electricity prices remain high.. at the moment the share price is a few percentage points above that at the June 30th when they fell out of the SIF portfolio.
:-/
On H & T (LON:HAT), you mentioned broker forecasts staying steady.
However, having looked at Research Tree, it looks like neither broker has issued any updates since 2019.... so more a case of outdated broker forecasts than brokers holding their forecasts steady for this year!
The numbers here show outperformance of 18% since April 2016:
I think you are being too modest. Give yourself an extra 6%
Hi Blissgull,
Many thanks for pointing out this schoolboy error... I need to brush up my maths! I'll correct the article.
Roland
Good stuff Roland. I have a crossover with your portfolio so it's doubly helpful. One share we both hold is £FIF. Nice score, understandable business but very little news. I can't quite understand why it has gone down so far and flat-lined. Maybe patience is all that is needed.
Thank you Roland, good report and lots of honesty about how you run the portfolio and how those of us with less time can use a basic set of screening tools to improve our overall performance and generation (and hence acceptance or rejection) of ideas and be more controlled and less emotional through what is likely to be a challenging few months.
T.
Great write-up as ever, Roland.